Stock Analysis · Endeavour Mining Corp (EDVMF)
Overview
Endeavour Mining Corp is a large gold producer focused on West Africa. The company explores for gold, develops mines, operates producing sites, and then sells gold doré bars into the global market. Its portfolio has been built around a group of mines in Côte d’Ivoire, Senegal, and Burkina Faso, with additional development and exploration projects intended to extend mine life and support future output.
For a simple long-term view, this is mainly a business tied to two things: how much gold it can produce at acceptable cost, and what the gold price is when that metal is sold. Unlike a diversified miner, Endeavour is largely concentrated in one commodity, so its operating performance and market value are closely linked to gold.
Its revenue base is straightforward. In public reporting, the company’s sales are overwhelmingly generated by gold production, while smaller amounts can come from by-products or other mining-related items depending on the year and site mix.
- Gold sales: approximately 95% to 100% of revenue. This includes gold produced from the company’s operating mines and sold at prevailing market prices.
- Other mining-related revenue: generally 0% to 5%. This can include minor by-product sales or other limited items, but these are not the economic driver of the group.
That concentration makes the company easy to understand: Endeavour is essentially a gold production platform with a pipeline of mine-life extensions and new projects designed to keep ounces flowing over many years.
The business has gone through a noticeable earnings swing over the past few years. Revenue and operating income were pressured in 2022 through 2024, then improved sharply in 2025 as sales expanded and profitability recovered. The broad message is that this is a cyclical miner, but one that has recently shown strong operating leverage when market conditions and execution line up.
Key Figures
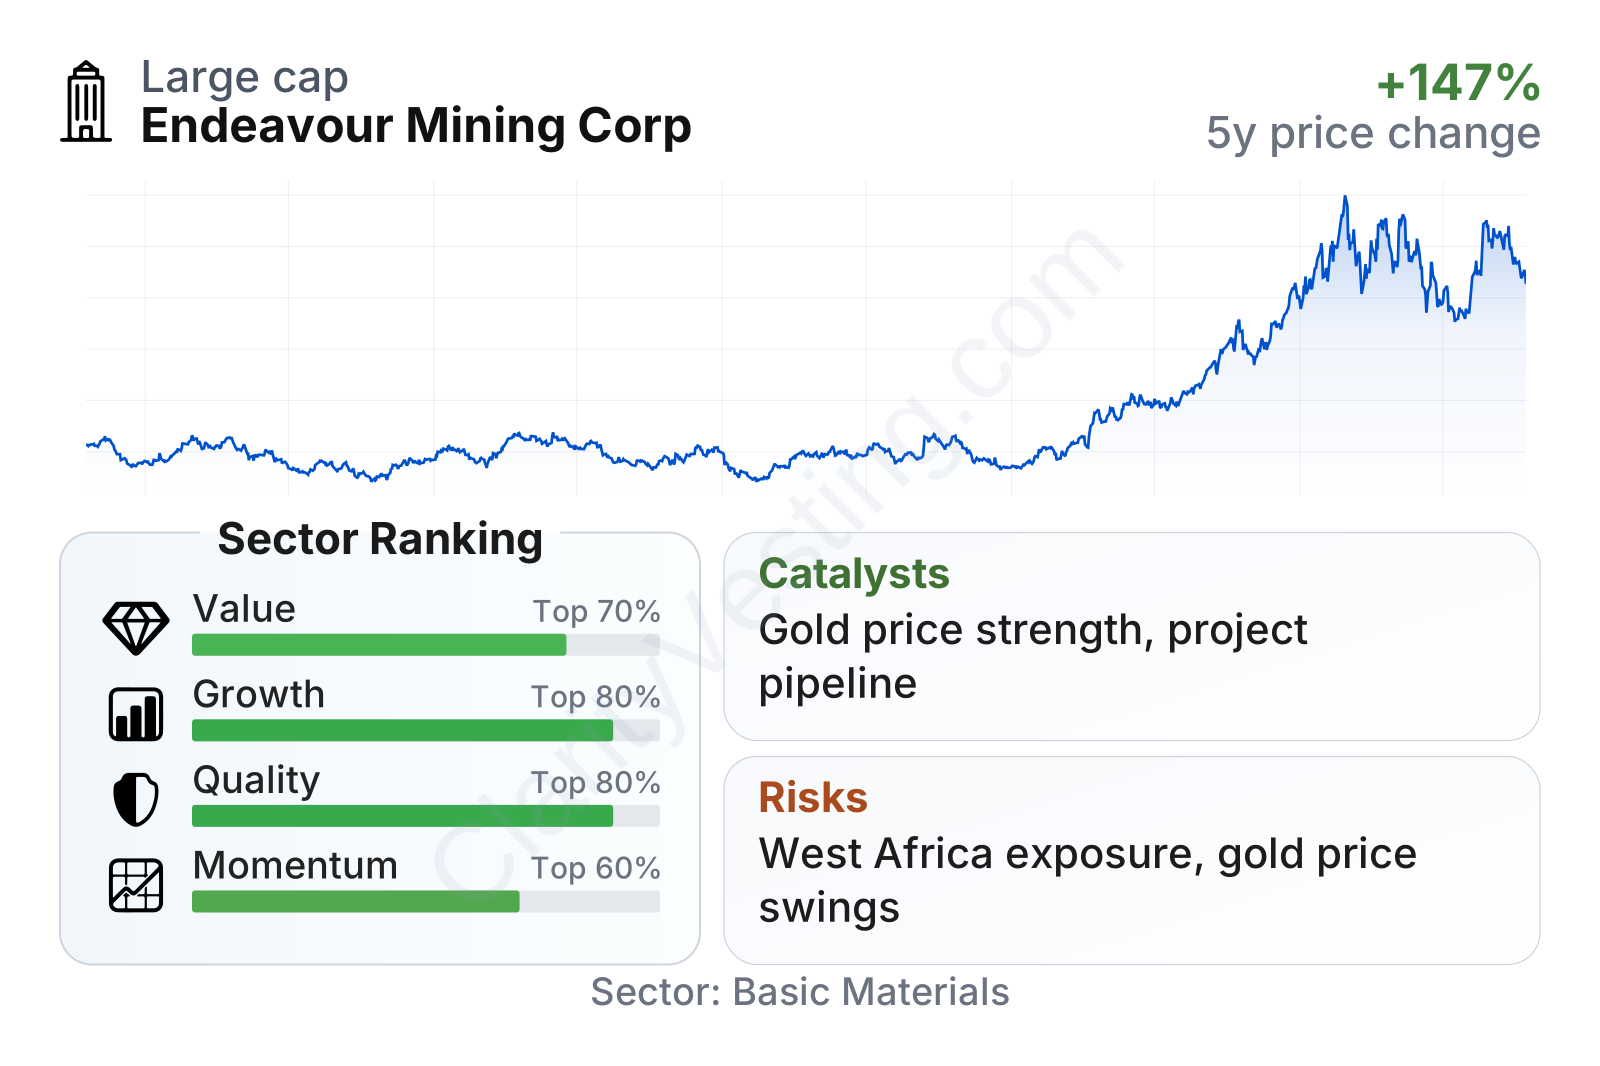
The share price trend has been very strong over the last several years, although the path has not been smooth. That pattern is typical for gold miners: they can rerate quickly when margins improve, but they also tend to remain volatile because sentiment can shift with bullion prices, country risk, and mine-specific news.
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Gold | |
| Market Cap ⓘ | $13.36B | |
| Beta ⓘ | 1.20 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 16.30 | 16.90 |
| P/B Ratio ⓘ | 4.14 | 1.65 |
| FCF Yield ⓘ | 10.73% | 5.76% |
| Dividend Yield ⓘ | 3.29% | 2.13% |
| EBIT / EV ⓘ | 12.50% | 6.30% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 21.00% | 11.10% |
| RPS Growth (5Y CAGR) ⓘ | 11.94% | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | 0.41% | -13.47% |
| BVPS Growth (5Y CAGR) ⓘ | -8.11% | 5.51% |
| Margin Growth (5Y Trend) ⓘ | 15.10% | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | 15.14% | 0.37% |
| DPS Growth (5Y CAGR) ⓘ | 22.96% | 6.08% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 36.94% | 9.26% |
| ROA (Latest) ⓘ | 13.98% | 4.91% |
| ROIC (5Y Median) ⓘ | 5.73% | 7.70% |
| ROA (5Y Median) ⓘ | -0.87% | 3.86% |
| Net Debt / EBIT (Latest) ⓘ | N/A | 1.40 |
| Net Debt / EBIT (5Y Median) ⓘ | 1.71 | 1.70 |
| Net Debt / EBITDA (Latest) ⓘ | N/A | 0.95 |
| Net Debt / Assets ⓘ | N/A | 13.69% |
| EBITDA / Interest ⓘ | 35.42 | 12.34 |
| Operating Margin (Latest) ⓘ | 39.43% | 13.20% |
| Operating Margin (5Y Median) ⓘ | 15.25% | 11.80% |
| Debt to Equity (Latest) ⓘ | N/A | 40.56% |
| Profit Margin (Latest) ⓘ | 17.67% | 6.43% |
| Free Cash Flow (Latest) ⓘ | $1.43B | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +190.06% | +68.89% |
| 12M Return (excl. last month) ⓘ | +64.06% | +30.21% |
| 6M Return ⓘ | -19.22% | -4.16% |
| Price vs. 200-Day MA ⓘ | -6.97% | -1.27% |
On the latest snapshot, Endeavour screens well on growth and quality relative to much of the basic materials universe. Revenue growth, free cash flow generation, operating profitability, and returns on capital stand out. Valuation is more mixed: earnings-based multiples are close to sector norms, while price-to-book is clearly richer, suggesting the market is already recognizing the stronger recent performance and asset quality.
The company is also in the larger end of the gold producer spectrum, with moderate share-price volatility and a dividend yield above the sector median. Strong interest coverage and healthy free cash flow add support to the financial profile, even if mining remains a capital-intensive business by nature.
Growth
Gold remains a relevant long-term sector because it sits at the intersection of jewelry demand, central bank reserve management, inflation protection, and geopolitical uncertainty. That does not make it a conventional growth market like software or semiconductors, but it does mean a well-run producer can expand meaningfully through production growth, reserve replacement, and disciplined capital allocation.
Endeavour’s strategy is sensible for that environment. It has aimed to combine producing assets with a development pipeline, while keeping a meaningful exploration effort around existing operations. For a miner, this matters because growth is not only about selling more in the next quarter; it is also about replacing depleted ounces and preserving mine life over many years.
The recent revenue trend shows a business that moved from contraction to strong expansion. After a difficult phase in 2022 and 2023, growth turned positive in 2024 and accelerated sharply through 2025. Part of that improvement likely reflects stronger gold prices, but it also points to better operating momentum and a more favorable production mix.
Cash generation has also improved after a weaker stretch. Free cash flow moved from positive to negative and then rebounded strongly, which is important because mining profits on paper do not always translate into cash. The latest level of free cash flow is substantial for a company of this size and gives Endeavour more flexibility for dividends, debt management, project spending, and exploration.
A major growth catalyst is project execution. If Endeavour continues advancing its development assets on time and on budget, it can add future production and reduce the pressure that naturally comes from ore depletion at mature mines. Another catalyst is reserve conversion through exploration near existing sites, which is often cheaper and less risky than acquiring entirely new operations.
There is also a broader external catalyst: a supportive gold price backdrop. When gold prices rise, miners with established production and strong margins can see disproportionate gains in earnings and cash flow. Endeavour’s recent operating recovery suggests it has meaningful leverage to that environment.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


