Stock Analysis · New Oriental Education & Technology (EDU)
Overview
New Oriental Education & Technology is a China-based education company that rebuilt its business after the major regulatory reset that reshaped the country’s private tutoring market. Today, the group operates a broader platform centered on non-academic tutoring, educational services, test preparation, study-abroad consulting, adult and language learning, and an increasingly important livestream e-commerce business through East Buy.
The company’s revenue mix has changed meaningfully in the last few years. Traditional K-12 academic tutoring is no longer the core driver it once was. Based on the latest annual disclosures, the main sources of revenue are approximately:
- Educational services and test preparation: about 60% to 65% of revenue. This includes overseas test prep, overseas study consulting, adult and university student programs, and non-academic tutoring such as enrichment courses.
- Private label products and livestream e-commerce: about 30% to 35% of revenue. This activity is mainly carried through East Buy and includes product sales generated through online channels and livestreaming.
- Other educational businesses: about 5% to 10% of revenue. This includes smaller activities such as smart learning systems and related services.
What stands out is that New Oriental is no longer a single-line tutoring company. It now combines education services with a consumer-facing online commerce arm, which has expanded the addressable market but also makes the business model more mixed than before.
The operating profile has also improved sharply since the 2022 restructuring period. Revenue has climbed from roughly $3.1 billion in fiscal 2022 to about $5.7 billion in fiscal 2026, while profitability moved from a deep loss to solid positive earnings. Gross profit has grown steadily, and operating income has recovered even as selling and administrative spending has risen to support expansion.
The business mix shows a clear post-crackdown recovery: sales are well above pre-rebound levels, and earnings have turned positive again. At the same time, the cost base has expanded with the company’s push into newer activities, especially commerce and broader service offerings.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Nov 14, 2026 | |
| Context | ||
| Sector | Consumer Defensive | |
| Industry | Education & Training Services | |
| Market Cap ⓘ | $8.31B | |
| Beta ⓘ | 0.24 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 16.75 | 18.98 |
| P/B Ratio ⓘ | 2.15 | 2.42 |
| FCF Yield ⓘ | 9.30% | 6.95% |
| Dividend Yield ⓘ | 3.73% | 2.68% |
| EBIT / EV ⓘ | 19.36% | 7.79% |
| PEG ⓘ | 0.98 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 23.10% | 4.00% |
| RPS Growth (5Y CAGR) ⓘ | 18.32% | 6.22% |
| EPS Growth (5Y CAGR) ⓘ | 4.82% | -10.65% |
| BVPS Growth (5Y CAGR) ⓘ | 1.33% | 3.24% |
| Margin Growth (5Y Trend) ⓘ | 45.98% | -0.23% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 4.88% |
| DPS Growth (5Y CAGR) ⓘ | 90.84% | 6.57% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 14.26% | 11.61% |
| ROA (Latest) ⓘ | 5.92% | 6.27% |
| ROIC (5Y Median) ⓘ | 8.78% | 10.52% |
| ROA (5Y Median) ⓘ | 4.45% | 5.46% |
| Net Debt / EBIT (Latest) ⓘ | -1.12 | 1.82 |
| Net Debt / EBIT (5Y Median) ⓘ | -1.66 | 2.31 |
| Net Debt / EBITDA (Latest) ⓘ | -1.21 | 1.25 |
| Net Debt / Assets ⓘ | -10.05% | 20.03% |
| EBITDA / Interest ⓘ | N/A | 9.67 |
| Operating Margin (Latest) ⓘ | 13.20% | 8.97% |
| Operating Margin (5Y Median) ⓘ | 10.08% | 9.61% |
| Debt to Equity (Latest) ⓘ | 20.36% | 67.67% |
| Profit Margin (Latest) ⓘ | 8.44% | 5.40% |
| Free Cash Flow (Latest) ⓘ | $772.85M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | -20.80% | +19.66% |
| 12M Return (excl. last month) ⓘ | +11.43% | +3.06% |
| 6M Return ⓘ | +3.96% | +3.17% |
| Price vs. 200-Day MA ⓘ | -0.91% | +2.91% |
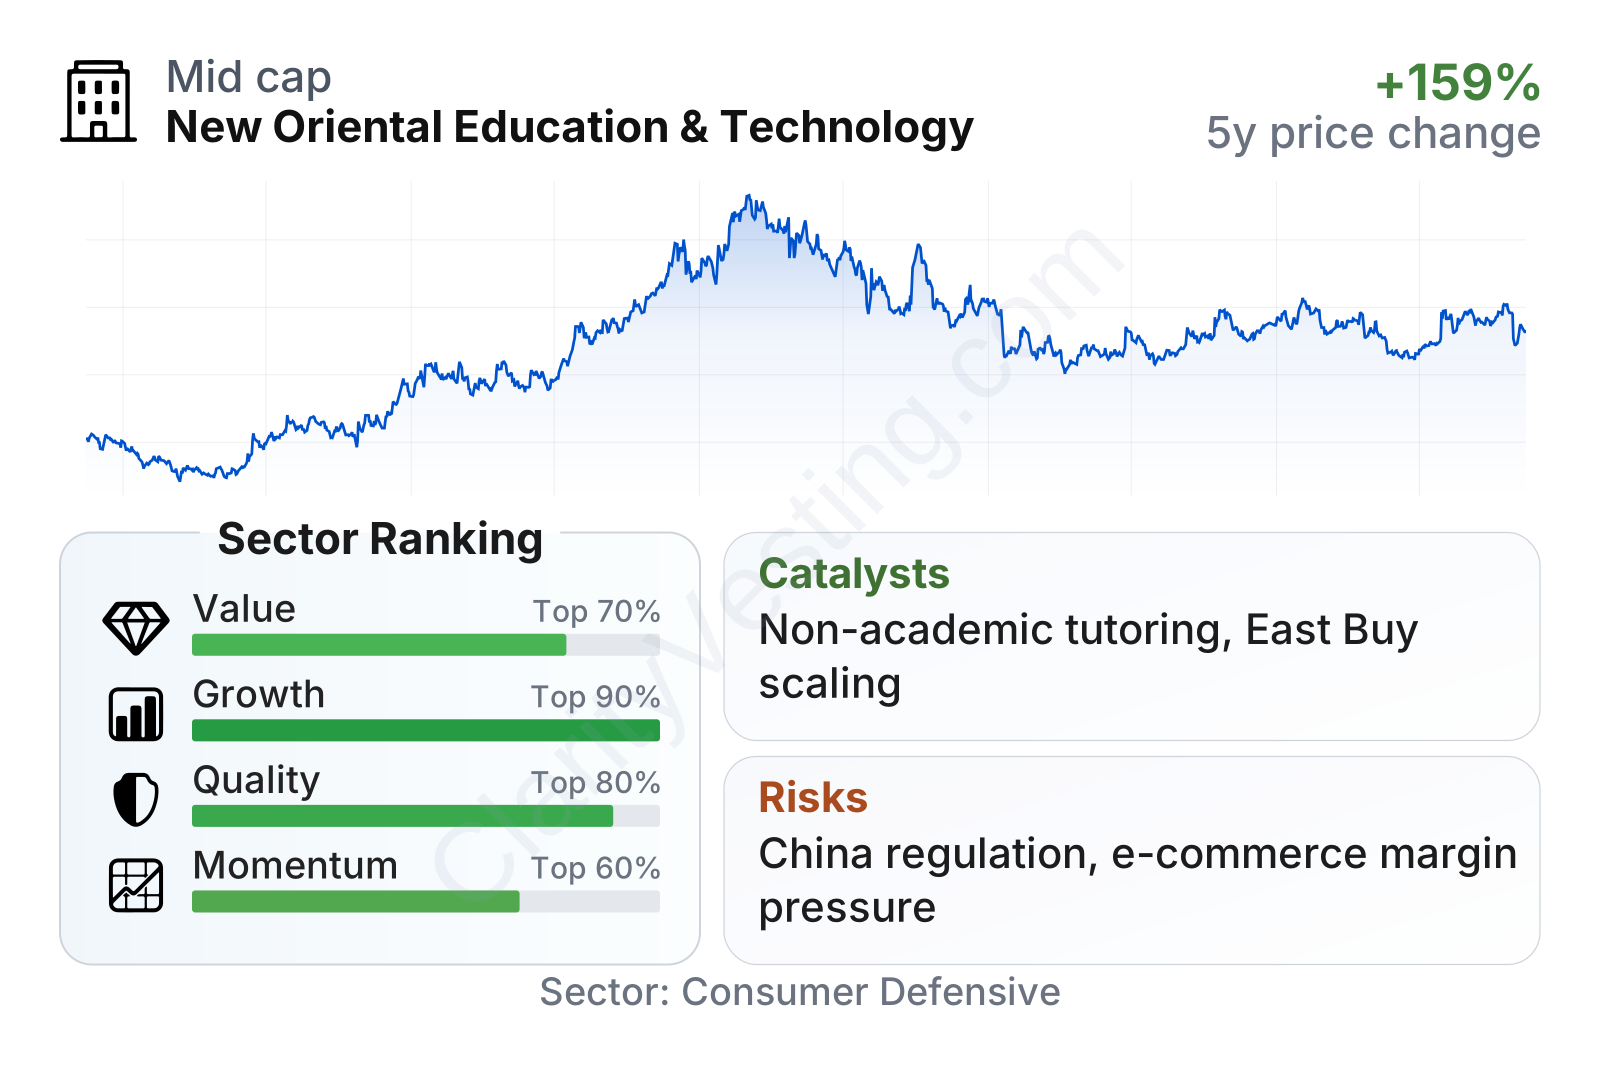
New Oriental currently combines strong growth and solid balance-sheet quality with only middling market momentum. Growth and quality rank high versus the broader sector, helped by above-average revenue expansion, improving margins, and a net cash position. Value metrics are more mixed: earnings valuation is slightly below the sector median, while the price-to-book multiple is higher, reflecting the market’s recognition of the company’s recovery and asset-light earnings potential.
The stock has been volatile over the last few years. After a major rebound from 2022 into 2024, the shares pulled back and have moved more unevenly since then. That pattern suggests the market is still debating how durable the new version of New Oriental is, especially the balance between education and commerce.
Growth
New Oriental operates in a sector with long-term demand, but the shape of that demand has changed. In China, families still spend heavily on education, language training, enrichment, and overseas study support. The difference is that growth is now concentrated in areas permitted by regulation, such as non-academic tutoring, test prep, vocational and adult learning, and adjacent services. That creates room for expansion, but only for companies able to adapt their model quickly.
New Oriental’s strategy broadly makes sense in that context. It has kept its brand, teaching network, and customer relationships, then redirected them toward categories with regulatory room to grow. It also built a second growth engine in East Buy, using brand trust and online reach to enter product sales and livestream commerce. This diversification has helped the company avoid dependence on any single business line.
Revenue growth has been strong since the turnaround. After the collapse during the regulatory reset, the company returned to sustained double-digit expansion, and the most recent year-over-year growth rate remains above 20%. That is far ahead of the sector median and supports the view that New Oriental is still in a recovery-and-expansion phase rather than a mature, low-growth one.
Cash generation also matters here because turnarounds can look better on paper than in cash. In New Oriental’s case, free cash flow recovered sharply after 2022 and has remained solidly positive, recently running in the high hundreds of millions of dollars on a trailing basis. That gives the company flexibility to invest, absorb volatility, and continue returning capital through dividends without leaning on debt.
A meaningful catalyst is the continued scaling of non-academic tutoring and overseas-related services, where the company already has a recognized brand. Another is the potential for East Buy to deepen monetization through product mix, private-label development, and audience retention. Recent company updates have also pointed to branch network expansion and continued enrollment growth in core education programs, which reinforces the idea that the rebound is not coming from only one segment.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


