Stock Analysis · Ecovyst Inc (ECVT)
Overview
Ecovyst Inc is a specialty chemicals company that supplies catalysts, silica-based materials, and sulfuric acid recycling services used in refining, petrochemicals, emissions control, packaging, consumer products, and infrastructure-related markets. In simple terms, the company makes materials that help other industrial customers run chemical processes more efficiently, clean up emissions, and manufacture products ranging from plastics to household goods.
Its business is mainly organized around two operating segments. Based on recent company reporting, revenue is led by Ecoservices, with Advanced Materials as the second-largest contributor. The exact mix can move by year because sulfuric acid pricing, customer demand, and product mix are volatile, but the business is broadly split as follows:
- Ecoservices: approximately 55% to 65% of revenue in recent periods. This segment regenerates and recycles spent sulfuric acid for refineries and also sells virgin sulfuric acid used in industrial applications.
- Advanced Materials & Catalysts-related products: approximately 35% to 45% of revenue. This includes silica catalysts, zeolites, and specialty materials used in polyethylene production, refining, emissions applications, and other industrial processes.
The business model has two attractive features for long-term analysis. First, many of Ecovyst’s products are not optional line items for customers; they are embedded in industrial processes. Second, acid recycling and process catalysts can create recurring demand because customers need continuous supply and service rather than one-time purchases.
At the same time, the company is not a simple volume growth story. Revenue and earnings can swing with industrial production, refinery activity, raw material costs, plant utilization, and the timing of customer orders. The profit flow over the last several years shows this clearly: sales have held up better than net income, while interest costs and margin pressure have had a meaningful effect on bottom-line results.
The multi-year operating picture suggests a business with decent gross profit generation but uneven conversion into net income. Revenue recovered from the 2023 dip and improved again in 2024 and 2025, yet profitability was much less stable because of higher costs, interest burden, and weaker margins.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Specialty Chemicals | |
| Market Cap ⓘ | $1.10B | |
| Beta ⓘ | 1.06 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 43.83 | 16.90 |
| P/B Ratio ⓘ | 1.87 | 1.65 |
| FCF Yield ⓘ | 6.54% | 5.76% |
| Dividend Yield ⓘ | N/A | 2.13% |
| EBIT / EV ⓘ | 4.97% | 6.30% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 42.00% | 11.10% |
| RPS Growth (5Y CAGR) ⓘ | 8.89% | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | -23.59% | -13.47% |
| BVPS Growth (5Y CAGR) ⓘ | -0.82% | 5.51% |
| Margin Growth (5Y Trend) ⓘ | -0.04% | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | -0.00% | 0.37% |
| DPS Growth (5Y CAGR) ⓘ | -31.66% | 6.08% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 3.66% | 9.26% |
| ROA (Latest) ⓘ | -3.89% | 4.91% |
| ROIC (5Y Median) ⓘ | 2.21% | 7.70% |
| ROA (5Y Median) ⓘ | -0.37% | 3.86% |
| Net Debt / EBIT (Latest) ⓘ | 5.80 | 1.40 |
| Net Debt / EBIT (5Y Median) ⓘ | 6.41 | 1.70 |
| Net Debt / EBITDA (Latest) ⓘ | 2.86 | 0.95 |
| Net Debt / Assets ⓘ | 32.28% | 13.69% |
| EBITDA / Interest ⓘ | 6.66 | 12.34 |
| Operating Margin (Latest) ⓘ | 9.09% | 13.20% |
| Operating Margin (5Y Median) ⓘ | 8.33% | 11.80% |
| Debt to Equity (Latest) ⓘ | 93.10% | 40.56% |
| Profit Margin (Latest) ⓘ | -7.06% | 6.43% |
| Free Cash Flow (Latest) ⓘ | $72.21M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +6.21% | +68.89% |
| 12M Return (excl. last month) ⓘ | +7.78% | +30.21% |
| 6M Return ⓘ | -29.50% | -4.16% |
| Price vs. 200-Day MA ⓘ | -16.11% | -1.27% |
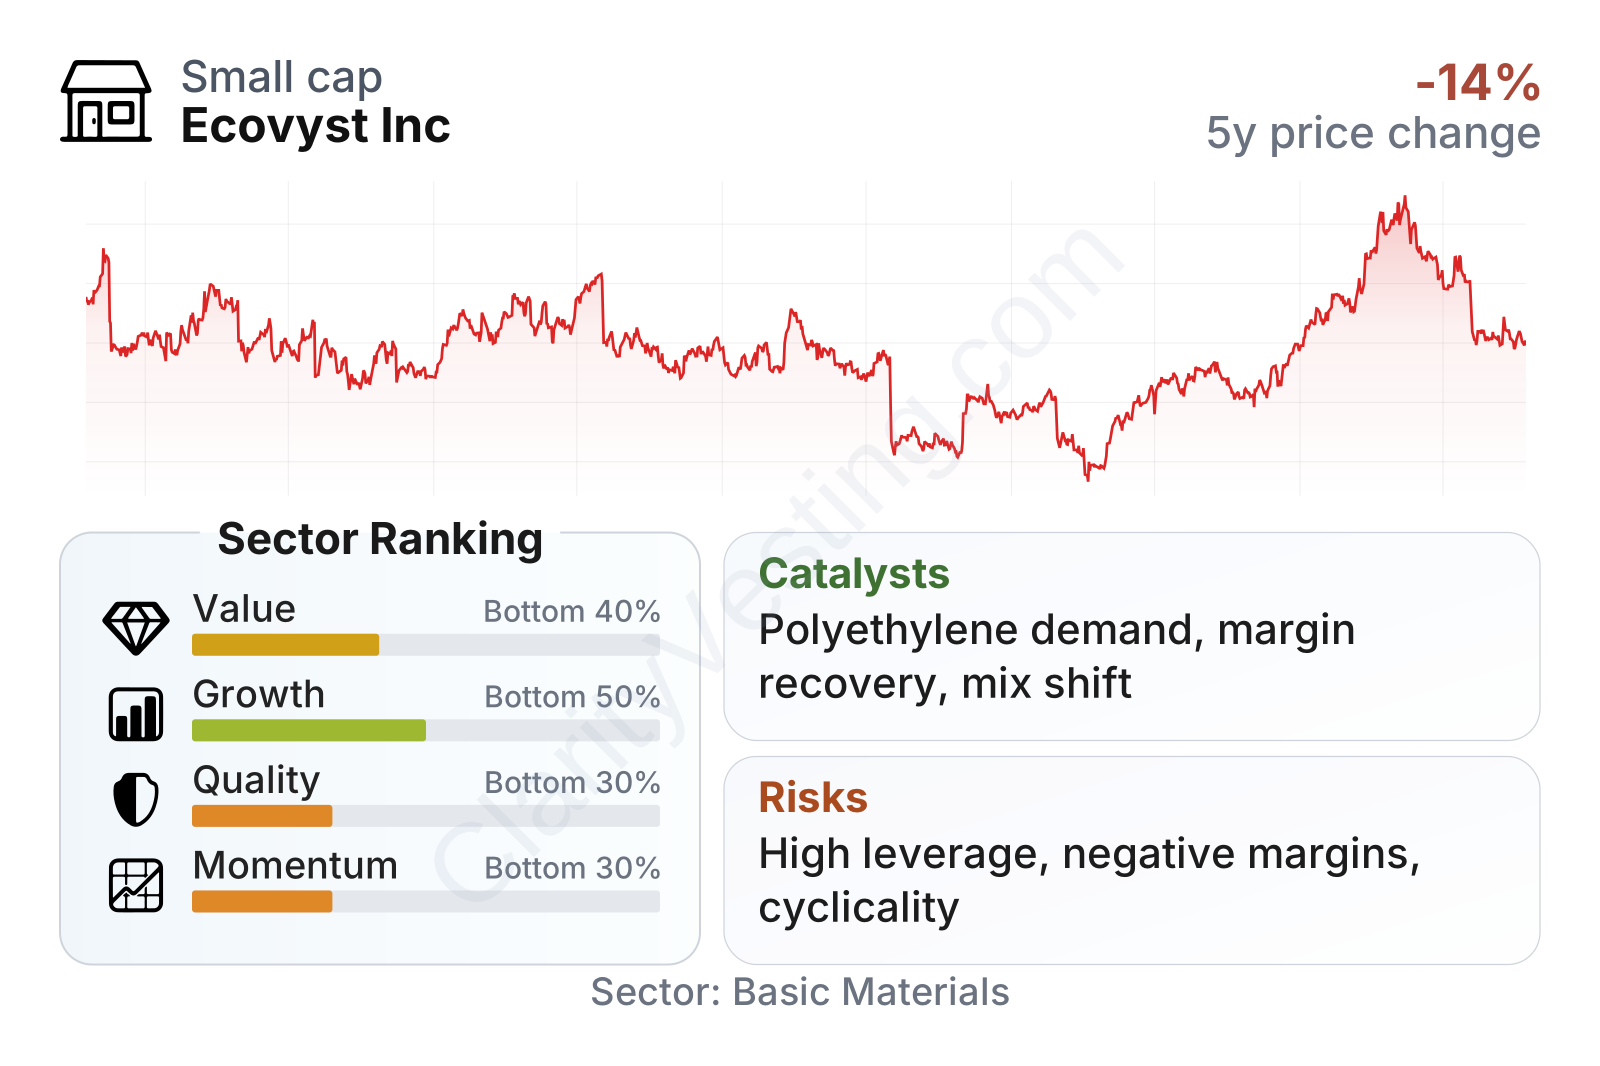
Ecovyst is a small-cap specialty chemicals company with a stock that has been notably volatile over the last few years. The share price improved sharply into early 2026 before giving back part of that move, which fits a business exposed to cyclical industrial demand and changing expectations around margins.
The latest factor profile is mixed. On valuation, the company does not screen as obviously cheap on earnings, with a P/E far above the sector median, although free cash flow yield is somewhat better than the sector median. On quality, the picture is weaker: returns on capital are below industry norms, leverage is elevated, and the latest profit margin is negative. Growth metrics are also uneven. Recent revenue growth has accelerated strongly, but longer-term earnings growth has been weak and book value growth has lagged the sector. Momentum remains soft versus peers despite the rebound seen earlier in 2026.
Growth
Ecovyst operates in parts of the chemical industry that still have structural relevance. Refiners need sulfuric acid regeneration to reduce waste and support fuel production, while petrochemical and plastics producers rely on catalysts and silica materials to improve efficiency and product performance. Those are not fashionable end markets, but they are essential ones. That matters for long-term durability.
The company’s strategy also makes industrial sense. Its Ecoservices network is based on specialized regeneration plants located near customer operations, which can create sticky relationships and logistical advantages. In Advanced Materials, management has focused on higher-value applications such as polyethylene catalysts and silica products serving packaging and specialty uses rather than competing only on bulk chemical volume.
Growth has recently turned more favorable after a weak period. Revenue was under pressure through much of 2023 and parts of 2024, then reaccelerated meaningfully in late 2025 and the first half of 2026. The latest year-over-year growth rates are far ahead of the sector median, which suggests either a demand recovery, improved pricing and mix, or both. That is encouraging, although one strong stretch does not erase the company’s history of uneven growth.
Cash generation adds an important layer to the growth discussion. Free cash flow has remained positive over time, even though it has not followed a smooth upward path. Trailing free cash flow sits in the tens of millions of dollars, showing that the company still converts a meaningful portion of its operations into cash despite weak accounting earnings. For a capital-intensive chemical business, that is a more constructive signal than net income alone.
One notable catalyst in the current setup is the possibility that stronger polyethylene and refining activity could improve utilization across Ecovyst’s network. Another is the company’s ability to shift mix toward higher-value catalyst and specialty materials applications. If those trends continue, revenue growth could translate into better operating leverage than the market currently assumes.
Recent company communications have also emphasized optimization projects, capacity initiatives, and efforts to improve segment mix. None of these items guarantees a step-change, but together they point to a business trying to become less dependent on commodity-like swings and more focused on applications where technical know-how matters.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


