Stock Analysis · Ecolab Inc (ECL)
Overview
Ecolab is a global specialty chemicals and services company focused on water, hygiene, and infection prevention. In simple terms, it helps customers use water and energy more efficiently, keep facilities clean and safe, and protect food, healthcare, and industrial processes. Its products and services are used in places such as restaurants, hotels, hospitals, data centers, factories, paper mills, refineries, and large commercial buildings.
The business model is broader than just selling chemicals. Ecolab combines consumable products, dosing and monitoring equipment, and recurring service relationships. That matters because customers often rely on Ecolab as part of daily operations rather than as an occasional supplier. The company also has a large installed base and significant field-service reach, which supports repeat business.
Based on recent company reporting, the main revenue sources are organized by business segment as follows:
- Global Industrial: approximately 44% of revenue. This includes water treatment, process chemicals, and digital monitoring solutions for manufacturing, food and beverage plants, paper, power, refining, petrochemicals, and other industrial customers.
- Global Institutional & Specialty: approximately 40% of revenue. This segment serves restaurants, hotels, healthcare facilities, schools, and other institutions with cleaning, sanitizing, kitchen, laundry, and infection-prevention solutions.
- Global Healthcare & Life Sciences: approximately 11% of revenue. This includes infection prevention, surgical and endoscopy solutions, and contamination-control offerings for healthcare and pharmaceutical environments.
- Pest Elimination: approximately 5% of revenue. This unit provides pest detection, prevention, and treatment services for foodservice, hospitality, retail, and industrial sites.
Geographically, Ecolab is a diversified international company, with the United States remaining its largest market and substantial operations across Europe, Asia-Pacific, Latin America, India, the Middle East, and Africa.
The overall revenue mix also shows a useful quality for long-term analysis: a large share comes from routine, compliance-related, or mission-critical activities such as sanitation, water treatment, and contamination control. These are usually harder for customers to delay than more discretionary purchases.
Over the past several years, revenue has increased from roughly $12.7 billion to more than $16.0 billion. At the same time, gross profit and operating income improved meaningfully, showing that recent growth has not come only from higher sales volume, but also from stronger profitability and better cost absorption.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Specialty Chemicals | |
| Market Cap ⓘ | $80.08B | |
| Beta ⓘ | 0.88 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 38.34 | 16.90 |
| P/B Ratio ⓘ | 8.12 | 1.65 |
| FCF Yield ⓘ | 2.34% | 5.76% |
| Dividend Yield ⓘ | 1.00% | 2.13% |
| EBIT / EV ⓘ | 3.33% | 6.30% |
| PEG ⓘ | 2.49 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 9.70% | 11.10% |
| RPS Growth (5Y CAGR) ⓘ | 6.37% | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | -4.42% | -13.47% |
| BVPS Growth (5Y CAGR) ⓘ | 8.22% | 5.51% |
| Margin Growth (5Y Trend) ⓘ | 4.54% | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | 7.63% | 0.37% |
| DPS Growth (5Y CAGR) ⓘ | 7.77% | 6.08% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 12.04% | 9.26% |
| ROA (Latest) ⓘ | 7.86% | 4.91% |
| ROIC (5Y Median) ⓘ | 10.45% | 7.70% |
| ROA (5Y Median) ⓘ | 6.34% | 3.86% |
| Net Debt / EBIT (Latest) ⓘ | 2.99 | 1.40 |
| Net Debt / EBIT (5Y Median) ⓘ | 3.70 | 1.70 |
| Net Debt / EBITDA (Latest) ⓘ | 2.39 | 0.95 |
| Net Debt / Assets ⓘ | 28.80% | 13.69% |
| EBITDA / Interest ⓘ | 11.90 | 12.34 |
| Operating Margin (Latest) ⓘ | 17.08% | 13.20% |
| Operating Margin (5Y Median) ⓘ | 13.77% | 11.80% |
| Debt to Equity (Latest) ⓘ | 136.77% | 40.56% |
| Profit Margin (Latest) ⓘ | 12.57% | 6.43% |
| Free Cash Flow (Latest) ⓘ | $1.87B | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +80.25% | +68.89% |
| 12M Return (excl. last month) ⓘ | +2.14% | +30.21% |
| 6M Return ⓘ | +5.91% | -4.16% |
| Price vs. 200-Day MA ⓘ | +5.28% | -1.27% |
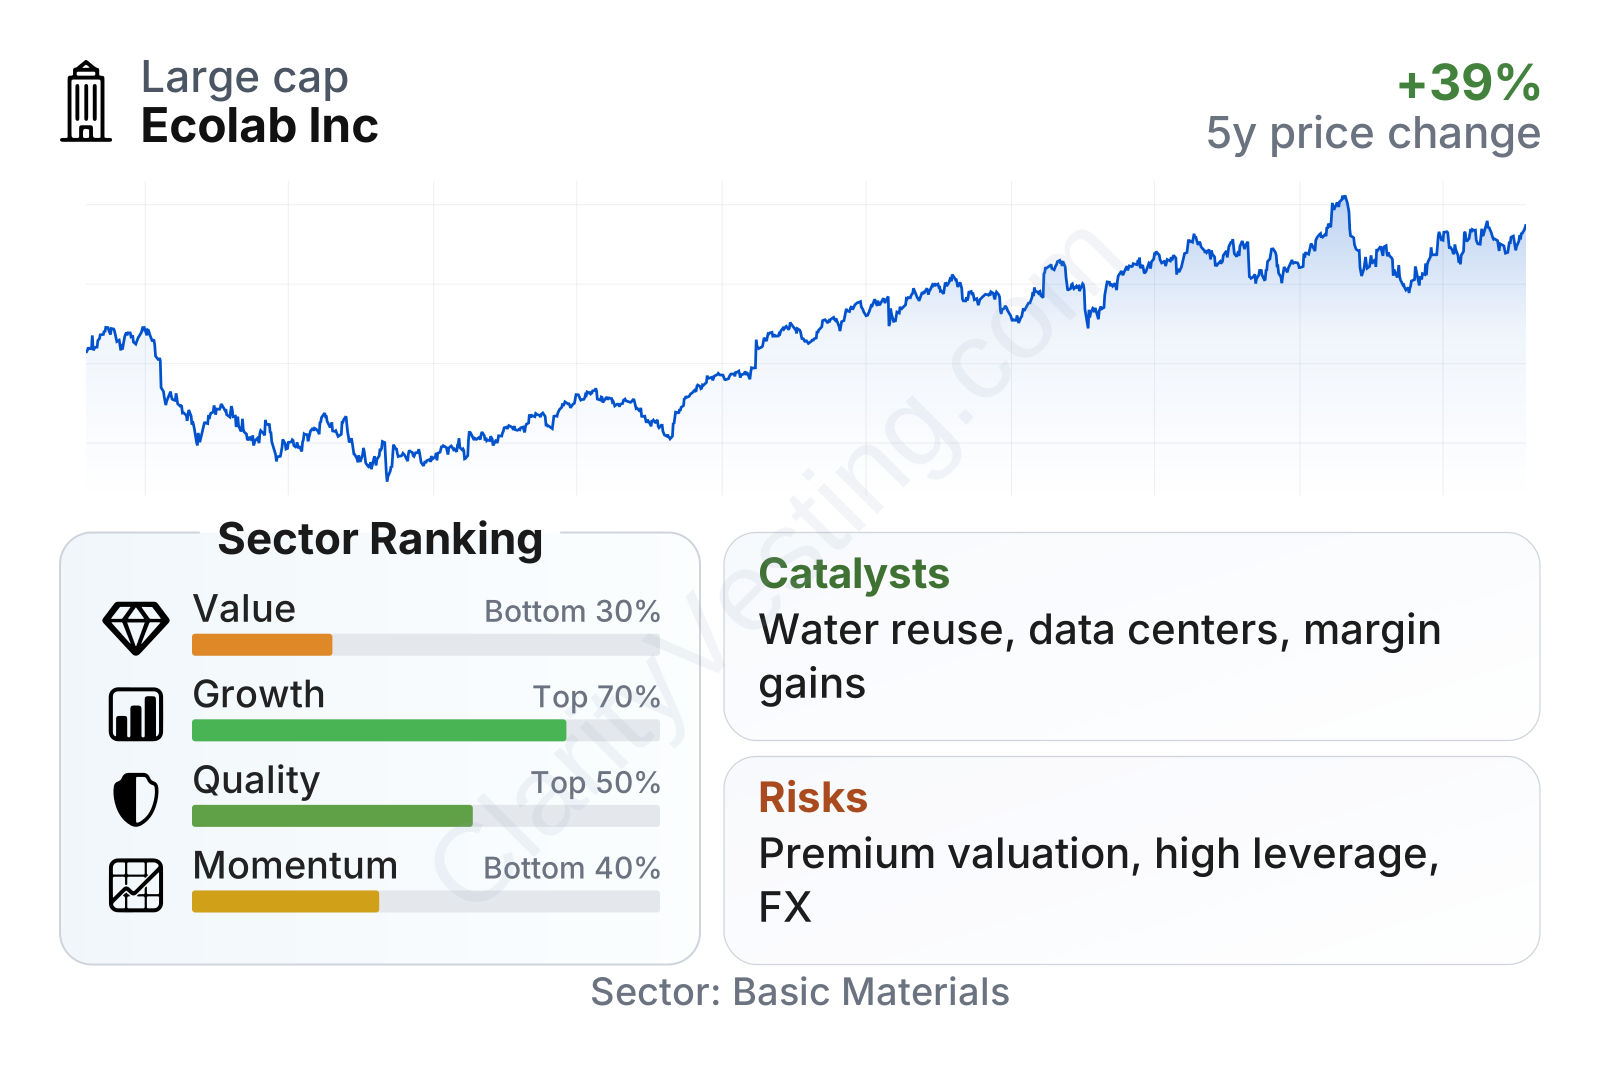
Ecolab is a very large company with a market value in the tens of billions of dollars and a stock that has historically moved a bit less than the broader market, as indicated by a beta below 1. In the factor summary, quality looks stronger than value: profitability metrics are solid versus the sector, while valuation ratios are clearly richer than typical specialty chemical peers. Growth is respectable rather than exceptional, helped by improving margins and free cash flow over multi-year periods. Recent share-price momentum has been softer than much of the sector even though the longer-term stock performance remains positive.
Growth
Ecolab operates in attractive long-term markets. Water scarcity, tighter hygiene standards, food safety requirements, rising healthcare sterilization needs, and industrial efficiency targets all support demand for what the company sells. These are durable themes rather than short-lived trends. Many customers also face higher pressure to reduce water use, lower energy intensity, and document compliance, which plays directly into Ecolab’s service-heavy model.
The company’s strategy appears coherent for future expansion. It is not trying to win through commodity chemicals alone; instead, it builds integrated relationships around chemistry, equipment, software, and on-site service. That combination can make switching less convenient for customers and can support pricing, especially where downtime, contamination, or non-compliance would be costly.
Recent sales growth has re-accelerated after a slower period. Year-over-year revenue growth moved from low single digits and even a brief decline in 2025 to roughly 10% in the most recent quarters. That is close to, though still somewhat below, the sector median on the latest reading. The more important point is the direction: growth regained momentum after a period of normalization.
Cash generation also supports the growth case. Free cash flow has remained substantial, recently around $1.9 billion on a trailing basis, after moving through a more uneven period. Over five years, free cash flow growth has been well ahead of the sector median, suggesting that Ecolab has been improving not only its income statement but also its ability to turn operations into cash.
Several business-specific catalysts stand out. The company continues to benefit from demand for water reuse, digital monitoring, and treatment solutions in industrial sites and data centers, where cooling and water management are becoming increasingly important. Its healthcare and life sciences activities also fit well with ongoing demand for contamination control and more stringent cleaning standards. In addition, margin expansion in recent years shows that internal execution has been contributing alongside end-market demand.
Recent company updates have also pointed to continued emphasis on high-growth and high-return areas such as water, life sciences, and digital solutions. That focus matters because these categories tend to be less cyclical than some industrial chemical niches and may carry stronger competitive differentiation.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


