Stock Analysis · DXP Enterprises Inc (DXPE)
Overview
DXP Enterprises is an industrial distribution company that sells equipment, replacement parts, and technical services to businesses that run factories, energy infrastructure, transportation systems, and other heavy operations. In simple terms, it helps industrial customers keep critical equipment working by supplying products such as pumps, bearings, power transmission parts, industrial supplies, and safety-related items, while also providing maintenance, repair, and engineering support.
The company organizes its business into three main segments. Based on recent company filings, revenue is spread roughly as follows:
- Service Centers — about 69%: This is the largest business. It includes maintenance, repair, and operating products, rotating equipment, bearings, power transmission products, metalworking tools, safety supplies, and other everyday industrial needs sold through local branches and service locations.
- Innovative Pumping Solutions — about 19%: This segment focuses on pumping systems, custom-engineered packages, process equipment, fabrication, installation support, and aftermarket service. It is especially tied to applications where fluid handling is mission-critical.
- Supply Chain Services — about 12%: This business manages inventory and procurement for customers, including onsite storerooms, integrated supply arrangements, and other programs designed to simplify purchasing and reduce downtime.
That mix matters because it shows DXP is not a single-product company. A large base of recurring replacement-part demand supports the business, while engineered systems and supply-chain contracts can deepen customer relationships and increase switching costs.
Over the last several years, the company’s revenue, gross profit, and operating income have all moved meaningfully higher. At the same time, interest expense has also increased, which is an important detail because it shows growth has come with a heavier debt load.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Industrials | |
| Industry | Industrial Distribution | |
| Market Cap ⓘ | $2.65B | |
| Beta ⓘ | 1.04 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 30.03 | 22.29 |
| P/B Ratio ⓘ | 5.37 | 1.98 |
| FCF Yield ⓘ | 4.48% | 6.26% |
| Dividend Yield ⓘ | N/A | 1.92% |
| EBIT / EV ⓘ | 5.26% | 4.83% |
| PEG ⓘ | 0.55 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 15.60% | 9.30% |
| RPS Growth (5Y CAGR) ⓘ | 21.50% | 7.76% |
| EPS Growth (5Y CAGR) ⓘ | 5.06% | -13.17% |
| BVPS Growth (5Y CAGR) ⓘ | 13.80% | 6.13% |
| Margin Growth (5Y Trend) ⓘ | 5.30% | 0.74% |
| FCF Growth (5Y CAGR) ⓘ | 14.79% | 10.79% |
| DPS Growth (5Y CAGR) ⓘ | 4.75% | 9.41% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 10.93% | 10.75% |
| ROA (Latest) ⓘ | 5.80% | 5.41% |
| ROIC (5Y Median) ⓘ | 11.25% | 9.37% |
| ROA (5Y Median) ⓘ | 5.58% | 4.95% |
| Net Debt / EBIT (Latest) ⓘ | 3.52 | 2.04 |
| Net Debt / EBIT (5Y Median) ⓘ | 3.77 | 2.27 |
| Net Debt / EBITDA (Latest) ⓘ | 2.85 | 1.39 |
| Net Debt / Assets ⓘ | 38.00% | 19.27% |
| EBITDA / Interest ⓘ | 3.66 | 9.58 |
| Operating Margin (Latest) ⓘ | 8.94% | 10.49% |
| Operating Margin (5Y Median) ⓘ | 8.26% | 10.30% |
| Debt to Equity (Latest) ⓘ | 166.25% | 64.82% |
| Profit Margin (Latest) ⓘ | 4.36% | 6.67% |
| Free Cash Flow (Latest) ⓘ | $118.66M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +446.28% | +67.77% |
| 12M Return (excl. last month) ⓘ | +62.07% | +12.05% |
| 6M Return ⓘ | +10.59% | 0.00% |
| Price vs. 200-Day MA ⓘ | +11.18% | +0.67% |
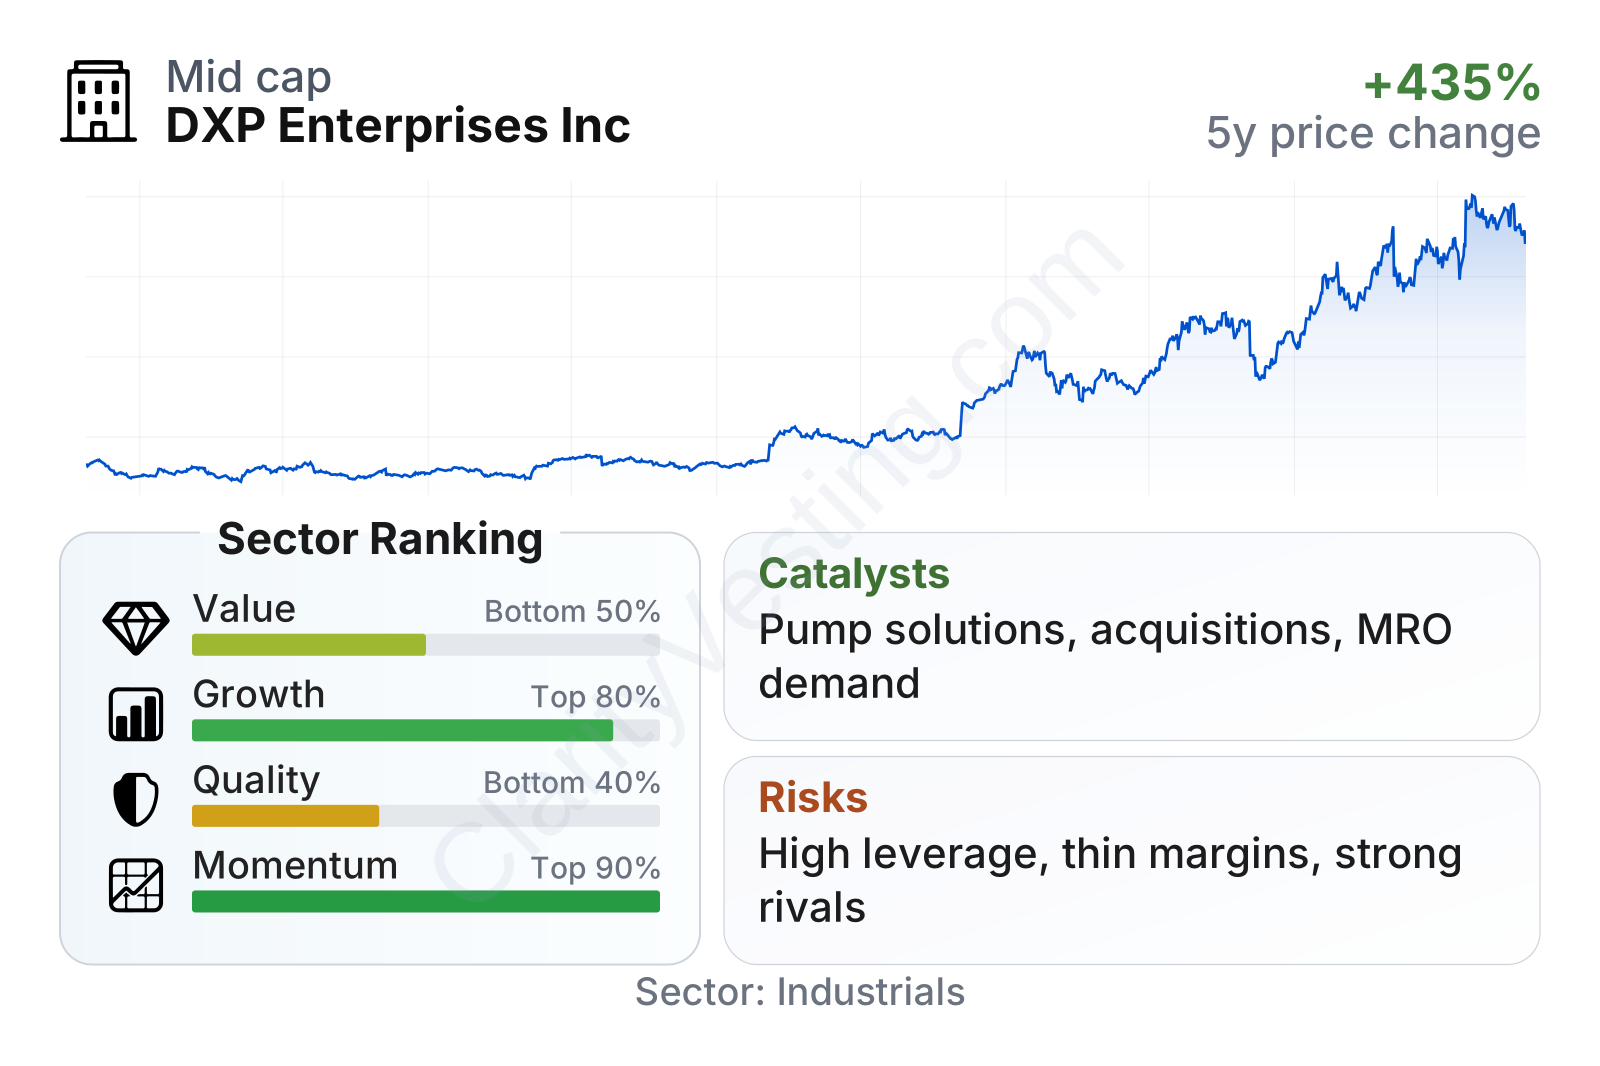
DXP is a mid-sized industrial distributor with a stock that has shown very strong momentum compared with most companies in its sector. Growth measures rank well above average, supported by solid multi-year expansion in revenue, earnings, book value, and free cash flow. Quality is more mixed: returns on capital are around sector norms, but leverage is notably higher than typical peers and margins remain below the broader industrial median. On valuation, the shares trade at a premium on earnings and book value, so the market is clearly pricing in continued execution.
Growth
DXP operates in a part of the economy that tends to benefit from long-lived industrial demand rather than short product cycles. Companies still need pumps, bearings, fluid-handling systems, safety supplies, and maintenance support regardless of whether they are expanding capacity or simply keeping existing facilities online. That creates a durable backdrop, especially in markets such as energy, manufacturing, water, transportation, and general industrial maintenance.
The company’s strategy also looks coherent for long-term expansion. Its model combines local distribution, technical know-how, and service capability. That combination is useful because industrial customers often value reliability and speed more than just the lowest price. DXP has also used acquisitions for years to add product categories, broaden geography, and strengthen specialized capabilities, particularly in higher-value technical niches.
Revenue growth has cooled from the exceptional post-2021 rebound period, but it has remained positive overall and still sits above the sector median. That suggests the company is not merely riding a one-time recovery; it is still expanding faster than many peers even after growth normalized.
Cash generation has been uneven from year to year, which is common in distribution businesses because inventory and working capital can move around, but the broader direction has improved. Free cash flow remains meaningful in absolute terms, giving the company room to support acquisitions, debt service, and internal investment.
A notable catalyst is DXP’s exposure to replacement demand and operational uptime. When customers need equipment repaired quickly, established distributors with technical staff and local inventory can gain share. Another catalyst is the company’s specialized pumping and engineered-solutions business, which can carry better customer stickiness than basic product resale alone. If management continues integrating acquisitions effectively while sustaining above-sector revenue growth, that could further strengthen scale and cross-selling opportunities.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


