Stock Analysis · Leonardo DRS Inc (DRS)
Overview
Leonardo DRS is a U.S. defense electronics and military systems company. It designs and builds equipment used by the U.S. armed forces and allied militaries, with a focus on sensing, computing, power and propulsion, force protection, and naval systems. In simple terms, the company sells the “brains and hardware” that help military platforms detect threats, process information, move power, and survive in combat environments. Its products are typically embedded in larger defense programs, which can create long contracts and recurring follow-on work.
The business is organized around two main segments, and recent annual reporting shows revenue is fairly balanced between them.
- Advanced Sensing and Computing: approximately 50% to 55% of revenue. This includes infrared sensing, electro-optical systems, intelligence and mission computing, network computing, and battlefield communications and decision-support technologies.
- Integrated Mission Systems: approximately 45% to 50% of revenue. This includes naval power and propulsion, electric power conversion, shipboard systems, tactical radars, force protection, and other integrated defense platforms and subsystems.
A large majority of sales come from the U.S. Department of Defense, with a smaller contribution from international customers and commercial or other government work. That concentration is common in defense, but it means Leonardo DRS is closely tied to U.S. procurement priorities. The company’s scale is mid-sized within aerospace and defense: large enough to participate in major programs, but still much smaller than the industry’s prime contractors.
The financial flow over recent years shows a useful pattern: revenue has moved up from roughly $2.9 billion in 2021 to about $3.6 billion in 2025, while gross profit and net income also trended higher. Interest expense has dropped materially over that period, which supports earnings quality.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Industrials | |
| Industry | Aerospace & Defense | |
| Market Cap ⓘ | $9.06B | |
| Beta ⓘ | 0.16 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 28.52 | 22.29 |
| P/B Ratio ⓘ | 3.26 | 1.98 |
| FCF Yield ⓘ | 4.01% | 6.26% |
| Dividend Yield ⓘ | 1.02% | 1.92% |
| EBIT / EV ⓘ | 4.00% | 4.83% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 10.10% | 9.30% |
| RPS Growth (5Y CAGR) ⓘ | -9.07% | 7.76% |
| EPS Growth (5Y CAGR) ⓘ | -28.76% | -13.17% |
| BVPS Growth (5Y CAGR) ⓘ | -1.94% | 6.13% |
| Margin Growth (5Y Trend) ⓘ | 1.27% | 0.74% |
| FCF Growth (5Y CAGR) ⓘ | 17.77% | 10.79% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 9.41% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 11.23% | 10.75% |
| ROA (Latest) ⓘ | 7.63% | 5.41% |
| ROIC (5Y Median) ⓘ | 8.81% | 9.37% |
| ROA (5Y Median) ⓘ | 5.26% | 4.95% |
| Net Debt / EBIT (Latest) ⓘ | -0.01 | 2.04 |
| Net Debt / EBIT (5Y Median) ⓘ | 0.13 | 2.27 |
| Net Debt / EBITDA (Latest) ⓘ | -0.01 | 1.39 |
| Net Debt / Assets ⓘ | -0.07% | 19.27% |
| EBITDA / Interest ⓘ | 70.86 | 9.58 |
| Operating Margin (Latest) ⓘ | 10.56% | 10.49% |
| Operating Margin (5Y Median) ⓘ | 8.81% | 10.30% |
| Debt to Equity (Latest) ⓘ | 9.53% | 64.82% |
| Profit Margin (Latest) ⓘ | 8.52% | 6.67% |
| Free Cash Flow (Latest) ⓘ | $363.00M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +82.84% | +67.77% |
| 12M Return (excl. last month) ⓘ | -7.63% | +12.05% |
| 6M Return ⓘ | -21.11% | 0.00% |
| Price vs. 200-Day MA ⓘ | -19.51% | +0.67% |
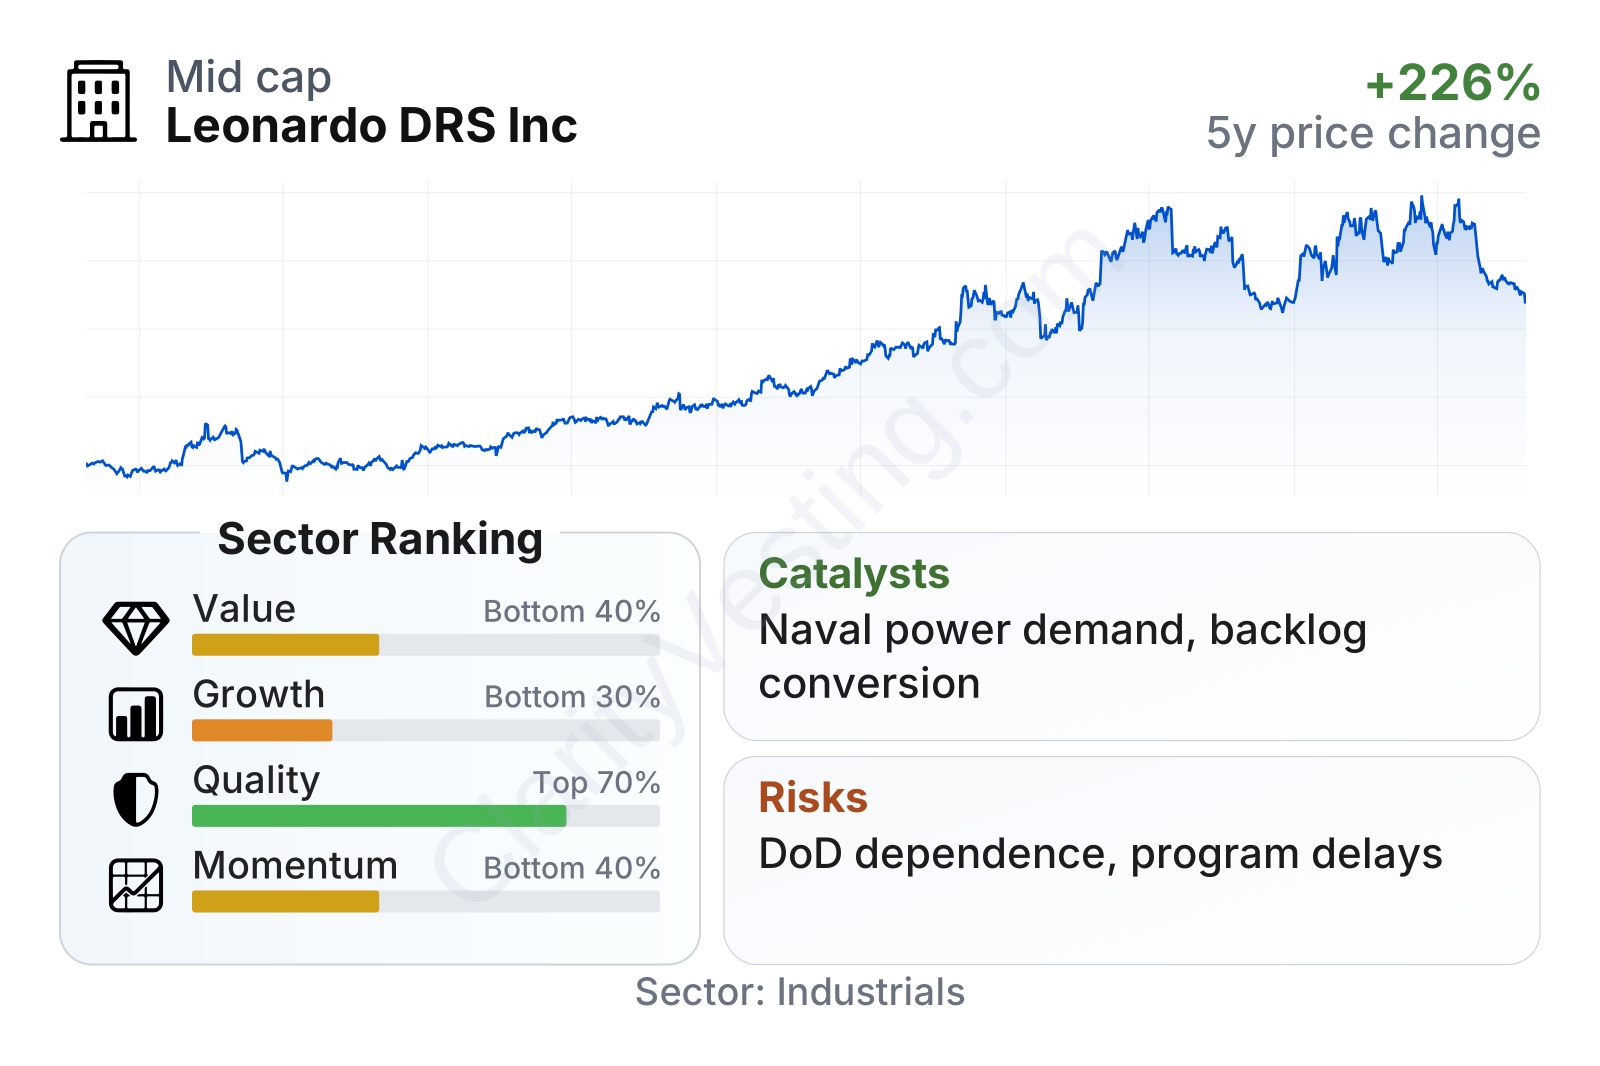
Leonardo DRS combines a relatively defensive share-price profile with a mixed fundamental ranking. Its beta is very low, meaning the stock has historically moved less than the broader market. Quality metrics are solid, helped by returns on capital around sector norms, a profit margin above the industry median, and an exceptionally light debt burden. The weaker area is valuation: earnings and book-value multiples sit above sector medians, while free-cash-flow yield and dividend yield are below many peers. Growth is also uneven depending on the time frame. Recent revenue growth is slightly ahead of the sector median, but longer-term per-share growth measures are less attractive because of earlier volatility and the company’s changing earnings base since becoming public.
Growth
The company operates in a sector with durable long-cycle demand. Defense spending has remained supported by U.S. modernization priorities, naval investment, electronic warfare needs, air and missile defense requirements, and broader geopolitical tension. Those themes are favorable for suppliers of sensing, power conversion, and mission systems, especially when their products are embedded in programs that are hard to replace once qualified.
Leonardo DRS’s current strategy is coherent with those trends. Management has emphasized areas such as advanced sensing, battlefield networking, electric power and propulsion, and naval systems. These are not fringe products; they sit in categories where defense customers increasingly want more processing power, better survivability, and more electrification across platforms. The company has also expanded through acquisitions in recent years to deepen its position in next-generation military technology and improve access to higher-priority programs.
Revenue growth has improved meaningfully since the softer period in 2022. Over the last several quarters, year-over-year growth has generally stayed positive and often landed in the mid-single-digit to high-teen range. The latest pace is around 10%, slightly above the sector median. That matters because defense companies are often judged less by one strong quarter than by whether they can sustain steady delivery growth over multi-year program cycles.
Cash generation has also recovered. Free cash flow moved from negative territory in 2023 to clearly positive levels afterward, and trailing free cash flow is now in the low hundreds of millions of dollars. For a defense contractor, that is important because accounting earnings can sometimes look better than cash flow during production ramps. Leonardo DRS currently appears to be converting growth into cash more consistently than it did a few years ago.
A meaningful catalyst is the company’s exposure to U.S. naval and electric power programs. Military platforms are becoming more power-hungry as sensors, software, and directed-energy capabilities expand. That creates demand for exactly the kind of shipboard power conversion and propulsion systems where Leonardo DRS has an established position. Continued contract wins, backlog conversion, and production scaling in these categories could support future growth beyond ordinary budget increases.
Recent company communications have also pointed to ongoing order activity and backlog support across its defense electronics portfolio. In this industry, backlog matters because it gives more visibility than many industrial businesses have. It does not remove execution risk, but it can make future revenue more predictable when the underlying programs remain funded.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


