Stock Analysis · dormakaba Holding AG (DRRKF)
Overview
dormakaba Holding AG is a global access solutions company. In simple terms, it makes and services products that control how people enter, exit, and secure buildings. Its portfolio includes door hardware, automatic doors, electronic access control systems, mechanical and digital locks, key systems, safes, movable walls, and related software and services. The company sells to commercial buildings, hotels, hospitals, schools, airports, retailers, and public infrastructure, and it also has exposure to residential security products in some markets.
The business is generally organized around access products, project-based installations, and recurring service activity. Based on company reporting and business descriptions, the largest revenue sources can be summarized as follows:
- Access Solutions products and systems: approximately 70% to 80% of revenue. This includes door closers, locks, cylinders, entrance systems, electronic access devices, and integrated security hardware used in new construction and upgrades.
- Services, maintenance, and modernization: approximately 15% to 25% of revenue. This covers maintenance contracts, repairs, aftermarket support, and upgrades of installed systems.
- Other specialized solutions: a smaller share, roughly 5% to 10%. This includes products such as movable walls, safes, and niche access-related offerings depending on region.
Geographically, dormakaba is broad rather than dependent on one country. Europe is its biggest base, while the Americas and Asia-Pacific also contribute meaningful sales. That helps diversify demand, although construction cycles and renovation spending still matter a great deal.
What stands out about the model is that it combines hardware sales with software-enabled access control and a service base tied to installed products. That mix can make revenue more resilient than a pure construction supplier, because buildings need ongoing maintenance, replacement parts, and regulatory upgrades over time.
The operating profile has improved meaningfully since the weaker 2023-2024 period. Revenue has stayed close to the same general range over the last several years, but operating income and net income recovered sharply in 2025 and remained much better in 2026 than the trough years. Another encouraging sign is cost discipline: selling and administrative expenses have come down from their recent peak, while interest expense has also eased. This suggests the recent profit improvement has come more from execution and efficiency than from rapid top-line growth.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Industrials | |
| Industry | Building Products & Equipment | |
| Market Cap ⓘ | $3.30B | |
| Beta ⓘ | 0.73 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 31.59 | 22.10 |
| P/B Ratio ⓘ | 21.10 | 1.97 |
| FCF Yield ⓘ | N/A | 6.38% |
| Dividend Yield ⓘ | 1.20% | 1.94% |
| EBIT / EV ⓘ | 7.24% | 4.79% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | -1.30% | 9.30% |
| RPS Growth (5Y CAGR) ⓘ | -43.52% | 7.81% |
| EPS Growth (5Y CAGR) ⓘ | -10.29% | -13.06% |
| BVPS Growth (5Y CAGR) ⓘ | -45.17% | 6.14% |
| Margin Growth (5Y Trend) ⓘ | 0.66% | 0.88% |
| FCF Growth (5Y CAGR) ⓘ | 34.69% | 11.01% |
| DPS Growth (5Y CAGR) ⓘ | -47.86% | 9.48% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 10.84% |
| ROA (Latest) ⓘ | N/A | 5.41% |
| ROIC (5Y Median) ⓘ | 18.29% | 9.38% |
| ROA (5Y Median) ⓘ | 3.35% | 4.95% |
| Net Debt / EBIT (Latest) ⓘ | N/A | 2.08 |
| Net Debt / EBIT (5Y Median) ⓘ | 1.95 | 2.27 |
| Net Debt / EBITDA (Latest) ⓘ | N/A | 1.39 |
| Net Debt / Assets ⓘ | 17.71% | 19.28% |
| EBITDA / Interest ⓘ | N/A | 9.58 |
| Operating Margin (Latest) ⓘ | N/A | 10.50% |
| Operating Margin (5Y Median) ⓘ | 9.43% | 10.29% |
| Debt to Equity (Latest) ⓘ | N/A | 65.48% |
| Profit Margin (Latest) ⓘ | 3.47% | 6.67% |
| Free Cash Flow (Latest) ⓘ | N/A | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +142.83% | +61.68% |
| 12M Return (excl. last month) ⓘ | -13.47% | +12.58% |
| 6M Return ⓘ | +12.45% | 0.00% |
| Price vs. 200-Day MA ⓘ | N/A | +0.02% |
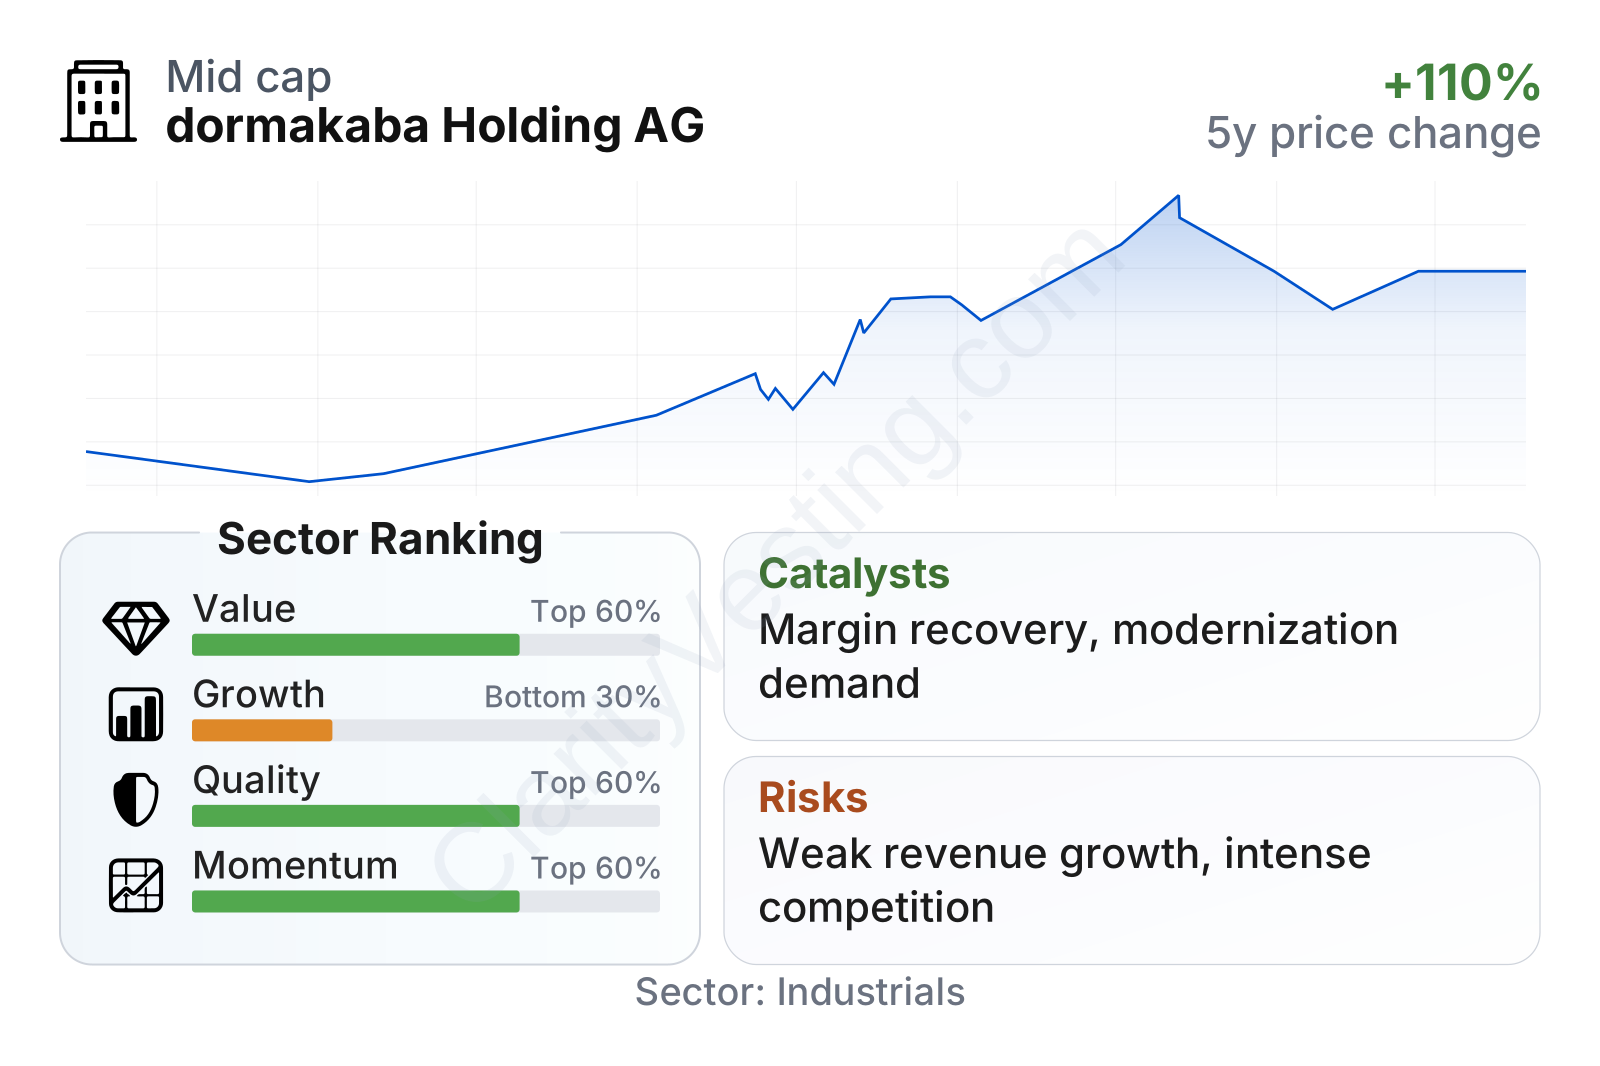
dormakaba sits in the mid-sized range and its share price has risen strongly over the last three years, clearly ahead of the sector median over that longer stretch. More recently, momentum has been mixed, with softer performance over the last year even though the shares still trade above their long-term average trend line.
The quality profile looks acceptable rather than outstanding. Long-term returns on invested capital have been solid relative to much of the sector, and leverage appears manageable, with net debt metrics around or slightly better than industry norms. On the other hand, profit margin remains below the sector median, which shows the business still has room to improve profitability.
The weakest area is growth. Recent revenue change has been slightly negative, and several five-year per-share growth measures look poor. One bright spot is cash generation: free cash flow growth over five years has been much stronger than the sector median, which fits with the recent recovery in operating performance.
Valuation indicators are mixed. The earnings multiple is above the sector median, the price-to-book multiple is exceptionally high, and the dividend yield is below the sector median. At the same time, the company’s EBIT relative to enterprise value looks better than many peers, which suggests the market is recognizing the earnings recovery but is not treating the business as distressed or deeply discounted.
Growth
dormakaba operates in a sector with durable long-term support. Building security, access control, and door automation benefit from urbanization, stricter building standards, workplace security needs, and the gradual shift from mechanical hardware to electronic and software-connected systems. In developed markets, a large installed base also creates steady replacement and modernization demand even when new construction slows.
The company’s strategy makes sense in that context. It is positioned where several trends meet: physical security, automation, energy-efficient entrance systems, and digital credential management. The move toward smart buildings should support higher-value electronic access solutions over time, while service and maintenance can add recurring revenue around installed systems.
A key growth catalyst is margin improvement rather than pure sales expansion. Recent results show that better cost control and simplification efforts can lift earnings even if revenue stays nearly flat. If dormakaba continues to streamline operations, improve pricing, and focus on higher-value electronic and service offerings, profit growth can outpace revenue growth.
Another useful catalyst is modernization demand. Many commercial and institutional buildings still operate older access infrastructure. Upgrades tied to compliance, convenience, and energy efficiency can support replacement cycles for automatic doors, electronic locks, and integrated entry systems. This is especially relevant in healthcare, education, transportation, hospitality, and public buildings, where reliability and controlled access matter continuously.
Recent company communication has also pointed to transformation efforts and portfolio simplification, which matter because the business has not been a strong organic grower in recent years. In other words, the near-term opportunity is less about explosive demand and more about improving the quality of revenue and converting a stable installed base into better margins and cash flow.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


