Stock Analysis · Dundee Precious Metals Inc (DPMLF)
Overview
Dundee Precious Metals is a gold mining company with operations centered in Southeastern Europe and a development pipeline that also includes Ecuador. In simple terms, it finds, mines, and sells gold, with copper and silver adding smaller contributions. The company’s current producing base is mainly the Chelopech mine in Bulgaria and the Ada Tepe mine in Bulgaria, while its longer-term growth plan is increasingly tied to the Čoka Rakita project in Serbia and the Loma Larga project in Ecuador.
Its revenue mainly comes from metal sales rather than from many different business lines, so the company is fairly easy to understand. Based on recent annual reporting and operational disclosures, the revenue mix is approximately:
- Gold: about 80% to 90% of revenue. This is the main driver and includes doré and concentrate-related gold sales from producing mines.
- Copper: about 10% to 20% of revenue. This is largely tied to Chelopech, which is a copper-gold deposit.
- Silver and other metals: generally under 5% of revenue. These are by-products sold alongside the main metals.
Geographically, cash generation is still concentrated in a small number of mines. That creates focus and operational simplicity, but it also means company results can move sharply when production, grades, or metal prices change at one site.
The recent financial flow also shows a business that has become significantly more profitable over the last two years. Revenue expanded strongly into 2025, while costs grew more slowly, allowing a much larger share of sales to turn into operating income and net income.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 04, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Gold | |
| Market Cap ⓘ | $8.50B | |
| Beta ⓘ | 1.33 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 12.54 | 17.61 |
| P/B Ratio ⓘ | 2.98 | 1.78 |
| FCF Yield ⓘ | 7.94% | 5.86% |
| Dividend Yield ⓘ | 0.40% | 2.07% |
| EBIT / EV ⓘ | 7.36% | 6.43% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 93.90% | 11.30% |
| RPS Growth (5Y CAGR) ⓘ | 10.59% | 4.46% |
| EPS Growth (5Y CAGR) ⓘ | 32.44% | -13.11% |
| BVPS Growth (5Y CAGR) ⓘ | 26.80% | 5.51% |
| Margin Growth (5Y Trend) ⓘ | 8.86% | -1.57% |
| FCF Growth (5Y CAGR) ⓘ | 35.31% | 0.55% |
| DPS Growth (5Y CAGR) ⓘ | 7.61% | 6.02% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 23.59% | 9.31% |
| ROA (Latest) ⓘ | 20.59% | 4.94% |
| ROIC (5Y Median) ⓘ | 19.27% | 7.91% |
| ROA (5Y Median) ⓘ | 16.40% | 3.93% |
| Net Debt / EBIT (Latest) ⓘ | -1.07 | 1.40 |
| Net Debt / EBIT (5Y Median) ⓘ | -2.35 | 1.70 |
| Net Debt / EBITDA (Latest) ⓘ | -0.93 | 0.91 |
| Net Debt / Assets ⓘ | -23.02% | 13.69% |
| EBITDA / Interest ⓘ | 169.43 | 11.93 |
| Operating Margin (Latest) ⓘ | 56.82% | 13.07% |
| Operating Margin (5Y Median) ⓘ | 40.38% | 11.86% |
| Debt to Equity (Latest) ⓘ | N/A | 40.43% |
| Profit Margin (Latest) ⓘ | 50.26% | 6.57% |
| Free Cash Flow (Latest) ⓘ | $674.93M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +571.07% | +65.06% |
| 12M Return (excl. last month) ⓘ | +125.24% | +35.57% |
| 6M Return ⓘ | +4.95% | +1.69% |
| Price vs. 200-Day MA ⓘ | +4.85% | +0.95% |
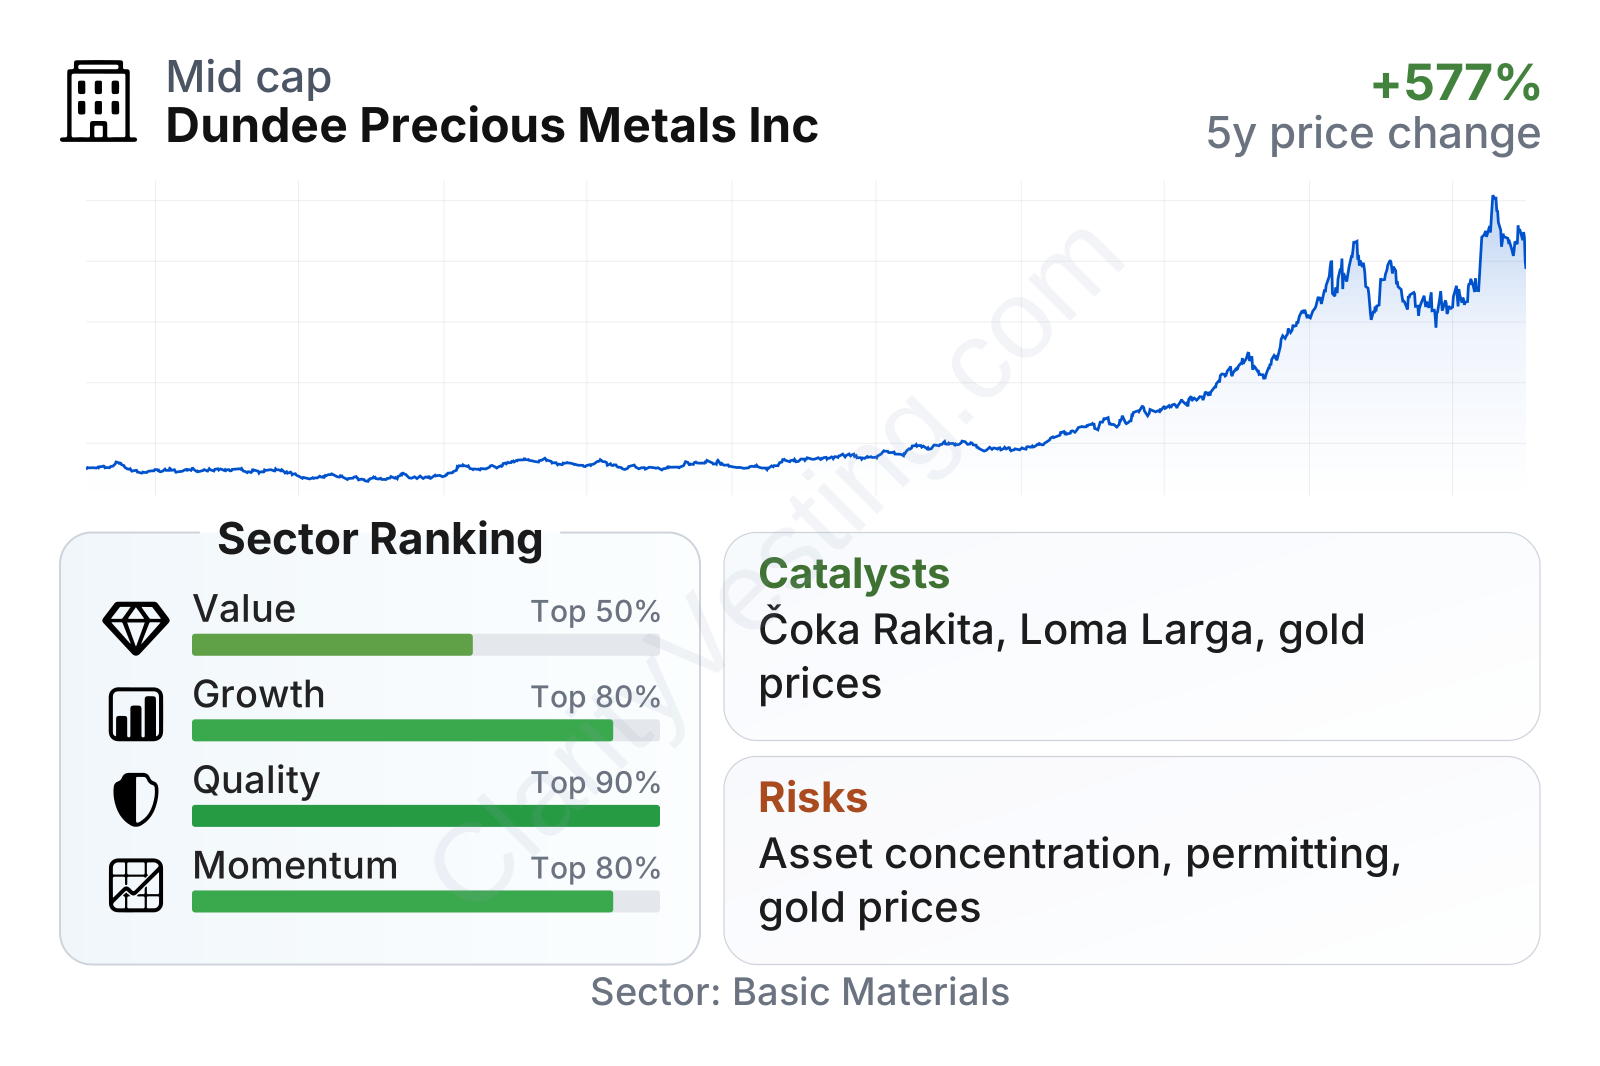
Dundee Precious Metals stands out on quality, growth, and recent market performance relative to much of the gold sector. Profitability is unusually strong, returns on capital are high, and the balance sheet is exceptionally clean with net cash rather than heavy leverage. On valuation, the picture is more mixed: earnings and enterprise-value-based measures still look broadly reasonable for the current profit level, but the price-to-book ratio is well above the sector median, reflecting that the market already gives the company credit for its operating quality and project pipeline.
The stock’s long climb since 2023 suggests that the market has been recognizing both stronger gold fundamentals and company-specific execution. At the same time, the recent pullback from the 2026 high shows that even strong miners remain sensitive to shifts in gold sentiment and expectations.
Growth
Gold mining remains a sector with long-term relevance because gold often benefits from inflation concerns, geopolitical uncertainty, central bank demand, and the search for assets outside traditional currencies. That does not make the industry steadily growing in the way software or healthcare can be, but it does mean well-run gold producers can find attractive expansion opportunities when they combine good assets, cost discipline, and a strong balance sheet.
Dundee Precious Metals appears to fit that profile. Its strategy is straightforward: generate cash from current mines, keep debt low, and reinvest into future projects that can replace depleting production. That matters because mining companies are always fighting natural decline at existing assets. In this case, Ada Tepe is a shorter-life mine, so bringing new production online is especially important for sustaining the company beyond the current asset base.
Revenue growth has been volatile, which is normal in mining, but the latest period shows a sharp acceleration. That surge is far above the sector’s median pace and reflects a mix of stronger realized metal prices and favorable operating performance. Over a five-year period, revenue per share and earnings per share have also grown much faster than the typical company in the gold space.
Cash generation has also improved meaningfully. Free cash flow has climbed from the low hundreds of millions of dollars a few years ago to well above $500 million on a trailing basis. That gives the company unusual flexibility for a miner of its size: it can fund development, continue dividends, consider acquisitions, or simply preserve financial strength.
The main growth catalysts now are project execution and mine-life replacement. Čoka Rakita in Serbia is one of the most important pieces because it has the potential to become a new producing mine in a region where the company already has operating experience. Loma Larga in Ecuador is another potentially important growth asset, though it carries a different risk profile because of permitting and social-license considerations. More broadly, a supportive gold price environment can rapidly lift earnings and internal funding capacity for both projects.
Recent company communications have also emphasized exploration success around its development portfolio and continued progress on technical and permitting work. For a miner, that matters because value creation often comes from extending resources, improving project economics, and moving deposits from paper plans into financed construction decisions.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


