Stock Analysis · Ducommun Incorporated (DCO)
Overview
Ducommun Incorporated is a long-established aerospace and defense supplier that designs and manufactures components and systems used on military aircraft, commercial airplanes, space platforms, and industrial applications. The company does not build whole aircraft. Instead, it supplies the parts and subsystems that larger manufacturers and defense contractors need, which makes it a behind-the-scenes participant in many major programs.
Its business is organized into two main segments. Based on the latest annual reporting structure, revenue is generated primarily from:
- Electronic Systems: about 58% of revenue — This segment includes engineered electronic and electromechanical products such as avionics-related hardware, cabin and aerospace electronics, power and actuation systems, missile and defense electronics, and other complex assemblies.
- Structural Systems: about 42% of revenue — This segment makes metallic and composite structures, engineered assemblies, machined parts, skins, panels, and other airframe-related components used on aircraft and defense platforms.
Looking at end markets, Ducommun is heavily tied to aerospace and defense demand, with military and space programs representing a large share and commercial aerospace also making an important contribution. That mix gives the company exposure to both defense budgets and the ongoing recovery and production ramp in commercial aircraft.
The business model is relatively straightforward: win positions on long production programs, deliver highly specified components, and benefit as customers raise output over time. That can create durable revenue streams, but it also means performance depends on execution, production schedules, and a relatively concentrated set of large customers.
The long-term income flow shows a useful contrast. Revenue has climbed steadily from roughly the mid-$600 million range to above $800 million over the last five years, and gross profit has also improved. However, profitability at the operating and net income level has been far less stable, which suggests that cost execution and one-time charges have mattered as much as top-line growth.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Industrials | |
| Industry | Aerospace & Defense | |
| Market Cap ⓘ | $2.51B | |
| Beta ⓘ | 1.04 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | N/A | 22.29 |
| P/B Ratio ⓘ | 3.80 | 1.98 |
| FCF Yield ⓘ | -0.97% | 6.26% |
| Dividend Yield ⓘ | N/A | 1.92% |
| EBIT / EV ⓘ | -0.96% | 4.83% |
| PEG ⓘ | 3.34 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 11.80% | 9.30% |
| RPS Growth (5Y CAGR) ⓘ | 1.18% | 7.76% |
| EPS Growth (5Y CAGR) ⓘ | -12.91% | -13.17% |
| BVPS Growth (5Y CAGR) ⓘ | 3.42% | 6.13% |
| Margin Growth (5Y Trend) ⓘ | -32.34% | 0.74% |
| FCF Growth (5Y CAGR) ⓘ | 29.25% | 10.79% |
| DPS Growth (5Y CAGR) ⓘ | 174.64% | 9.41% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | -2.20% | 10.75% |
| ROA (Latest) ⓘ | -2.01% | 5.41% |
| ROIC (5Y Median) ⓘ | 4.88% | 9.37% |
| ROA (5Y Median) ⓘ | 2.80% | 4.95% |
| Net Debt / EBIT (Latest) ⓘ | N/A | 2.04 |
| Net Debt / EBIT (5Y Median) ⓘ | 4.89 | 2.27 |
| Net Debt / EBITDA (Latest) ⓘ | 50.40 | 1.39 |
| Net Debt / Assets ⓘ | 24.18% | 19.27% |
| EBITDA / Interest ⓘ | 0.42 | 9.58 |
| Operating Margin (Latest) ⓘ | -3.21% | 10.49% |
| Operating Margin (5Y Median) ⓘ | 6.30% | 10.30% |
| Debt to Equity (Latest) ⓘ | 48.65% | 64.82% |
| Profit Margin (Latest) ⓘ | -2.45% | 6.67% |
| Free Cash Flow (Latest) ⓘ | -$24.47M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +265.78% | +67.77% |
| 12M Return (excl. last month) ⓘ | +78.88% | +12.05% |
| 6M Return ⓘ | +19.16% | 0.00% |
| Price vs. 200-Day MA ⓘ | +11.29% | +0.67% |
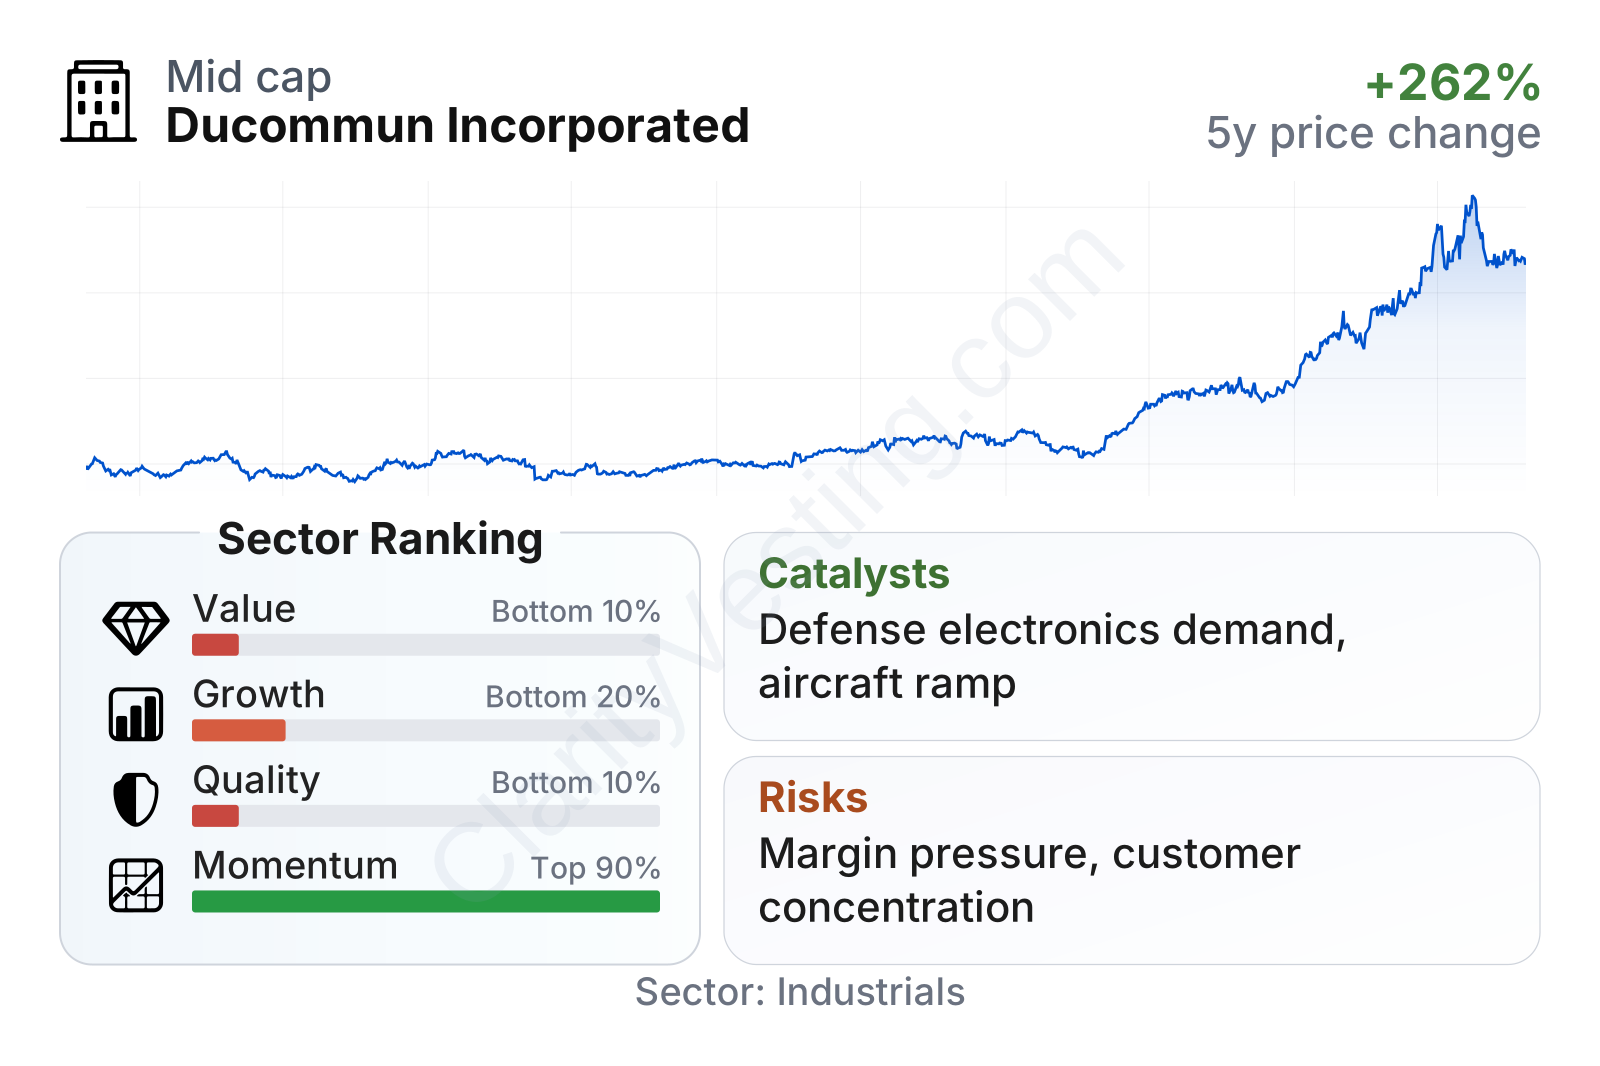
Ducommun is a mid-sized aerospace and defense company with stock-market performance that has been exceptionally strong over the last one to three years. At the same time, the broader metric profile is mixed. Momentum is among the strongest in its sector, but value, quality, and growth rankings are weaker. That combination usually means the market has become more optimistic about future improvement than current profitability alone would justify.
Growth
Aerospace and defense remains a favorable long-term market. On the defense side, spending priorities continue to support missiles, electronics, sustainment, and next-generation platforms. On the commercial aerospace side, aircraft production is still being pushed higher to work through large backlogs. Both trends are relevant to Ducommun because it supplies content rather than end products, allowing it to benefit from volume growth across multiple programs.
Ducommun’s strategy also fits that backdrop reasonably well. The company focuses on specialized, mission-critical products that are hard to replace quickly once qualified. Management has emphasized higher-value engineered offerings, operational improvement, and a portfolio mix tilted toward defense and electronics, where program lives can be long and switching costs can be meaningful.
Recent revenue growth has been positive and, lately, stronger than the sector median. The pattern is not explosive, but it does show acceleration after a softer stretch in 2024 and early 2025. For a supplier in this industry, consistent mid- to high-single-digit growth, with occasional periods above 10%, can be meaningful if it converts into margin improvement.
Cash generation is less clean than revenue growth. Free cash flow had improved into positive territory before turning negative again more recently. That does not automatically signal a broken business, since working capital swings are common when production ramps and inventory builds, but it does reduce near-term flexibility and raises the importance of better execution.
As a practical catalyst, Ducommun appears well placed to benefit from continued build-rate increases at major aerospace customers and from sustained demand for defense electronics and missile-related content. Recent company communications have also highlighted new business wins and program activity, which matters because this is a business where booked work can support revenue for years once production matures.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


