Stock Analysis · Covista Inc (CVSA)
Overview
Covista Inc operates in education and training services, with a business model centered on postsecondary learning. Based on its public filings, the company primarily serves students through university and professional education programs, with a strong emphasis on online and career-focused offerings. That makes it less tied to one-time consumer purchases and more dependent on enrollment trends, student retention, tuition pricing, and program mix.
The company’s revenue is mainly generated from educational services rather than a wide mix of unrelated activities. Public disclosures indicate that tuition and fees are the core source of sales, while smaller contributions can come from books, supplies, and other student-related services. Exact percentages are not always broken out in a highly granular way in summary materials, but the business appears heavily concentrated in core academic revenue.
- Tuition and fees: the dominant source of revenue, likely well above 80%, tied to degree programs, certificates, and other academic offerings.
- Books, materials, and student-related charges: a smaller contribution, linked to course content, supplies, and ancillary academic services.
- Other revenue: limited contribution from miscellaneous educational and institutional activities.
Financially, the operating picture has improved meaningfully over the last several years. Revenue has climbed from roughly $1.4 billion in fiscal 2022 to nearly $2.0 billion in fiscal 2026, while operating income and net income have expanded even faster. Just as important, interest expense has moved lower over that period, suggesting a healthier balance sheet and less pressure from debt costs.
The business mix shows a favorable trend: sales have grown steadily, gross profit has widened, and profitability has improved from losses in fiscal 2022 to solid earnings in fiscal 2026. One item worth watching is operating expense growth in the latest year, especially selling and administrative spending, because future margin gains will depend on revenue continuing to outpace those costs.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Consumer Defensive | |
| Industry | Education & Training Services | |
| Market Cap ⓘ | $4.44B | |
| Beta ⓘ | 0.65 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 17.50 | 17.88 |
| P/B Ratio ⓘ | 3.10 | 1.29 |
| FCF Yield ⓘ | 8.85% | 12.39% |
| Dividend Yield ⓘ | N/A | 2.85% |
| EBIT / EV ⓘ | 8.30% | 6.43% |
| PEG ⓘ | 0.91 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 9.70% | 4.10% |
| RPS Growth (5Y CAGR) ⓘ | 17.65% | 6.18% |
| EPS Growth (5Y CAGR) ⓘ | 23.47% | -13.59% |
| BVPS Growth (5Y CAGR) ⓘ | 7.06% | 3.20% |
| Margin Growth (5Y Trend) ⓘ | 14.31% | -0.15% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 4.10% |
| DPS Growth (5Y CAGR) ⓘ | -29.90% | 6.79% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 15.32% | 12.34% |
| ROA (Latest) ⓘ | 8.56% | 6.30% |
| ROIC (5Y Median) ⓘ | 10.94% | 10.49% |
| ROA (5Y Median) ⓘ | 4.93% | 5.44% |
| Net Debt / EBIT (Latest) ⓘ | 1.28 | 1.96 |
| Net Debt / EBIT (5Y Median) ⓘ | 2.31 | 2.35 |
| Net Debt / EBITDA (Latest) ⓘ | 1.06 | 1.38 |
| Net Debt / Assets ⓘ | 16.57% | 21.51% |
| EBITDA / Interest ⓘ | 10.74 | 9.46 |
| Operating Margin (Latest) ⓘ | 19.92% | 8.87% |
| Operating Margin (5Y Median) ⓘ | 17.14% | 9.53% |
| Debt to Equity (Latest) ⓘ | 62.61% | 72.35% |
| Profit Margin (Latest) ⓘ | 12.87% | 5.40% |
| Free Cash Flow (Latest) ⓘ | $392.73M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +190.79% | +20.92% |
| 12M Return (excl. last month) ⓘ | -8.90% | +2.13% |
| 6M Return ⓘ | +14.15% | +1.26% |
| Price vs. 200-Day MA ⓘ | +9.04% | +1.39% |
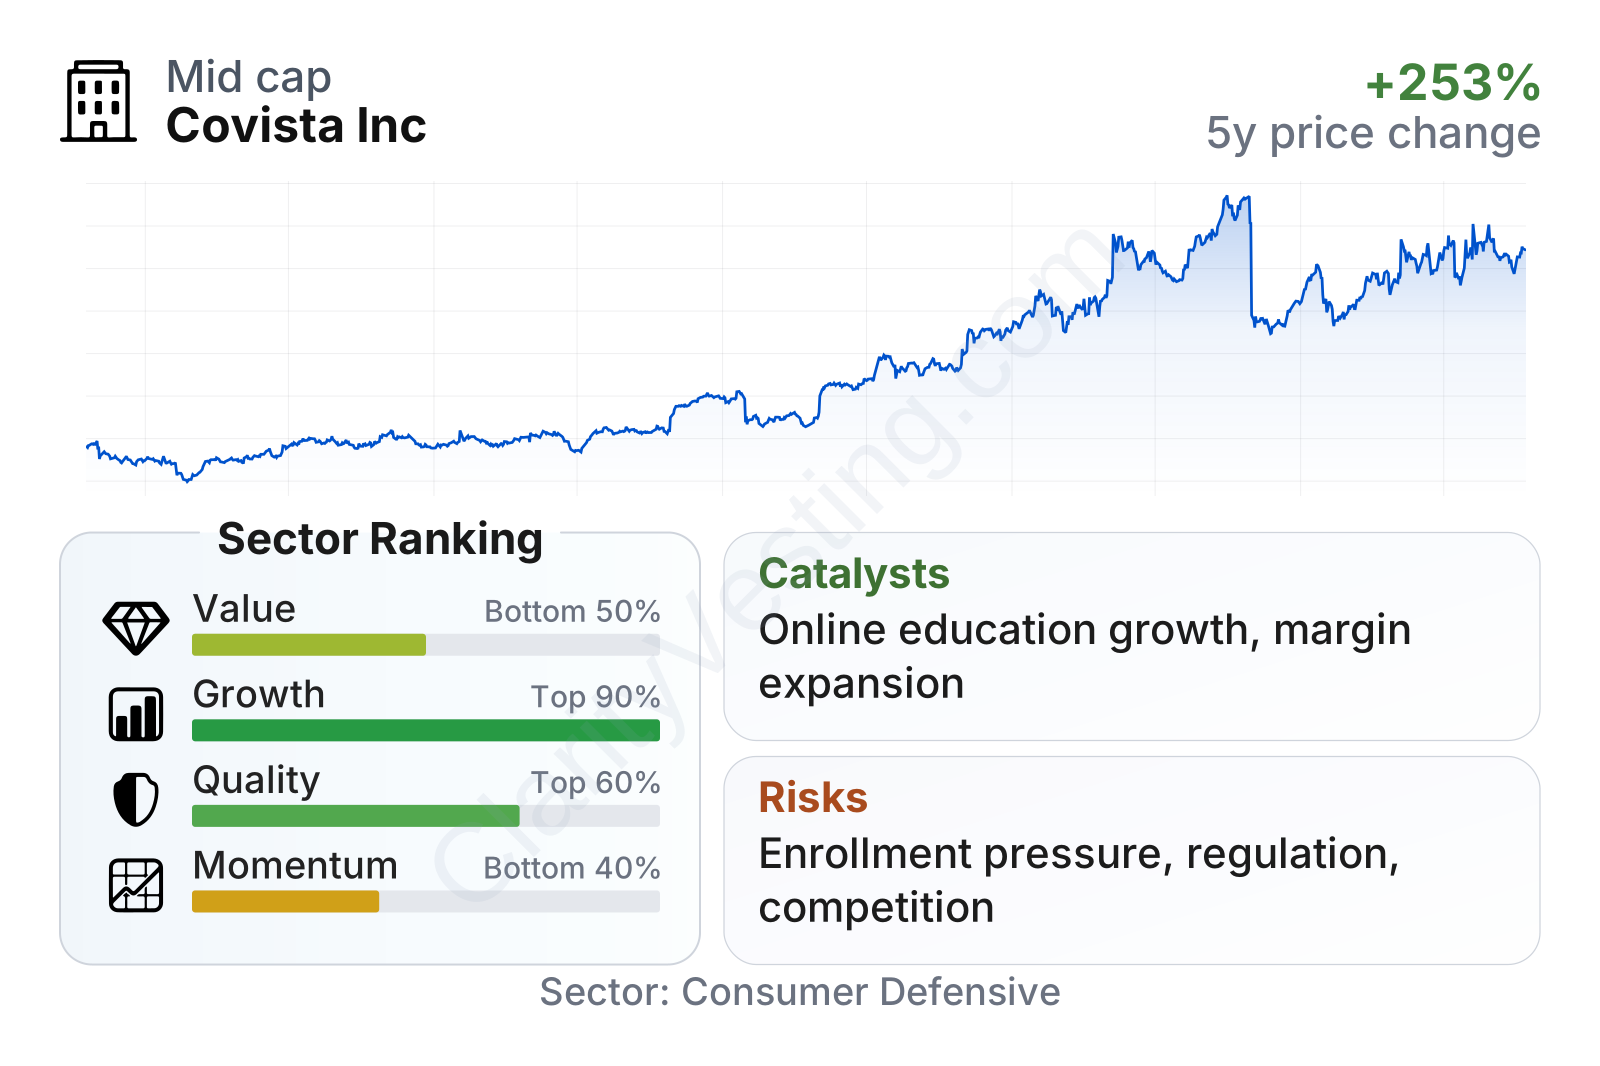
Covista sits in the mid-cap range and its share-price volatility has been lower than the broader market, as indicated by a beta well below 1. On fundamentals, the profile is mixed in a constructive way: valuation metrics are not especially cheap on every measure, but growth ranks near the top of its sector, quality is above average, and momentum has remained positive. Profitability and returns on capital also compare well with many sector peers.
Growth
Education remains a relevant long-term sector, but it is not automatically a high-growth market. For Covista, the more important question is whether it is gaining share in parts of education where demand is durable. Career-oriented programs, adult learning, flexible online formats, and training tied to employability can support growth when the offering matches labor-market needs. That strategic direction is easier to scale than a purely campus-based model and can create recurring enrollment pipelines.
Recent performance suggests the strategy has been working. Revenue growth has stayed positive and, despite some quarterly moderation, the latest year-over-year increase remains clearly above the sector median. Over five years, revenue per share and earnings per share have grown much faster than the typical company in its sector, which points to more than just temporary recovery.
The growth pattern looks strongest from 2023 through 2025, followed by a slower but still positive pace in 2026. That matters because it suggests the company is no longer in a turnaround phase only; it is now trying to sustain expansion from a higher base. Margin improvement over the same period makes that growth more credible, since it has not depended only on rising enrollment but also on better operating efficiency.
Cash generation is another encouraging sign. Free cash flow has risen sharply over the last several years and now stands at a meaningful level for a company of this size. Stronger cash production gives management more flexibility for debt reduction, acquisitions, technology investment, and shareholder returns.
The upward trend in cash flow supports the idea that earnings quality has improved. In practical terms, the company is not only reporting better accounting profits; it is also converting more of its operations into real cash. That strengthens the long-term case if management can keep enrollment stable and avoid letting costs rise too quickly.
A visible catalyst is the company’s improving financial structure alongside operating growth. Lower interest expense, better margins, and stronger cash generation can reinforce each other. If Covista continues to expand in workforce-focused and online education while maintaining pricing discipline, that could remain a meaningful opportunity.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


