Stock Analysis · Critical Metals Corp (CRML)
Overview
Critical Metals Corp is a small mining company focused on metals that are important for electrification, battery supply chains, and advanced manufacturing. Its main assets are development-stage projects rather than large operating mines, which means the business today is still shaped more by project building, permitting, and financing than by steady commercial production.
The company’s portfolio is centered on lithium and other strategic minerals. Public company materials highlight the Wolfsberg Lithium Project in Austria as the core asset, with additional exposure to critical minerals projects in Greenland. In practical terms, the investment case depends on whether these assets can move from exploration and development into funded, buildable, and eventually producing operations.
At this stage, revenue is very limited and does not reflect the long-term ambition of the business. Recent annual financial statements show that reported revenue has been negligible relative to operating costs, which means the company is not yet supported by a meaningful producing asset base. Based on recent filings, revenue sources are best understood as follows:
- Project-related and other minor revenue: approximately 100% of current reported revenue. This appears to be incidental rather than the result of full-scale mining operations.
- Lithium concentrate or downstream mineral sales: 0% at commercial scale so far, because the flagship assets are still in development rather than full production.
This matters because Critical Metals should be viewed less as an established miner and more as a listed vehicle tied to the future value of a handful of strategic mineral projects. That can create upside if milestones are met, but it also means current financial statements offer only limited support on their own.
The business mix also shows a clear imbalance: expenses have been far higher than revenue for several years. That is typical of a pre-production resource company, but it underlines that the present valuation rests mainly on future execution rather than current operating profitability.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Other Industrial Metals & Mining | |
| Market Cap ⓘ | $1.08B | |
| Beta ⓘ | 1.95 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | N/A | 16.90 |
| P/B Ratio ⓘ | 2.71 | 1.65 |
| FCF Yield ⓘ | -3.94% | 5.76% |
| Dividend Yield ⓘ | N/A | 2.13% |
| EBIT / EV ⓘ | -7.61% | 6.30% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 557.70% | 11.10% |
| RPS Growth (5Y CAGR) ⓘ | N/A | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -13.47% |
| BVPS Growth (5Y CAGR) ⓘ | 19.15% | 5.51% |
| Margin Growth (5Y Trend) ⓘ | N/A | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 0.37% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 6.08% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 9.26% |
| ROA (Latest) ⓘ | -59.18% | 4.91% |
| ROIC (5Y Median) ⓘ | -91.58% | 7.70% |
| ROA (5Y Median) ⓘ | -44.90% | 3.86% |
| Net Debt / EBIT (Latest) ⓘ | N/A | 1.40 |
| Net Debt / EBIT (5Y Median) ⓘ | N/A | 1.70 |
| Net Debt / EBITDA (Latest) ⓘ | N/A | 0.95 |
| Net Debt / Assets ⓘ | -19.05% | 13.69% |
| EBITDA / Interest ⓘ | N/A | 12.34 |
| Operating Margin (Latest) ⓘ | -4241.76% | 13.20% |
| Operating Margin (5Y Median) ⓘ | -6152.28% | 11.80% |
| Debt to Equity (Latest) ⓘ | 1.89% | 40.56% |
| Profit Margin (Latest) ⓘ | N/A | 6.43% |
| Free Cash Flow (Latest) ⓘ | -$42.62M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | -34.99% | +68.89% |
| 12M Return (excl. last month) ⓘ | +25.30% | +30.21% |
| 6M Return ⓘ | -9.25% | -4.16% |
| Price vs. 200-Day MA ⓘ | -26.35% | -1.27% |
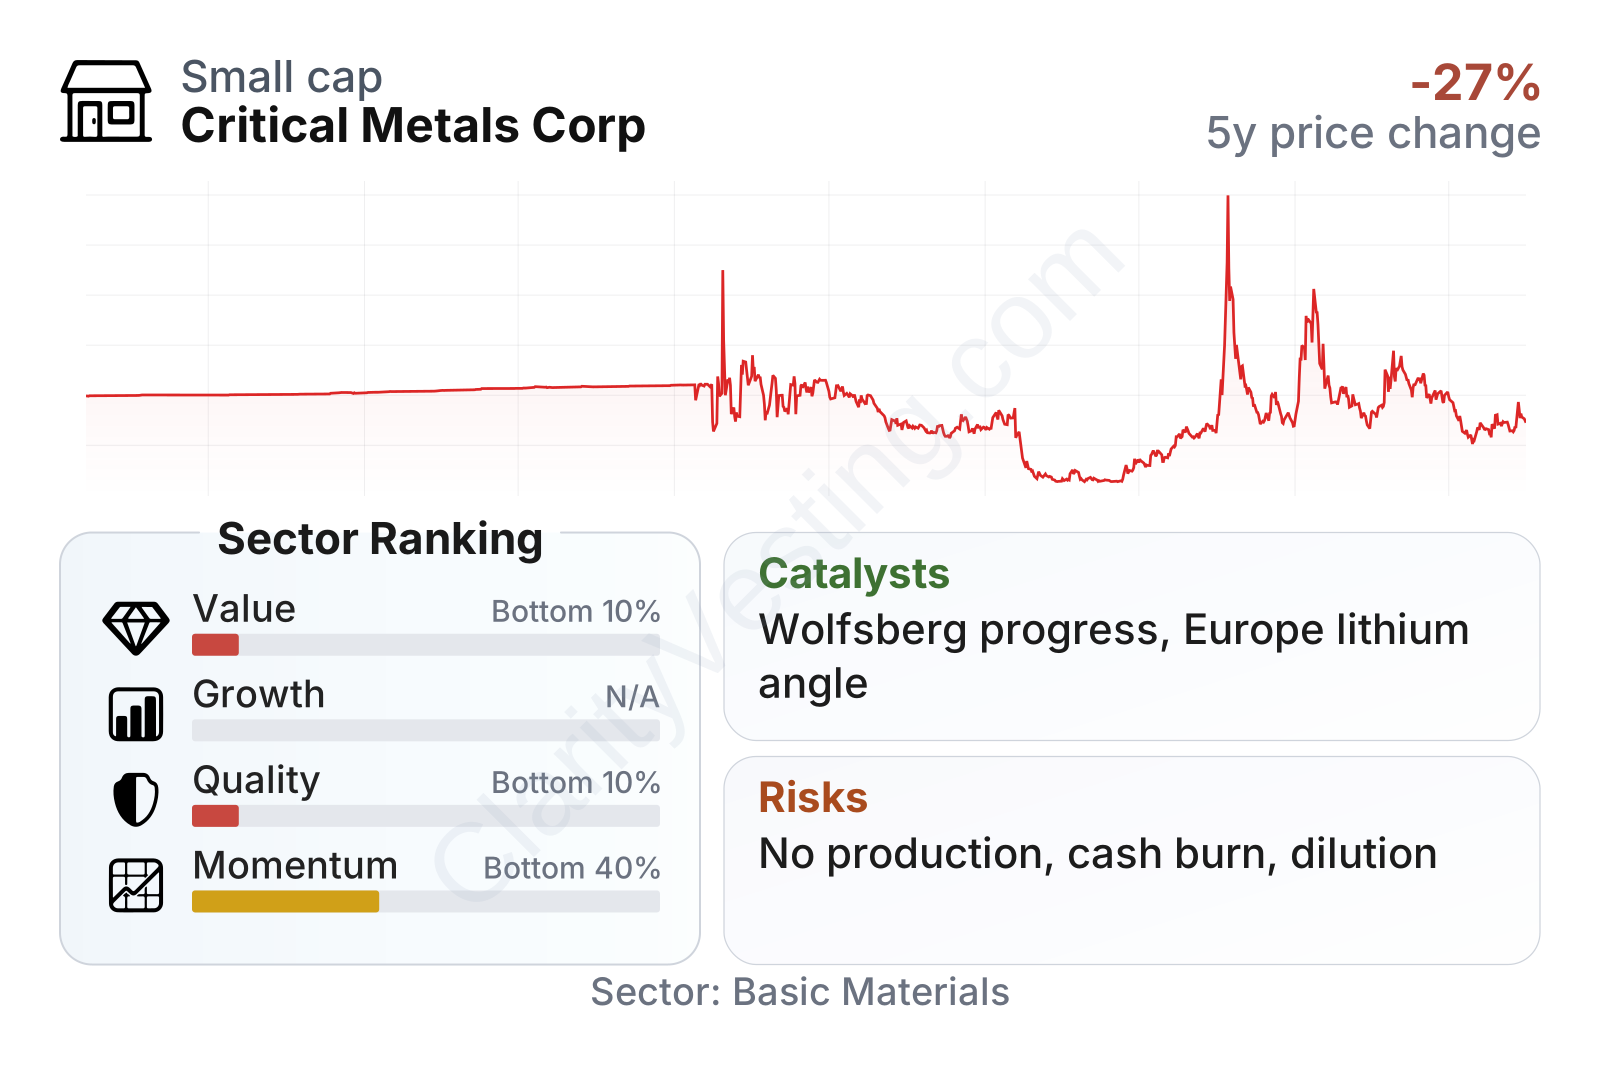
Critical Metals is currently a small-cap company with a stock that has been volatile, including large swings over the last two years. The share price recovery seen at points in 2026 did not fully erase earlier declines, and momentum remains weaker than the sector overall.
The metrics table points to a business that scores poorly on current value and quality measures. Profitability is deeply negative, free cash flow remains negative, and operating margins are far below the industry median. On the positive side, leverage is very low, with debt to equity near 2% versus roughly 40% for the sector median, which gives the company more balance-sheet flexibility than many peers. Book value growth has also been stronger than the sector median, but that mostly reflects capital formation and asset development rather than a mature earnings engine.
Growth
The company operates in a sector with a credible long-term demand backdrop. Lithium remains a key input for electric vehicle batteries and energy storage systems, while Western governments and manufacturers continue trying to build critical mineral supply chains outside China. That broader trend supports interest in projects located in Europe and other politically strategic jurisdictions.
Critical Metals’ strategy is logical in that context. The Wolfsberg Lithium Project in Austria is especially notable because Europe has relatively few advanced hard-rock lithium projects that could feed regional battery manufacturing. If the asset moves forward on permitting, technical studies, financing, and offtake agreements, it could become much more relevant than the company’s present income statement suggests.
There is also a strategic angle beyond pure geology. A future European lithium source can be attractive to automakers, battery makers, and policymakers that want shorter supply chains and lower geopolitical dependence. For a company of this size, one credible partnership, funding package, or permitting milestone can materially change market perception.
Recent corporate developments have continued to emphasize project advancement, portfolio building, and strategic positioning around critical minerals. The main opportunity is not current production growth, but rather the possibility that one or more assets become financeable development projects. That is the central catalyst to monitor over the next several years.
Cash generation, however, still moves in the wrong direction. Free cash flow has remained negative and worsened as the company scaled up activity, which is consistent with a development-stage miner but also shows that growth currently consumes cash rather than producing it. For long-term analysis, the key question is whether these outflows are building toward a viable mine, not whether near-term cash flow looks attractive.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


