Stock Analysis · China Resources Land Ltd (CRBJY)
Overview
China Resources Land Ltd is a large mainland China property company focused on urban development. It develops and sells residential properties, but it is not only a homebuilder. The group also owns and operates shopping malls, office buildings, hotels, rental housing, and urban redevelopment projects. It is part of the broader China Resources Group, a major state-owned enterprise, which gives it scale, financing access, and a strong position in dealing with local governments and large city projects.
Its revenue is still dominated by property development and sales, while recurring income comes from investment properties and related operations. Based on the company’s recent annual reporting structure, the main sources of revenue can be summarized as follows:
- Property development and sales: approximately 85% to 90% of revenue. This includes contracted and recognized sales of residential projects and mixed-use developments.
- Investment property rental income: approximately 5% to 8% of revenue. This mainly comes from shopping malls, offices, and other commercial real estate held for leasing.
- Property management, construction, and other services: approximately 3% to 7% of revenue. This includes management services, urban operation activities, hotel operations, and other supporting businesses.
That mix matters because property development drives most of the top line, but rental income and operating assets help stabilize cash generation when China’s home sales market is weak. Over the last several years, total revenue has generally stayed at a very large scale, while gross profit and net income have been more pressured than revenue, showing that the company has kept volume but faced tougher profitability.
The business mix shows a company with substantial scale and still-strong operating earnings, but also with margin pressure. Revenue rose meaningfully from 2021 to 2024 and then was broadly stable in 2025, while net income trended lower from earlier peaks. That points to a resilient platform, but one operating in a much harder property market than a few years ago.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Nov 01, 2026 | |
| Context | ||
| Sector | Real Estate | |
| Industry | Real Estate - Development | |
| Market Cap ⓘ | $27.84B | |
| Beta ⓘ | 0.73 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 8.36 | 18.09 |
| P/B Ratio ⓘ | 0.17 | 0.87 |
| FCF Yield ⓘ | 319.06% | 7.16% |
| Dividend Yield ⓘ | 4.37% | 4.71% |
| EBIT / EV ⓘ | N/A | 3.79% |
| PEG ⓘ | 1.00 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | -28.50% | 5.60% |
| RPS Growth (5Y CAGR) ⓘ | 6.91% | 6.02% |
| EPS Growth (5Y CAGR) ⓘ | 32.43% | -7.57% |
| BVPS Growth (5Y CAGR) ⓘ | -8.35% | 0.46% |
| Margin Growth (5Y Trend) ⓘ | -9.23% | -0.87% |
| FCF Growth (5Y CAGR) ⓘ | 67.66% | 5.40% |
| DPS Growth (5Y CAGR) ⓘ | 1.33% | 5.11% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 12.94% | 5.20% |
| ROE (Latest) ⓘ | 31.33% | 7.59% |
| ROA (Latest) ⓘ | 4.43% | 3.05% |
| ROIC (5Y Median) ⓘ | 7.67% | 4.22% |
| ROE (5Y Median) ⓘ | 16.05% | 6.04% |
| ROA (5Y Median) ⓘ | 2.76% | 2.45% |
| Net Debt / EBIT (Latest) ⓘ | 1.50 | 7.38 |
| Net Debt / EBIT (5Y Median) ⓘ | 2.21 | 8.34 |
| Net Debt / EBITDA (Latest) ⓘ | 1.46 | 5.21 |
| Net Debt / Assets ⓘ | 16.50% | 37.29% |
| EBITDA / Interest ⓘ | 18.12 | 4.18 |
| Operating Margin (Latest) ⓘ | 21.89% | 34.98% |
| Operating Margin (5Y Median) ⓘ | 27.08% | 37.79% |
| Debt to Equity (Latest) ⓘ | 94.81% | 88.65% |
| Profit Margin (Latest) ⓘ | 9.19% | 20.06% |
| Free Cash Flow (Latest) ⓘ | $88.84B | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +22.46% | +38.49% |
| 12M Return (excl. last month) ⓘ | -4.00% | +2.38% |
| 6M Return ⓘ | +8.67% | -2.01% |
| Price vs. 200-Day MA ⓘ | +23.19% | -1.05% |
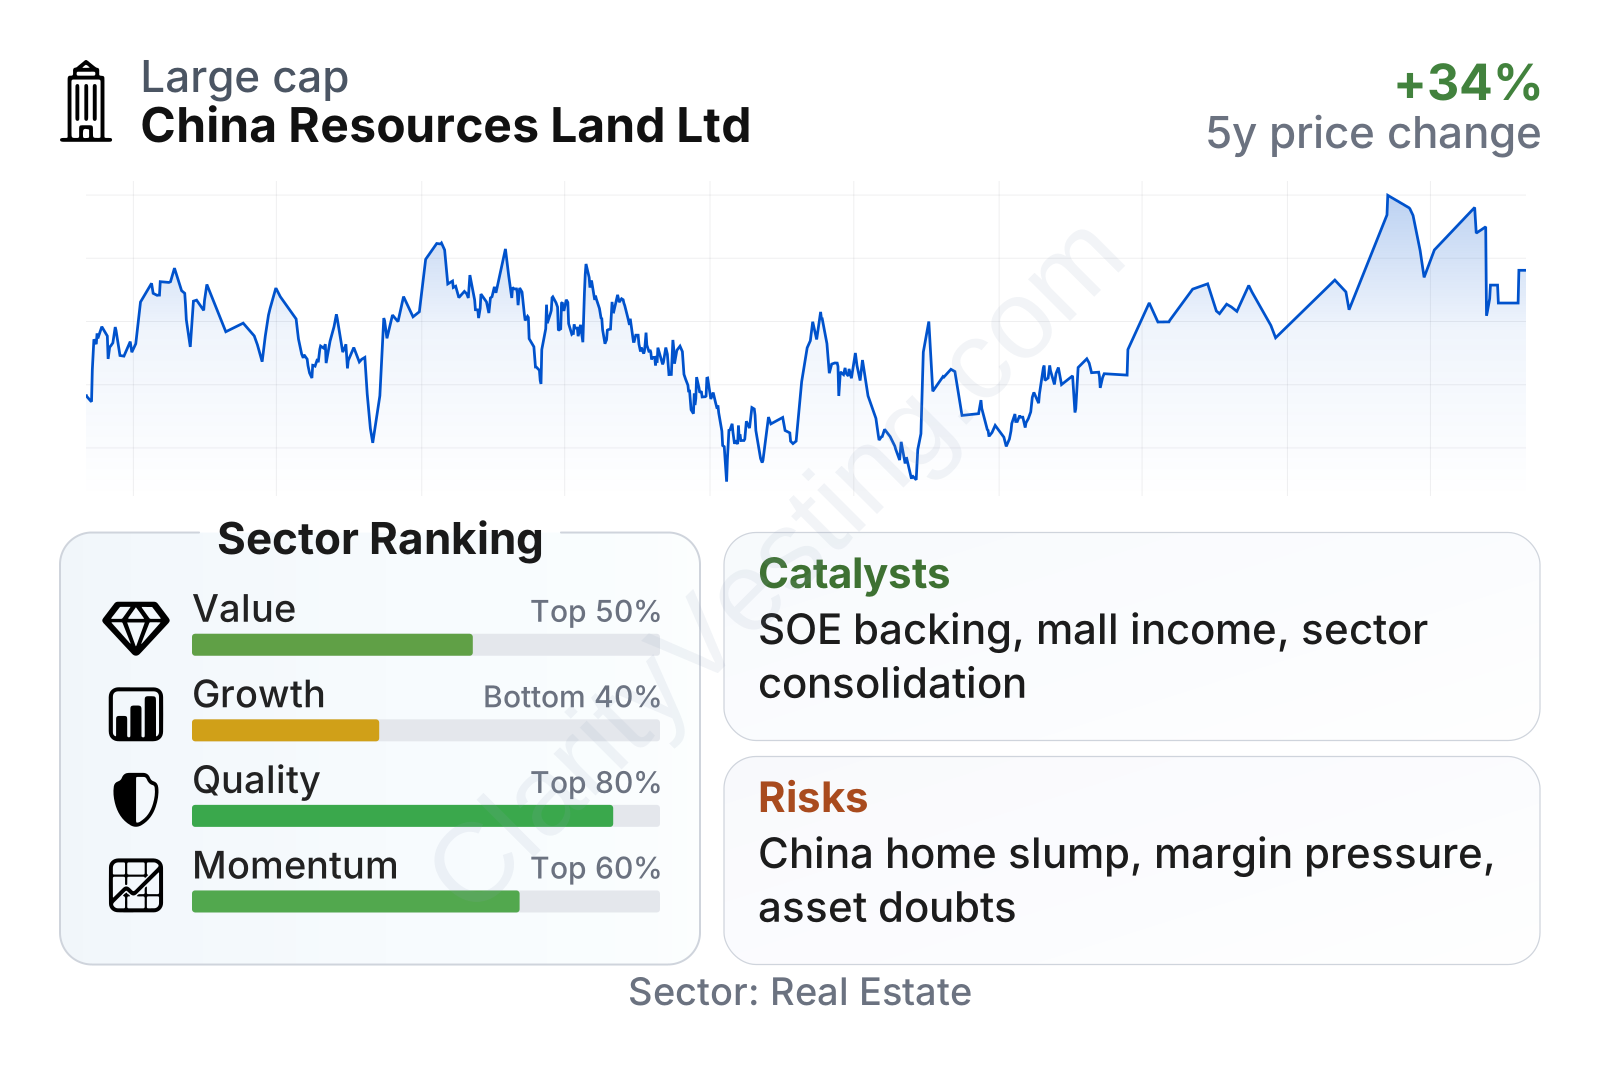
China Resources Land stands out as a large real estate developer with relatively strong balance-sheet quality for its sector. Profitability remains above many peers on return metrics, and leverage looks much more controlled than the real estate sector median, especially on net debt relative to earnings and interest coverage. At the same time, current growth metrics are mixed: recent revenue declined sharply year over year, margins have compressed over five years, and book value per share has moved in the wrong direction. Market behavior has improved recently, with the shares performing better than many sector peers over the last six months and trading well above their longer-term trend line.
Growth
China Resources Land operates in one of the most important but also most challenged sectors in China: residential and mixed-use real estate. In the short term, the sector is not a straightforward growth market because Chinese homebuyers remain cautious, developers face weak demand in many cities, and policymakers are still trying to stabilize confidence. But within that difficult environment, stronger state-backed groups with better funding access and higher-quality land banks have been gaining relative share as weaker private developers retreat.
The company’s strategy is sensible for this environment. Instead of relying only on rapid land turnover and apartment presales, it combines development profits with recurring income from malls and commercial properties. This makes the business less dependent on one housing cycle. Its shopping mall platform is especially important because prime retail assets in stronger Chinese cities can keep generating rent and foot traffic even when apartment sales slow.
Revenue per share has held up better over a multiyear period than the recent yearly slowdown might suggest. The broader pattern is that scale has been maintained and even expanded over five years, despite a weak industry backdrop. That does not remove cyclical risk, but it suggests the company has been more durable than many developers in China.
Another growth support is policy direction. Chinese authorities have continued to signal support for stabilizing the property market, urban renewal, and better-quality developers. China Resources Land is well placed in those themes because it has deep exposure to top-tier and higher-tier cities, redevelopment capabilities, and backing from a central state-owned parent. If housing demand normalizes even modestly in core cities, stronger operators could see better project conversion, healthier pricing, and improved land acquisition opportunities.
The dividend record also gives some insight into operating resilience. The payout has not been a straight upward line, but it has remained meaningful rather than disappearing, which is notable in a sector where many peers have faced far more severe stress.
The recent pattern shows a dividend that rose through 2023 and then softened. That fits the broader picture: the company still generates cash and remains profitable, but management appears to be balancing shareholder distributions with caution as the market works through a prolonged adjustment.
A further catalyst is industry consolidation. In a weaker real estate cycle, companies with healthier funding profiles can acquire land, projects, or market share on more favorable terms. China Resources Land appears better positioned than many domestic peers to benefit from that process over time.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


