Stock Analysis · Cencora Inc (COR)
Overview
Cencora is one of the largest healthcare distribution companies in the world. Its core role is to move pharmaceutical products from drug manufacturers to pharmacies, hospitals, health systems, physician practices, and other care sites. In simple terms, it sits in the middle of the medicine supply chain and helps make sure products reach patients safely, efficiently, and on time.
The business is large, operationally complex, and built around scale. Cencora handles branded drugs, specialty therapies, generics, over-the-counter products, and a range of support services for pharmaceutical companies and providers. Specialty medicines are especially important because they are high-cost, fast-growing therapies used in areas such as oncology and other complex diseases.
Based on the company’s recent reporting structure, revenue is mainly generated from pharmaceutical distribution and related services, with the U.S. business dominating the mix.
- U.S. Healthcare Solutions: about 84% to 86% of revenue — pharmaceutical distribution, specialty distribution, provider and pharmacy services, animal health, and related support activities in the United States.
- International Healthcare Solutions: about 14% to 16% of revenue — wholesale and distribution operations outside the United States, mainly in Europe and other international markets, plus manufacturer services and global commercialization support.
At a high level, the company’s economics reflect the nature of drug distribution: very high revenue, very high product costs, and thin margins. That means success depends less on large markups and more on scale, logistics, customer relationships, compliance capabilities, and disciplined expense control.
The long-term pattern shows a business that has kept expanding its revenue base, while gross profit has grown more steadily than operating income. That reinforces a key point for readers: Cencora is a volume-and-efficiency business, not a high-margin software-style company.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Healthcare | |
| Industry | Medical Distribution | |
| Market Cap ⓘ | $64.96B | |
| Beta ⓘ | 0.58 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 25.48 | 25.42 |
| P/B Ratio ⓘ | 22.93 | 3.08 |
| FCF Yield ⓘ | 6.25% | 3.12% |
| Dividend Yield ⓘ | 0.68% | 1.85% |
| EBIT / EV ⓘ | 5.96% | 0.56% |
| PEG ⓘ | 0.65 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 5.10% | 7.50% |
| RPS Growth (5Y CAGR) ⓘ | 12.53% | 8.60% |
| EPS Growth (5Y CAGR) ⓘ | 4.83% | -17.73% |
| BVPS Growth (5Y CAGR) ⓘ | 56.94% | 3.72% |
| Margin Growth (5Y Trend) ⓘ | -0.29% | -0.57% |
| FCF Growth (5Y CAGR) ⓘ | 9.53% | 0.96% |
| DPS Growth (5Y CAGR) ⓘ | 6.22% | 6.69% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 25.83% | 3.17% |
| ROA (Latest) ⓘ | 3.27% | 2.98% |
| ROIC (5Y Median) ⓘ | 34.78% | 4.56% |
| ROA (5Y Median) ⓘ | 2.93% | 1.87% |
| Net Debt / EBIT (Latest) ⓘ | 2.18 | 1.34 |
| Net Debt / EBIT (5Y Median) ⓘ | 1.69 | 1.86 |
| Net Debt / EBITDA (Latest) ⓘ | 1.73 | 1.00 |
| Net Debt / Assets ⓘ | 10.63% | 5.06% |
| EBITDA / Interest ⓘ | 10.34 | 9.55 |
| Operating Margin (Latest) ⓘ | 1.23% | 9.25% |
| Operating Margin (5Y Median) ⓘ | 0.93% | 7.33% |
| Debt to Equity (Latest) ⓘ | 384.25% | 26.68% |
| Profit Margin (Latest) ⓘ | 0.79% | 3.34% |
| Free Cash Flow (Latest) ⓘ | $4.06B | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +83.81% | +51.61% |
| 12M Return (excl. last month) ⓘ | +9.71% | +19.90% |
| 6M Return ⓘ | +10.26% | +10.10% |
| Price vs. 200-Day MA ⓘ | +6.91% | +6.44% |
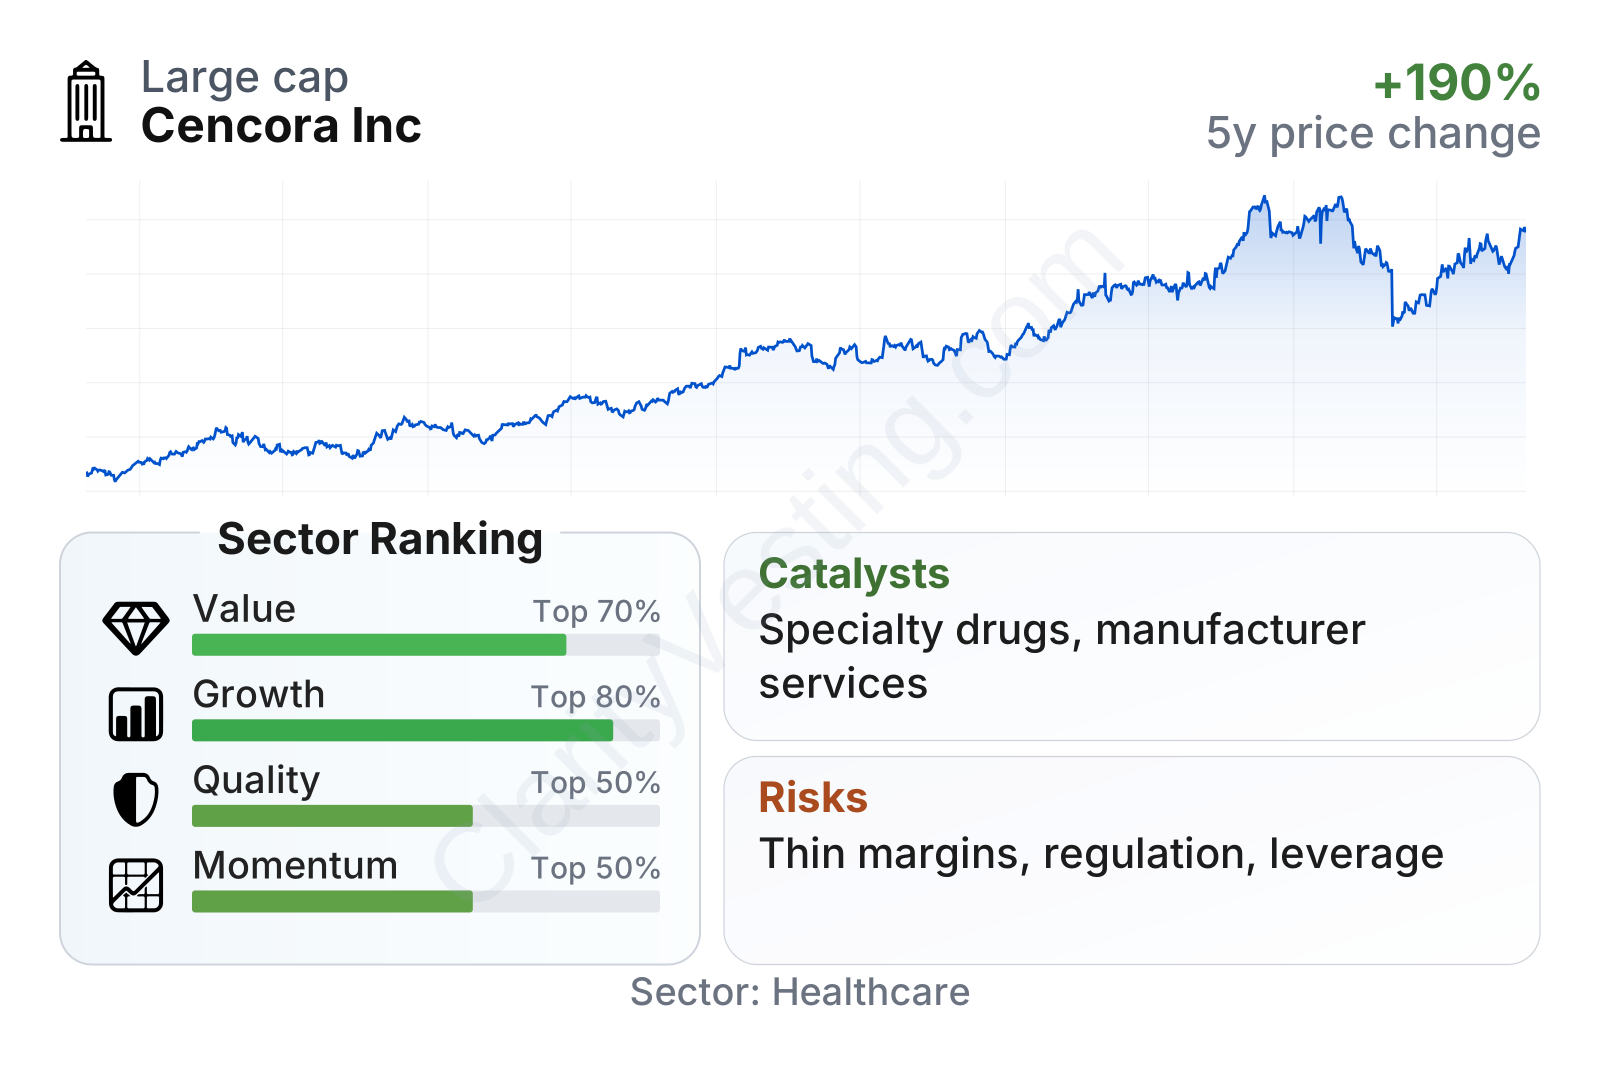
Cencora is a very large healthcare company with relatively low share-price volatility, as reflected by a beta well below 1. On valuation, earnings-based multiples look broadly moderate versus the healthcare sector, while free cash flow measures appear stronger than the sector median. Growth and quality indicators are also solid overall, especially in long-term revenue per share, free cash flow expansion, and returns on invested capital. The weaker area is recent market momentum, with the stock below its 200-day average and trailing shorter-term sector performance.
Growth
Cencora operates in a sector with durable long-term demand. Healthcare utilization tends to rise over time because of aging populations, the growing use of specialty medicines, and the increasing complexity of treatment delivery. Pharmaceutical distribution is not the most glamorous part of healthcare, but it is one of the most essential. As more therapies move through specialty channels and require tighter handling, reimbursement, and logistics support, large distributors can become even more embedded in the system.
The company’s strategy appears aligned with that trend. Cencora has continued to build around specialty distribution, manufacturer services, and global reach rather than relying only on traditional wholesale volumes. That matters because specialty drugs generally require more coordination, more data, and more service layers than standard medications. Those extra services can deepen customer relationships and improve the durability of the business, even if reported margins remain narrow.
Recent revenue growth has slowed from the unusually strong pace seen earlier in the period, but it has remained positive. The latest year-over-year pace is around 5%, which is below some earlier double-digit periods yet still shows continued expansion on an already very large base. Over a five-year view, revenue per share growth has been notably stronger than the sector median, suggesting that the company has done more than simply ride industry inflation.
Cash generation is an important part of the investment case because distributors often operate on thin accounting margins. Free cash flow has been uneven from year to year, which is common in this industry because working capital can swing with product timing, pricing, and customer activity. Even so, the longer-term trend remains constructive, and the current free cash flow yield stands out as strong compared with the sector median.
A major catalyst for future growth is continued expansion in specialty pharmaceuticals and oncology-related distribution. Another is the company’s manufacturer-facing service offering, which can benefit as drugmakers seek help with market access, commercialization, and global distribution. Recent company communications have also highlighted ongoing business wins, customer retention, and demand tied to high-value therapies, all of which support the idea that Cencora is participating in structural healthcare growth rather than depending on a short-lived cycle.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


