Stock Analysis · Concentra Group Holdings Parent Inc (CON)
Overview
Concentra Group Holdings Parent Inc operates occupational health clinics in the United States. Its business is centered on employer-focused care rather than traditional hospital services. The company helps employers manage workplace injuries, drug and alcohol testing, physical examinations, and other health services tied to hiring, compliance, and employee readiness. It also provides urgent care services to consumers in many of its centers, but the employer channel remains the core of the model.
This is a healthcare business with a fairly specific niche: keeping workers healthy, helping employees return to work after injury, and supporting employers with testing and screening requirements. That positioning matters because demand is linked not only to general healthcare usage, but also to employment levels, workplace safety activity, and regulatory testing needs.
Based on company filings, Concentra’s revenue is primarily generated from patient visits and related ancillary services delivered through its centers. The broad mix can be summarized this way:
- Workers’ compensation injury care: likely the largest revenue source, supported by treatment of job-related injuries, rehabilitation, and return-to-work services.
- Employer services: a major contributor that includes physicals, drug and alcohol screening, testing programs, vaccinations, and compliance-related exams.
- Consumer and urgent care visits: a smaller but still meaningful stream from non-occupational walk-in care.
- Ancillary and onsite services: additional revenue from services such as specialty exams, telemedicine support, and employer programs delivered beyond the clinic visit itself.
Public filings describe these activities clearly, but do not always break revenue into precise percentages across every service line. What is clear is that the employer-oriented business is the foundation of Concentra’s model, while urgent care adds volume, broader center utilization, and cross-traffic.
Over the last several years, revenue has moved from about $1.7 billion to more than $2.1 billion, while operating income has also expanded. Gross profit has grown faster than sales over that period, which suggests the business has been gaining scale and managing pricing and clinic utilization reasonably well. Interest expense remains meaningful, however, which limits how much of that operating progress reaches net income.
The long-term pattern shows a business that has increased sales and operating profit, with stronger gross profit in recent years. The main constraint has been financing costs, which have absorbed a noticeable portion of operating earnings.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Healthcare | |
| Industry | Medical Care Facilities | |
| Market Cap ⓘ | $4.98B | |
| Beta ⓘ | 0.63 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 25.22 | 25.42 |
| P/B Ratio ⓘ | 11.44 | 3.08 |
| FCF Yield ⓘ | 7.02% | 3.12% |
| Dividend Yield ⓘ | 0.64% | 1.85% |
| EBIT / EV ⓘ | 5.92% | 0.56% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 10.00% | 7.50% |
| RPS Growth (5Y CAGR) ⓘ | 5.39% | 8.60% |
| EPS Growth (5Y CAGR) ⓘ | -6.78% | -17.73% |
| BVPS Growth (5Y CAGR) ⓘ | -27.53% | 3.72% |
| Margin Growth (5Y Trend) ⓘ | -2.35% | -0.57% |
| FCF Growth (5Y CAGR) ⓘ | -5.19% | 0.96% |
| DPS Growth (5Y CAGR) ⓘ | 47.39% | 6.69% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 14.62% | 3.17% |
| ROA (Latest) ⓘ | 6.79% | 2.98% |
| ROIC (5Y Median) ⓘ | N/A | 4.56% |
| ROA (5Y Median) ⓘ | 6.65% | 1.87% |
| Net Debt / EBIT (Latest) ⓘ | 5.23 | 1.34 |
| Net Debt / EBIT (5Y Median) ⓘ | 4.89 | 1.86 |
| Net Debt / EBITDA (Latest) ⓘ | 4.32 | 1.00 |
| Net Debt / Assets ⓘ | 65.97% | 5.06% |
| EBITDA / Interest ⓘ | 4.29 | 9.55 |
| Operating Margin (Latest) ⓘ | 16.61% | 9.25% |
| Operating Margin (5Y Median) ⓘ | 15.62% | 7.33% |
| Debt to Equity (Latest) ⓘ | 449.35% | 26.68% |
| Profit Margin (Latest) ⓘ | 8.69% | 3.34% |
| Free Cash Flow (Latest) ⓘ | $349.75M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | N/A | +51.61% |
| 12M Return (excl. last month) ⓘ | +68.83% | +19.90% |
| 6M Return ⓘ | +77.29% | +10.10% |
| Price vs. 200-Day MA ⓘ | +43.69% | +6.44% |
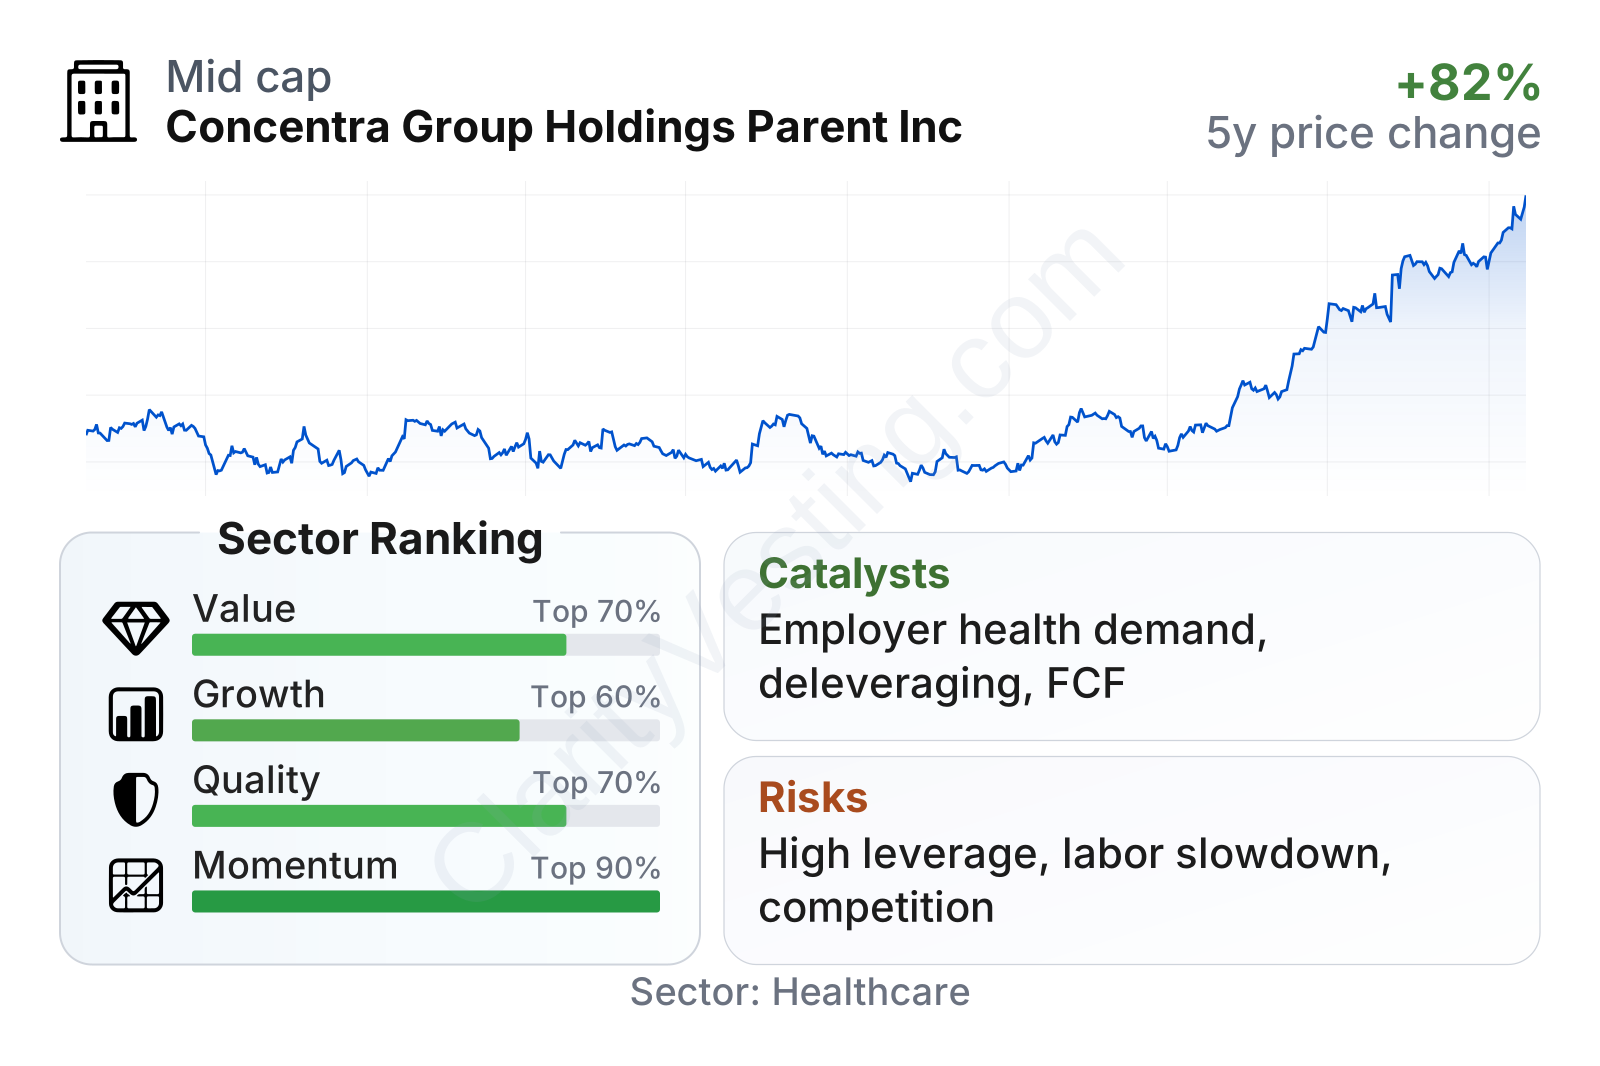
Concentra is a mid-sized healthcare company with a market value around the mid-single-digit billions of dollars and a stock that has recently shown strong momentum. The factor profile is mixed in a useful way: quality and cash generation look strong relative to much of the healthcare sector, while growth is positive but not exceptional. The company’s return on invested capital and return on assets are well above sector medians, and free cash flow yield also stands out favorably. On the other hand, the balance sheet carries much more leverage than the typical healthcare peer, which is an important counterweight to those strengths.
The stock’s recent move has been strong, and the company’s beta is below 1, suggesting that historically it has not behaved like one of the more volatile names in the market. Even after the recent rally, the earnings multiple remains below the sector median, although not by a very wide margin anymore.
Growth
Concentra operates in a part of healthcare that has durable structural support. Employers continue to need injury treatment, return-to-work programs, drug testing, physical exams, and compliance services. Those needs do not disappear when consumer healthcare patterns shift. In addition, labor shortages in some industries and continued attention to worker productivity can support demand for faster occupational health services. This makes the sector attractive for steady, service-based expansion, even if it is not usually a hypergrowth area.
The company’s strategy also makes practical sense. A nationwide clinic footprint creates local density, referral relationships, and administrative scale. Occupational health benefits from repeat employer relationships, network contracts, and familiarity with claims handling, all of which can be hard for smaller providers to replicate at scale. Because many services are standardized and recurring, there is room for operational efficiency as visit volume grows.
Recent revenue growth has been solid, running around 10% most recently after several quarters in the mid-teens. That indicates the business is still growing, but the pace has moderated from earlier levels. For a mature clinic-based operator, this is still a healthy rate, especially when paired with stable margins.
Cash generation has improved meaningfully. Trailing free cash flow has climbed from roughly $180 million to nearly $300 million over the period shown, and the latest trailing figure in the broader metrics is higher still. That is important because clinic-based healthcare businesses ultimately need to translate patient volume into cash, not just accounting earnings. Stronger free cash flow gives Concentra more flexibility for debt reduction, expansion, and shareholder returns.
A visible catalyst is the company’s ability to continue converting its employer-focused positioning into recurring volume. If employment remains firm in sectors that require screening, injury management, and compliance testing, Concentra has a direct path to additional visit growth. Another positive signal is that margin levels have remained well above sector medians, which suggests the company has room to benefit from scale even if top-line growth slows from its recent peak.
Recent investor communications have also emphasized center network reach, employer relationships, and a broad service offering. Those features are not a one-quarter event, but they are meaningful because they support multi-year growth through cross-selling and deeper penetration of existing clients rather than relying only on opening new locations.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


