Stock Analysis · Croda International PLC (COIHY)
Overview
Croda International PLC is a British specialty chemicals company that develops ingredient technologies used in everyday and high-value products. Rather than competing mainly on commodity chemical volume, Croda focuses on formulations and performance ingredients that help customers improve texture, stability, delivery, preservation, and efficiency. Its products are used in consumer care, life sciences, and industrial applications, giving the business exposure to personal care, pharmaceuticals, crop technologies, and selected industrial niches.
The company reports revenue through three main business areas. Based on the latest annual reporting structure, the revenue mix is approximately:
- Consumer Care: about 50% of revenue. This includes ingredients for beauty care, personal care, home care, fragrance, and related consumer formulations.
- Life Sciences: about 35% of revenue. This segment includes crop protection adjuvants and seed enhancement, pharma-related excipients and delivery systems, and health care ingredients.
- Industrial Specialties: about 15% of revenue. This covers ingredients used in lubricants, polymers, coatings, energy-related uses, and other industrial formulations.
That mix matters because Croda is not just selling chemical volume; it is selling performance, formulation know-how, regulatory expertise, and customer integration. This usually supports better margins than basic commodity chemicals, but it also means growth can depend on product cycles, customer destocking, and end-market confidence. Over the last several years, revenue rose strongly into 2022 and then retreated, while profitability compressed much more sharply than sales, showing that the business is still working through a difficult post-boom normalization period.
The long-term pattern shows a business that historically produced solid gross profit and operating income, but recent years brought a clear squeeze: sales are below the 2022 peak, and net income has fallen much faster than revenue. That gap suggests weaker mix, lower operating leverage, and a slower recovery than shareholders had expected.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Specialty Chemicals | |
| Market Cap ⓘ | $6.71B | |
| Beta ⓘ | 0.92 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 63.32 | 16.92 |
| P/B Ratio ⓘ | 3.12 | 1.66 |
| FCF Yield ⓘ | 3.87% | 5.83% |
| Dividend Yield ⓘ | 3.08% | 2.07% |
| EBIT / EV ⓘ | N/A | 6.38% |
| PEG ⓘ | 0.48 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 2.90% | 11.25% |
| RPS Growth (5Y CAGR) ⓘ | -3.13% | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | -22.95% | -15.24% |
| BVPS Growth (5Y CAGR) ⓘ | 5.49% | 5.49% |
| Margin Growth (5Y Trend) ⓘ | -8.80% | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | -2.90% | 0.37% |
| DPS Growth (5Y CAGR) ⓘ | 3.44% | 5.91% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 9.59% |
| ROA (Latest) ⓘ | 6.23% | 4.92% |
| ROIC (5Y Median) ⓘ | 13.53% | 7.91% |
| ROA (5Y Median) ⓘ | 4.76% | 3.92% |
| Net Debt / EBIT (Latest) ⓘ | 1.17 | 1.36 |
| Net Debt / EBIT (5Y Median) ⓘ | 1.88 | 1.69 |
| Net Debt / EBITDA (Latest) ⓘ | 0.75 | 0.93 |
| Net Debt / Assets ⓘ | 16.37% | 13.69% |
| EBITDA / Interest ⓘ | N/A | 12.38 |
| Operating Margin (Latest) ⓘ | 14.60% | 13.24% |
| Operating Margin (5Y Median) ⓘ | 15.47% | 11.82% |
| Debt to Equity (Latest) ⓘ | 36.06% | 40.30% |
| Profit Margin (Latest) ⓘ | 4.61% | 6.38% |
| Free Cash Flow (Latest) ⓘ | $259.55M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +8.66% | +73.47% |
| 12M Return (excl. last month) ⓘ | +21.53% | +27.59% |
| 6M Return ⓘ | +21.44% | -4.02% |
| Price vs. 200-Day MA ⓘ | +21.52% | -0.65% |
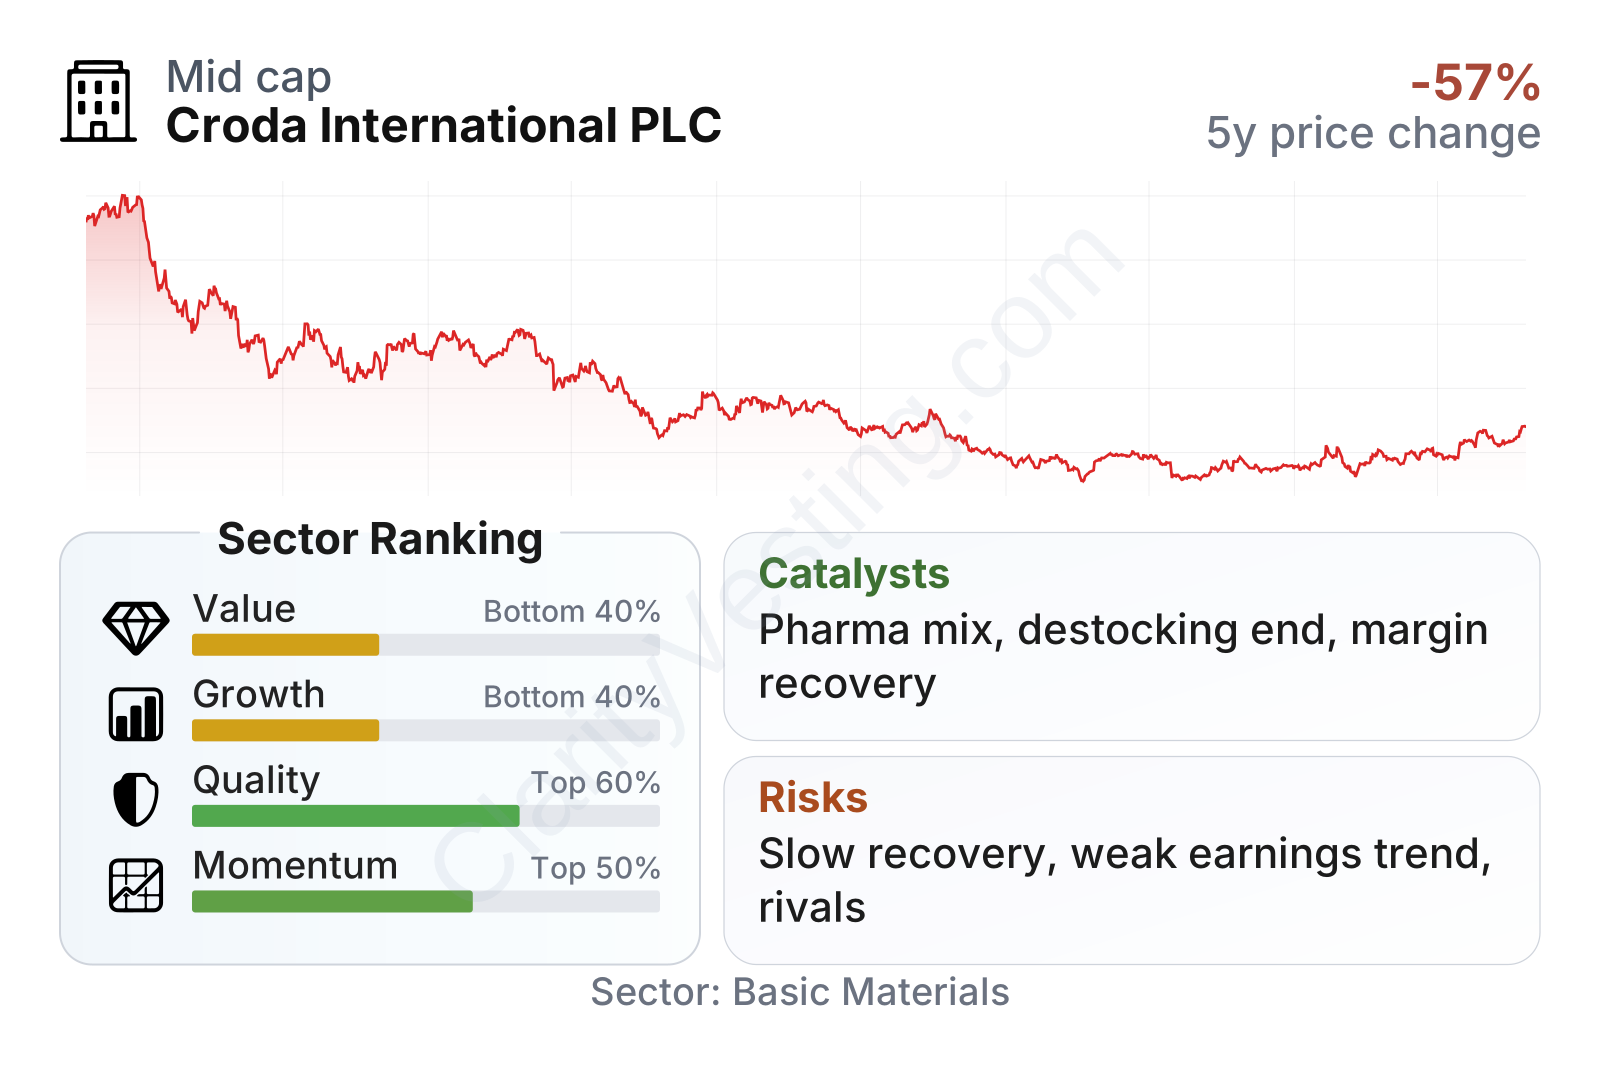
Croda is a mid-sized specialty chemicals group with below-market volatility, but the current factor profile is mixed. Quality remains respectable, supported by operating margins that still sit above the sector median and balance-sheet leverage that is not excessive. The weaker areas are growth and valuation: revenue growth has been modest, five-year earnings trends are negative, and traditional valuation ratios such as P/E and price-to-book sit above sector medians. Share price momentum has improved over the last 6 to 12 months, but that comes after a much weaker three-year stock performance.
Growth
Croda operates in parts of the chemicals market that generally have favorable long-term demand drivers. Personal care ingredients benefit from premiumization, innovation, and product differentiation. Pharma excipients and delivery systems are supported by complex biologics, vaccine technologies, and stricter formulation requirements. Crop protection technologies can also grow as agriculture looks for better efficacy, lower application intensity, and more sustainable solutions. These are structurally more attractive niches than bulk chemicals, even if they are not immune to inventory corrections and cyclical swings.
The company’s strategy also makes sense on paper for long-term expansion. Croda has been emphasizing higher-value niches, innovation-led products, and life sciences applications where technical barriers are higher and customer relationships are stickier. The business has also spent heavily on research and development and on capability building in areas such as pharma and consumer formulations. If end markets normalize, that positioning could help margins recover faster than revenue.
A central catalyst is the life sciences platform, especially pharma-related technologies and crop protection delivery systems. These areas can carry stronger margins and tend to rely more on qualification, regulation, and formulation expertise than on price alone. Another potential catalyst is volume normalization after the destocking phase that affected many specialty chemical customers. In that situation, even modest sales improvement can have an outsized effect on earnings because fixed costs are already in place.
Cash generation remains an important point to watch. Free cash flow has stayed positive but has been lower than the company’s stronger historical levels, which fits the broader picture of a business still recovering rather than already back at full strength. If free cash flow improves meaningfully from here, it would reinforce the case that earnings pressure was cyclical rather than structural.
Recent company updates have pointed to continued focus on self-help measures, portfolio quality, cost discipline, and selective investment in higher-return categories. For a company like Croda, the most significant opportunity is not explosive top-line growth; it is a combination of mix improvement, margin recovery, and steadier execution in segments where technical differentiation matters more than raw scale.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


