Stock Analysis · Vita Coco Company Inc (COCO)
Overview
Vita Coco Company Inc. sells coconut water and other beverage products, with its core business built around ready-to-drink coconut water marketed under the Vita Coco brand. The company operates in the non-alcoholic beverage category and positions itself as a better-for-you refreshment brand. In addition to branded products, it also has a private label business that supplies coconut water products for retail partners.
The business is still heavily centered on coconut water, which remains the company’s defining product and primary growth engine. Based on the company’s recent annual reporting, revenue is mainly generated from the following sources:
- Branded coconut water and related branded beverages: approximately 85% to 90% of revenue. This includes Vita Coco coconut water and adjacent branded products sold through grocery, club, convenience, e-commerce, and foodservice channels.
- Private label products: approximately 10% to 15% of revenue. This business supplies retailer-owned beverage offerings and is typically lower margin than the branded segment.
- Other products: a small share of revenue. This includes smaller lines such as protein-infused beverages or limited adjacent offerings, but they are not currently the main economic driver.
Geographically, the United States is the largest market, with international business adding diversification but not changing the fact that the company’s performance is primarily tied to U.S. retail demand, distribution gains, and category growth.
One notable feature of the business model is that profitability has improved much faster than sales over the last few years. Revenue moved from about $380 million in 2021 to about $610 million in 2025, while net income rose from about $19 million to more than $71 million over the same period. That suggests the company has benefited from scale, better gross margins, and tighter operating discipline rather than relying on sales growth alone.
The long-term pattern here is encouraging: cost of goods has remained a large expense, as expected for a beverage company, but gross profit and operating income have expanded meaningfully since 2022. Selling and marketing expenses have also grown, yet earnings have still widened, which points to a business that has recently become more efficient as it scales.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Consumer Defensive | |
| Industry | Beverages - Non-Alcoholic | |
| Market Cap ⓘ | $3.34B | |
| Beta ⓘ | 0.75 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 31.89 | 17.88 |
| P/B Ratio ⓘ | 8.68 | 1.29 |
| FCF Yield ⓘ | 3.73% | 12.39% |
| Dividend Yield ⓘ | N/A | 2.85% |
| EBIT / EV ⓘ | 4.60% | 6.43% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 28.10% | 4.10% |
| RPS Growth (5Y CAGR) ⓘ | 10.46% | 6.18% |
| EPS Growth (5Y CAGR) ⓘ | 83.06% | -13.59% |
| BVPS Growth (5Y CAGR) ⓘ | 25.66% | 3.20% |
| Margin Growth (5Y Trend) ⓘ | 8.77% | -0.15% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 4.10% |
| DPS Growth (5Y CAGR) ⓘ | 88.73% | 6.79% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 31.09% | 12.34% |
| ROA (Latest) ⓘ | 21.17% | 6.30% |
| ROIC (5Y Median) ⓘ | 24.16% | 10.49% |
| ROA (5Y Median) ⓘ | 17.27% | 5.44% |
| Net Debt / EBIT (Latest) ⓘ | -1.86 | 1.96 |
| Net Debt / EBIT (5Y Median) ⓘ | -1.96 | 2.35 |
| Net Debt / EBITDA (Latest) ⓘ | -1.84 | 1.38 |
| Net Debt / Assets ⓘ | -46.18% | 21.51% |
| EBITDA / Interest ⓘ | N/A | 9.46 |
| Operating Margin (Latest) ⓘ | 20.15% | 8.87% |
| Operating Margin (5Y Median) ⓘ | 11.74% | 9.53% |
| Debt to Equity (Latest) ⓘ | 3.51% | 72.35% |
| Profit Margin (Latest) ⓘ | 15.50% | 5.40% |
| Free Cash Flow (Latest) ⓘ | $124.44M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +119.22% | +20.92% |
| 12M Return (excl. last month) ⓘ | +31.44% | +2.13% |
| 6M Return ⓘ | +19.05% | +1.26% |
| Price vs. 200-Day MA ⓘ | -6.27% | +1.39% |
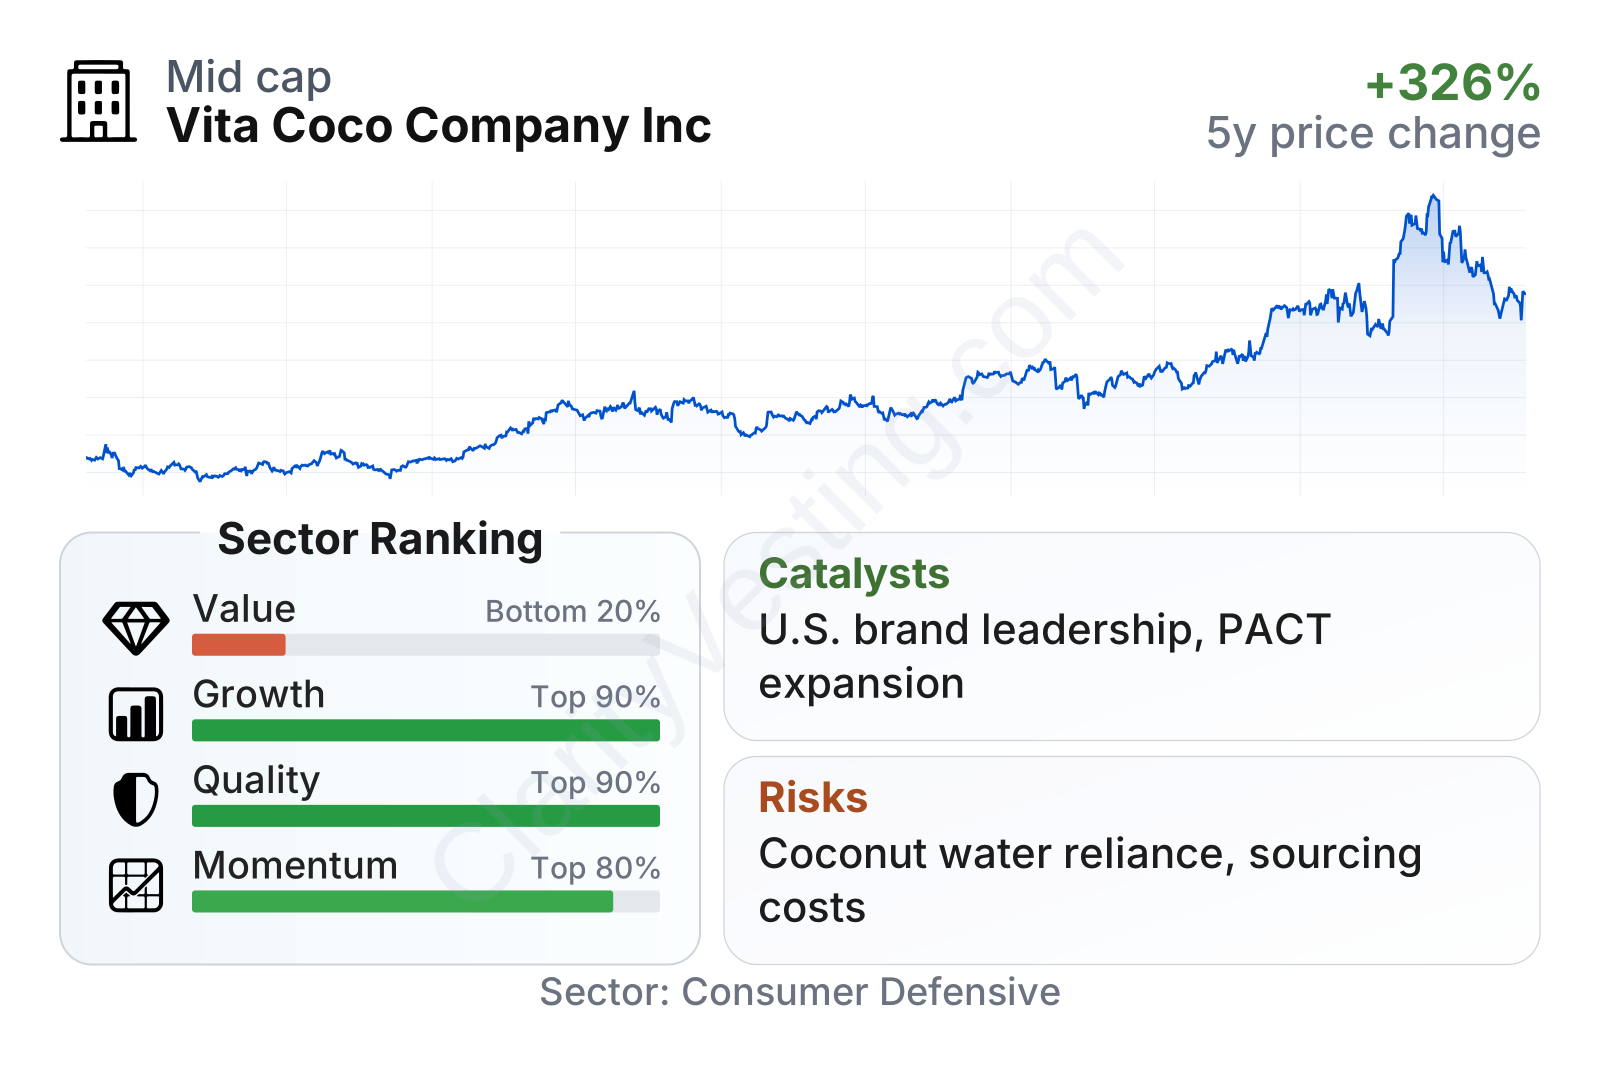
Vita Coco stands out for strong business quality and growth compared with much of the consumer defensive sector, but it does not screen as cheap. The company’s returns on capital and assets are well above sector norms, margins are stronger than typical beverage peers, and the balance sheet is unusually clean. At the same time, valuation metrics sit in a weaker relative position, meaning the market is already recognizing much of that operational strength.
The stock’s history also shows that sentiment can shift sharply. After a weak start as a public company, the shares have re-rated substantially as margins improved and growth accelerated. That helps explain why momentum remains strong over multiyear periods even if short-term trading can still be uneven.
Growth
Vita Coco operates in a part of the beverage market that continues to benefit from consumer interest in hydration, convenience, and products perceived as more natural than traditional soft drinks. Coconut water is still a niche compared with soda or sports drinks, but that can work in the company’s favor: a smaller category leaves room for distribution gains, household penetration growth, and product line extensions.
The company’s strategy appears coherent for long-term expansion. Management has focused on strengthening the core Vita Coco brand, widening retail distribution, supporting innovation around adjacent beverage formats, and using its supply chain relationships to preserve product availability. In a category where shelf space and repeat purchases matter, brand recognition and retailer relationships can compound over time.
Sales growth has not been perfectly smooth, but the broader trend has been strong. Recent year-over-year revenue growth has rebounded into the high-teens to high-20% range, with some quarters moving even higher. That is far ahead of the sector median, which suggests Vita Coco is gaining ground rather than merely keeping pace with the broader beverage industry.
Cash generation adds another positive layer. Free cash flow was negative earlier in the company’s public life, then turned clearly positive as profitability improved. While it has fluctuated from period to period, the business is now producing meaningful cash instead of consuming it, which gives management more flexibility for inventory, marketing, expansion, and shareholder returns.
A recent strategic catalyst has been the company’s agreement to acquire PACT, a refrigerated juice and smoothie brand. This matters because it extends Vita Coco beyond shelf-stable coconut water into the chilled functional beverage space. The deal is small relative to the overall company, but it shows a willingness to broaden the platform into adjacent categories where health-oriented consumers already shop.
Another growth support is financial capacity. With very low leverage and net cash, Vita Coco can invest behind the brand without the balance sheet pressure that often constrains smaller consumer companies. If category demand remains favorable, that combination of brand strength, retail presence, and financial flexibility could support continued expansion.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


