Stock Analysis · ConvaTec Group plc (CNVVY)
Overview
ConvaTec Group plc is a medical products company focused on chronic care. Its products are used in areas where patients often need ongoing treatment rather than one-time procedures, which can make demand more stable than in many other parts of healthcare. The company operates globally and sells to hospitals, clinicians, homecare channels, and distributors.
Its business is organized around four main product categories. Based on the company’s recent annual reporting, revenue is roughly distributed as follows:
- Advanced Wound Care: about 29% of revenue. This includes dressings and related products used to manage hard-to-heal wounds, burns, and surgical wounds.
- Ostomy Care: about 29% of revenue. These products support people living with a stoma, including pouches, skin barriers, and accessories.
- Continence Care: about 27% of revenue. This segment includes intermittent catheters and related continence products used in hospitals and at home.
- Infusion Care: about 15% of revenue. This business provides infusion sets and devices used in insulin delivery and other infusion therapies.
The mix matters because ConvaTec is not dependent on a single product line, yet it remains focused enough to build expertise in specialized care categories. Geographically, the company is also diversified, with meaningful sales across North America, Europe, and international markets.
The financial flow over recent years shows a useful pattern: revenue has been moving upward, gross profit has expanded, and operating income has improved faster than sales. Selling and administrative costs have stayed relatively controlled while research and development spending has remained present, suggesting the company has been improving efficiency without stepping away from product development.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Healthcare | |
| Industry | Medical Instruments & Supplies | |
| Market Cap ⓘ | $6.01B | |
| Beta ⓘ | 0.77 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 50.28 | 24.79 |
| P/B Ratio ⓘ | 4.31 | 3.08 |
| FCF Yield ⓘ | 5.63% | 3.15% |
| Dividend Yield ⓘ | 2.38% | 1.94% |
| EBIT / EV ⓘ | 9.48% | 0.57% |
| PEG ⓘ | 0.53 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 4.40% | 7.45% |
| RPS Growth (5Y CAGR) ⓘ | 4.55% | 8.61% |
| EPS Growth (5Y CAGR) ⓘ | -12.08% | -17.81% |
| BVPS Growth (5Y CAGR) ⓘ | -2.81% | 3.72% |
| Margin Growth (5Y Trend) ⓘ | 7.49% | -0.62% |
| FCF Growth (5Y CAGR) ⓘ | 12.21% | 1.04% |
| DPS Growth (5Y CAGR) ⓘ | 12.98% | 6.77% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 3.24% |
| ROA (Latest) ⓘ | 7.44% | 3.01% |
| ROIC (5Y Median) ⓘ | 6.53% | 4.60% |
| ROA (5Y Median) ⓘ | 3.57% | 1.89% |
| Net Debt / EBIT (Latest) ⓘ | 2.42 | 1.34 |
| Net Debt / EBIT (5Y Median) ⓘ | 4.72 | 1.84 |
| Net Debt / EBITDA (Latest) ⓘ | 1.54 | 1.00 |
| Net Debt / Assets ⓘ | 43.37% | 5.45% |
| EBITDA / Interest ⓘ | N/A | 9.64 |
| Operating Margin (Latest) ⓘ | 15.93% | 9.27% |
| Operating Margin (5Y Median) ⓘ | 11.83% | 7.38% |
| Debt to Equity (Latest) ⓘ | 121.83% | 28.58% |
| Profit Margin (Latest) ⓘ | 4.98% | 3.59% |
| Free Cash Flow (Latest) ⓘ | $338.11M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +35.83% | +42.80% |
| 12M Return (excl. last month) ⓘ | -4.79% | +18.50% |
| 6M Return ⓘ | -1.48% | +7.57% |
| Price vs. 200-Day MA ⓘ | +5.89% | +5.12% |
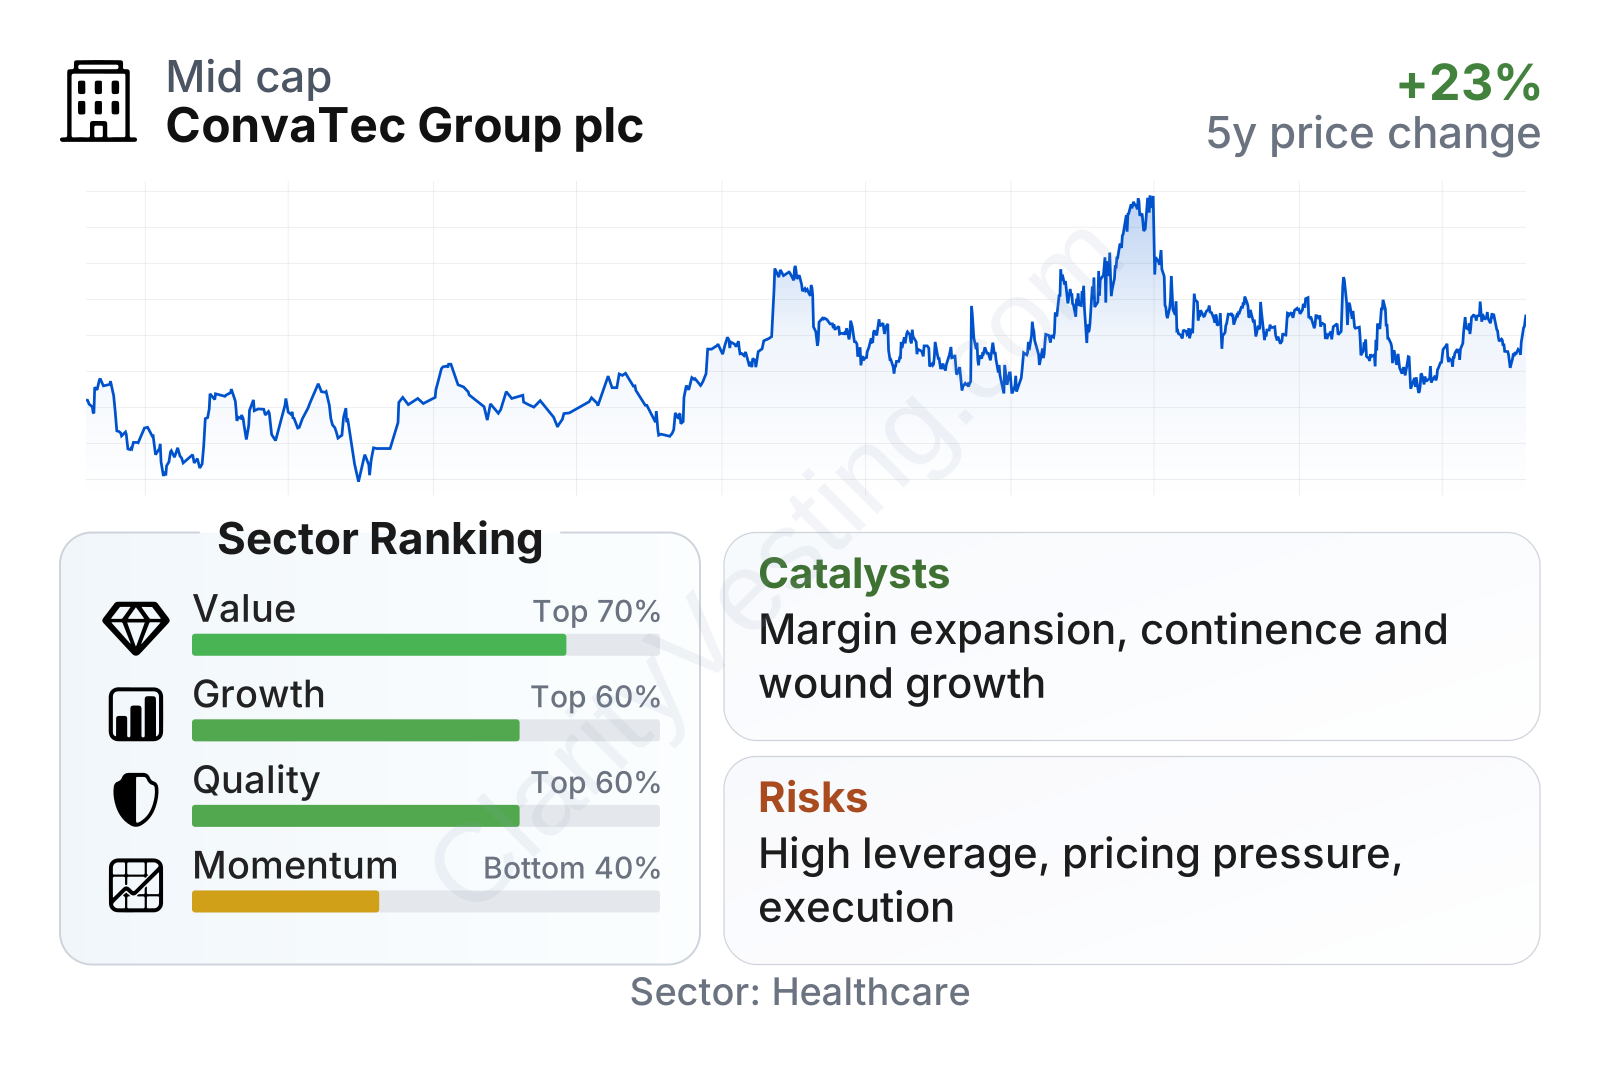
ConvaTec is a mid-sized healthcare company with a relatively low beta, which means its share price has tended to move less violently than the broader market. The factor breakdown is mixed but generally constructive. Value metrics are not uniformly cheap, especially on headline earnings multiples, yet cash generation looks stronger than the sector median. Quality and growth metrics are in the upper half of the sector, supported by solid returns on assets, improving margins, and good free cash flow progression. Momentum is the weakest area, reflecting a softer recent stock performance than many healthcare peers.
Growth
ConvaTec operates in parts of healthcare that benefit from durable long-term trends. Aging populations, rising rates of diabetes, increasing chronic wound prevalence, and the shift of care from hospitals to home settings all support demand for the company’s categories. These are not short-lived themes. They are broad structural drivers that can support recurring product usage over many years.
The company’s strategy also appears coherent for this type of market. Management has been emphasizing innovation in higher-value products, commercial execution, manufacturing efficiency, and expansion in underpenetrated regions. In continence care and wound care especially, product improvement can matter because better clinical outcomes and easier use can support pricing, retention, and market share.
Revenue growth has not been explosive, but it has been steady overall, with the pace improving meaningfully through 2024 and remaining positive into 2025. That profile fits the nature of the business: this is a healthcare supplier serving essential needs, so consistency can matter more than dramatic swings. The latest year-over-year growth rate is below the sector median, but the multi-year pattern points to an underlying business that has been strengthening rather than stalling.
Cash generation is one of the more encouraging elements. Free cash flow has moved up sharply from earlier levels and the five-year growth rate in free cash flow is well ahead of the sector median. That matters because it gives the company more flexibility to support dividends, invest in product development, improve manufacturing, and manage debt.
A notable catalyst is the ongoing expansion of margin. Recent annual results showed operating profit improving faster than revenue, which suggests the company is gaining from pricing, mix, and productivity actions. In addition, infusion care has strategic relevance because it gives ConvaTec exposure to insulin-delivery ecosystems, while advanced wound care and continence care offer opportunities tied to demographics and home-based treatment. Recent company communications have also highlighted continued innovation launches and category-focused execution, which support the idea that growth is being pursued through both new products and better commercial delivery.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


