Stock Analysis · ConvaTec Group Plc (CNVVF)
Overview
ConvaTec Group Plc is a medical products company focused on long-term, often recurring healthcare needs. Its products are used mainly outside emergency medicine and high-profile hospital equipment categories; instead, the business is centered on everyday care for people living with chronic conditions, wounds, continence issues, and kidney failure treatment at home or in clinical settings. That makes ConvaTec part of a healthcare niche where demand is often driven by aging populations, higher rates of diabetes and obesity, and the shift of care away from hospitals toward home and community settings.
The company organizes its business into four main product areas. Based on recent annual reporting, revenue is spread across them in the following order:
- Advanced Wound Care: about 29% of revenue. This includes dressings and related products used to treat hard-to-heal wounds such as surgical wounds, pressure injuries, and diabetic foot ulcers.
- Ostomy Care: about 28% of revenue. These products support people who have had surgery creating a stoma, including pouches, skin barriers, and accessories.
- Infusion Care: about 24% of revenue. This business mainly includes infusion sets and devices used with insulin pumps and other continuous infusion systems.
- Continence Care: about 19% of revenue. This segment includes intermittent catheters and related continence products.
Geographically, ConvaTec is diversified across North America, Europe, and international markets, which helps reduce dependence on a single healthcare system. The business model is attractive in one important way for long-term analysis: many products are consumables that need to be reordered regularly, so revenue tends to be steadier than for companies that rely on one-time capital equipment sales.
Over the last several years, the business has shown a visible improvement in profitability. Revenue has moved upward from just above $2.0 billion in 2021 to nearly $2.5 billion in 2025, while operating income has expanded faster than sales. That suggests the company has not only grown, but also become more efficient.
The financial profile points to a healthier mix over time: gross profit has increased steadily, operating income has improved meaningfully, and selling expenses have been kept relatively contained compared with revenue growth. The main area still weighing on net earnings is financing cost, although interest expense eased in 2025 versus 2023 and 2024.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 03, 2026 | |
| Context | ||
| Sector | Healthcare | |
| Industry | Medical Instruments & Supplies | |
| Market Cap ⓘ | $5.96B | |
| Beta ⓘ | 0.77 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 51.83 | 24.06 |
| P/B Ratio ⓘ | 4.27 | 3.08 |
| FCF Yield ⓘ | 5.70% | 3.07% |
| Dividend Yield ⓘ | 2.51% | 2.05% |
| EBIT / EV ⓘ | 9.43% | 0.63% |
| PEG ⓘ | 0.53 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 4.40% | 7.50% |
| RPS Growth (5Y CAGR) ⓘ | 5.06% | 8.70% |
| EPS Growth (5Y CAGR) ⓘ | -37.93% | -18.20% |
| BVPS Growth (5Y CAGR) ⓘ | -2.77% | 3.95% |
| Margin Growth (5Y Trend) ⓘ | 7.44% | -0.58% |
| FCF Growth (5Y CAGR) ⓘ | 12.76% | 0.88% |
| DPS Growth (5Y CAGR) ⓘ | 13.53% | 6.80% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 3.29% |
| ROA (Latest) ⓘ | 7.44% | 3.02% |
| ROIC (5Y Median) ⓘ | 6.53% | 4.75% |
| ROA (5Y Median) ⓘ | 3.57% | 1.93% |
| Net Debt / EBIT (Latest) ⓘ | 2.43 | 1.33 |
| Net Debt / EBIT (5Y Median) ⓘ | 4.72 | 1.83 |
| Net Debt / EBITDA (Latest) ⓘ | 1.57 | 0.99 |
| Net Debt / Assets ⓘ | 43.37% | 5.33% |
| EBITDA / Interest ⓘ | N/A | 9.63 |
| Operating Margin (Latest) ⓘ | 15.87% | 9.25% |
| Operating Margin (5Y Median) ⓘ | 11.83% | 7.80% |
| Debt to Equity (Latest) ⓘ | 121.83% | 28.99% |
| Profit Margin (Latest) ⓘ | 4.98% | 3.60% |
| Free Cash Flow (Latest) ⓘ | $339.56M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +27.81% | +37.48% |
| 12M Return (excl. last month) ⓘ | -8.35% | +20.85% |
| 6M Return ⓘ | +21.25% | +9.73% |
| Price vs. 200-Day MA ⓘ | N/A | +4.69% |
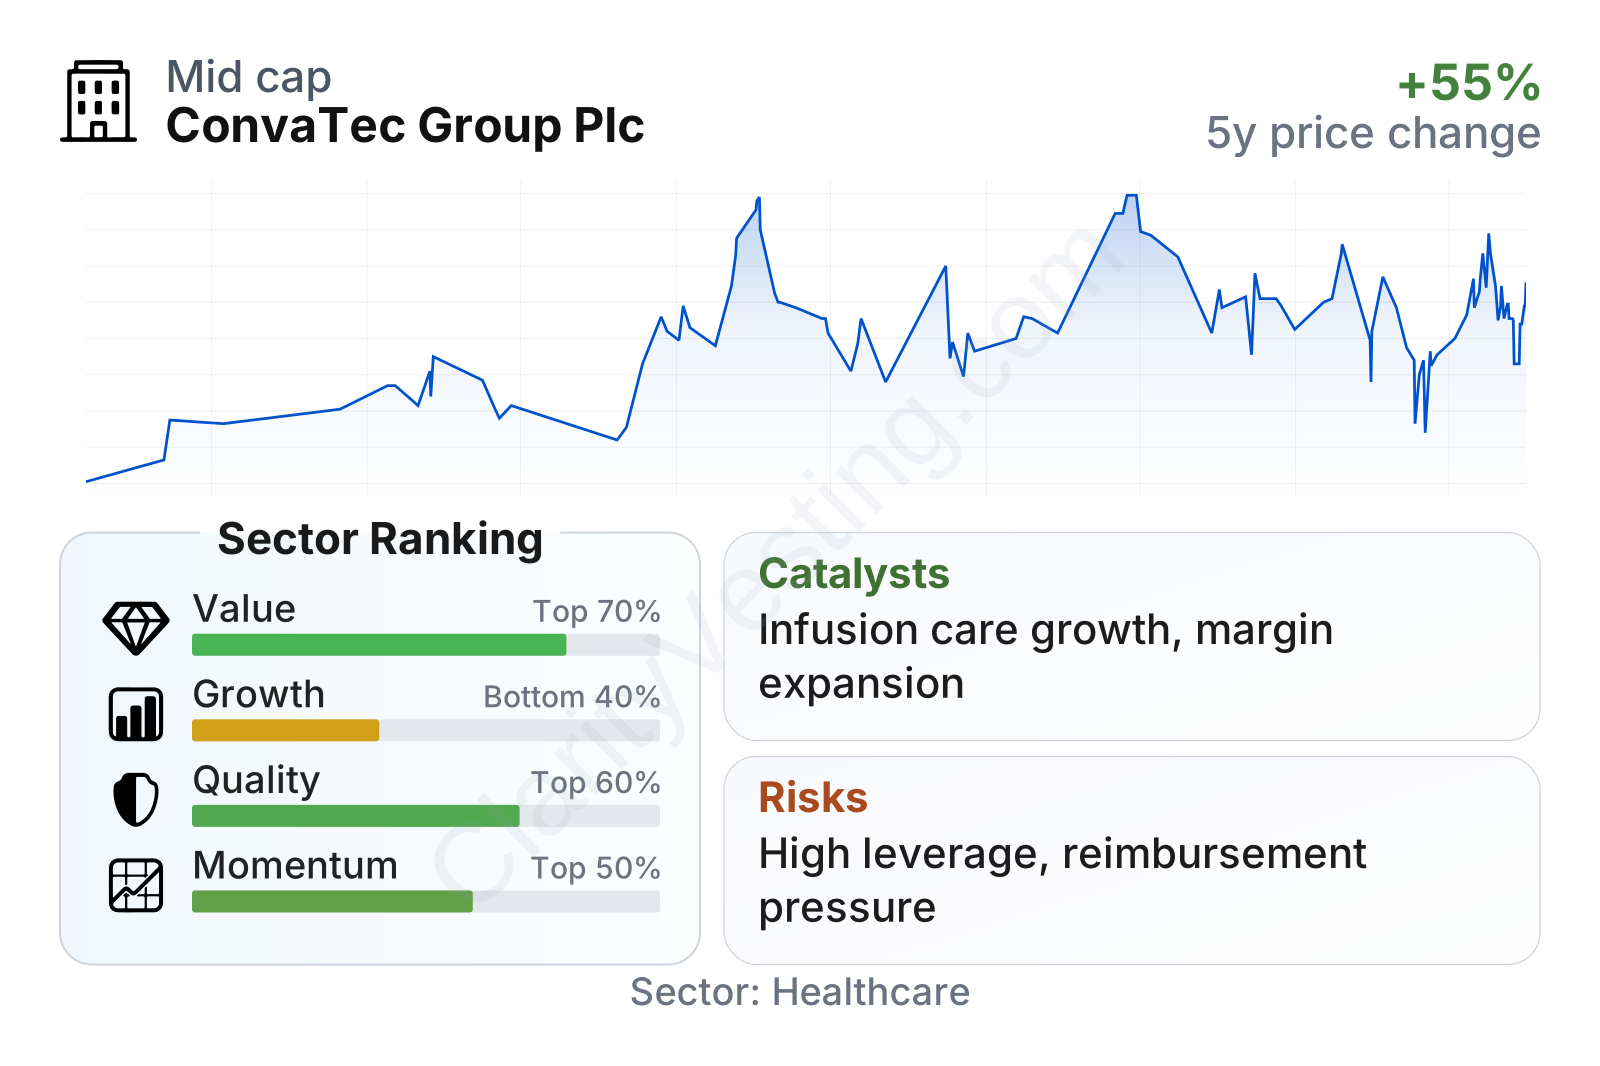
ConvaTec sits in the mid-sized range within healthcare and its share price behavior has been less volatile than the broader market, as reflected by a beta below 1. On valuation-related measures, the picture is mixed: the earnings multiple is above the sector median, but cash generation metrics are stronger, with free cash flow yield and EBIT relative to enterprise value comparing favorably. Quality is respectable rather than exceptional, supported by operating margins that are clearly above the sector median and returns on assets that also compare well.
The weaker area is growth relative to many healthcare peers. Recent revenue growth has been positive but below the sector median, and the stock’s recent momentum has been soft, with negative medium-term price performance while much of the sector did better. In other words, the market has recently become more cautious even as the business itself continues to produce solid cash flow and margin improvement.
Growth
ConvaTec operates in product categories tied to durable healthcare trends. Chronic wound treatment, ostomy care, continence care, and home-based infusion are all supported by aging populations, longer life expectancy for patients with complex conditions, and greater use of outpatient and home treatment. These are not fast-changing technology markets, but they can still produce steady expansion because the underlying patient need is recurring and often medically necessary.
The company’s strategy also makes practical sense. Management has been emphasizing innovation in higher-value products, commercial execution, and margin expansion rather than chasing growth at any cost. In wound care, that means products designed for more complex cases. In infusion care, the company has exposure to insulin delivery, an area connected to the rising prevalence of diabetes and broader adoption of pump-based therapy. In continence care and ostomy, the business benefits from specialist relationships, clinician familiarity, and patient reluctance to switch once a product works well.
A notable catalyst is the continuing expansion of the infusion business, especially where ConvaTec supplies components used in insulin pump systems. That area has stronger structural growth than some of the company’s more mature categories. Another supportive factor is operational improvement: over the last few years, operating margin has climbed into the mid-teens, well ahead of the sector median, showing that growth does not need to be dramatic for earnings and cash flow to improve.
Recent company communications have also highlighted continued product launches and geographic expansion efforts, especially in categories where adoption can still rise from relatively low penetration. For a long-term business assessment, the most important point is that ConvaTec does not need a breakthrough invention to grow; modest volume gains, better mix, and steady execution can still produce meaningful financial progress.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


