Stock Analysis · CONMED Corporation (CNMD)
Overview
CONMED Corporation is a medical technology company that makes devices and disposable products used in surgery and other medical procedures. Its focus is on helping surgeons perform minimally invasive and orthopedic procedures, along with supplying equipment used in general surgery, endoscopy, and gastroenterology. The business sells to hospitals, ambulatory surgery centers, and other healthcare facilities in the United States and internationally.
The company’s revenue is mainly generated by product sales across two reporting segments disclosed in recent annual filings:
- Orthopedics: approximately 55% to 60% of revenue in recent years. This segment includes sports medicine products, powered surgical instruments, visualization systems, implants, and related disposable items used in orthopedic and arthroscopic procedures.
- General Surgery: approximately 40% to 45% of revenue. This area includes electrosurgery products, endomechanical instruments, smoke evacuation, endoscopic technologies, and GI-related products used across laparoscopic, open, and flexible endoscopic procedures.
That mix matters because a meaningful part of CONMED’s business comes from recurring procedure-driven demand. Many of its products are single-use or procedure-linked, which can make revenue steadier than capital-equipment-only models. Geographically, the company still depends heavily on the U.S. market, but it also has a notable international presence that adds diversification.
Over the last several years, revenue expanded from roughly $1.0 billion to about $1.37 billion, showing that the company has been able to grow despite fluctuations in profitability. At the same time, expenses have not always moved in line with sales, which helps explain why earnings have been less stable than revenue.
The long-term pattern shows a business that has increased sales and gross profit, but with profit conversion becoming less consistent more recently. Selling and administrative expenses rose sharply in 2025, which weighed on operating income even as revenue continued to climb.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Healthcare | |
| Industry | Medical Devices | |
| Market Cap ⓘ | $1.35B | |
| Beta ⓘ | 0.94 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 24.29 | 24.79 |
| P/B Ratio ⓘ | 1.36 | 3.08 |
| FCF Yield ⓘ | 9.99% | 3.15% |
| Dividend Yield ⓘ | N/A | 1.94% |
| EBIT / EV ⓘ | 5.22% | 0.57% |
| PEG ⓘ | 1.84 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 0.30% | 7.45% |
| RPS Growth (5Y CAGR) ⓘ | 8.90% | 8.61% |
| EPS Growth (5Y CAGR) ⓘ | -4.05% | -17.81% |
| BVPS Growth (5Y CAGR) ⓘ | 8.00% | 3.72% |
| Margin Growth (5Y Trend) ⓘ | -3.31% | -0.62% |
| FCF Growth (5Y CAGR) ⓘ | 11.71% | 1.04% |
| DPS Growth (5Y CAGR) ⓘ | 2.42% | 6.77% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 4.11% | 3.24% |
| ROA (Latest) ⓘ | 2.44% | 3.01% |
| ROIC (5Y Median) ⓘ | 5.33% | 4.60% |
| ROA (5Y Median) ⓘ | 2.80% | 1.89% |
| Net Debt / EBIT (Latest) ⓘ | 7.04 | 1.34 |
| Net Debt / EBIT (5Y Median) ⓘ | 6.94 | 1.84 |
| Net Debt / EBITDA (Latest) ⓘ | 4.30 | 1.00 |
| Net Debt / Assets ⓘ | 34.64% | 5.45% |
| EBITDA / Interest ⓘ | 6.20 | 9.64 |
| Operating Margin (Latest) ⓘ | 8.24% | 9.27% |
| Operating Margin (5Y Median) ⓘ | 9.69% | 7.38% |
| Debt to Equity (Latest) ⓘ | 80.11% | 28.58% |
| Profit Margin (Latest) ⓘ | 4.12% | 3.59% |
| Free Cash Flow (Latest) ⓘ | $134.46M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | -49.30% | +42.80% |
| 12M Return (excl. last month) ⓘ | -9.35% | +18.50% |
| 6M Return ⓘ | +19.52% | +7.57% |
| Price vs. 200-Day MA ⓘ | +14.58% | +5.12% |
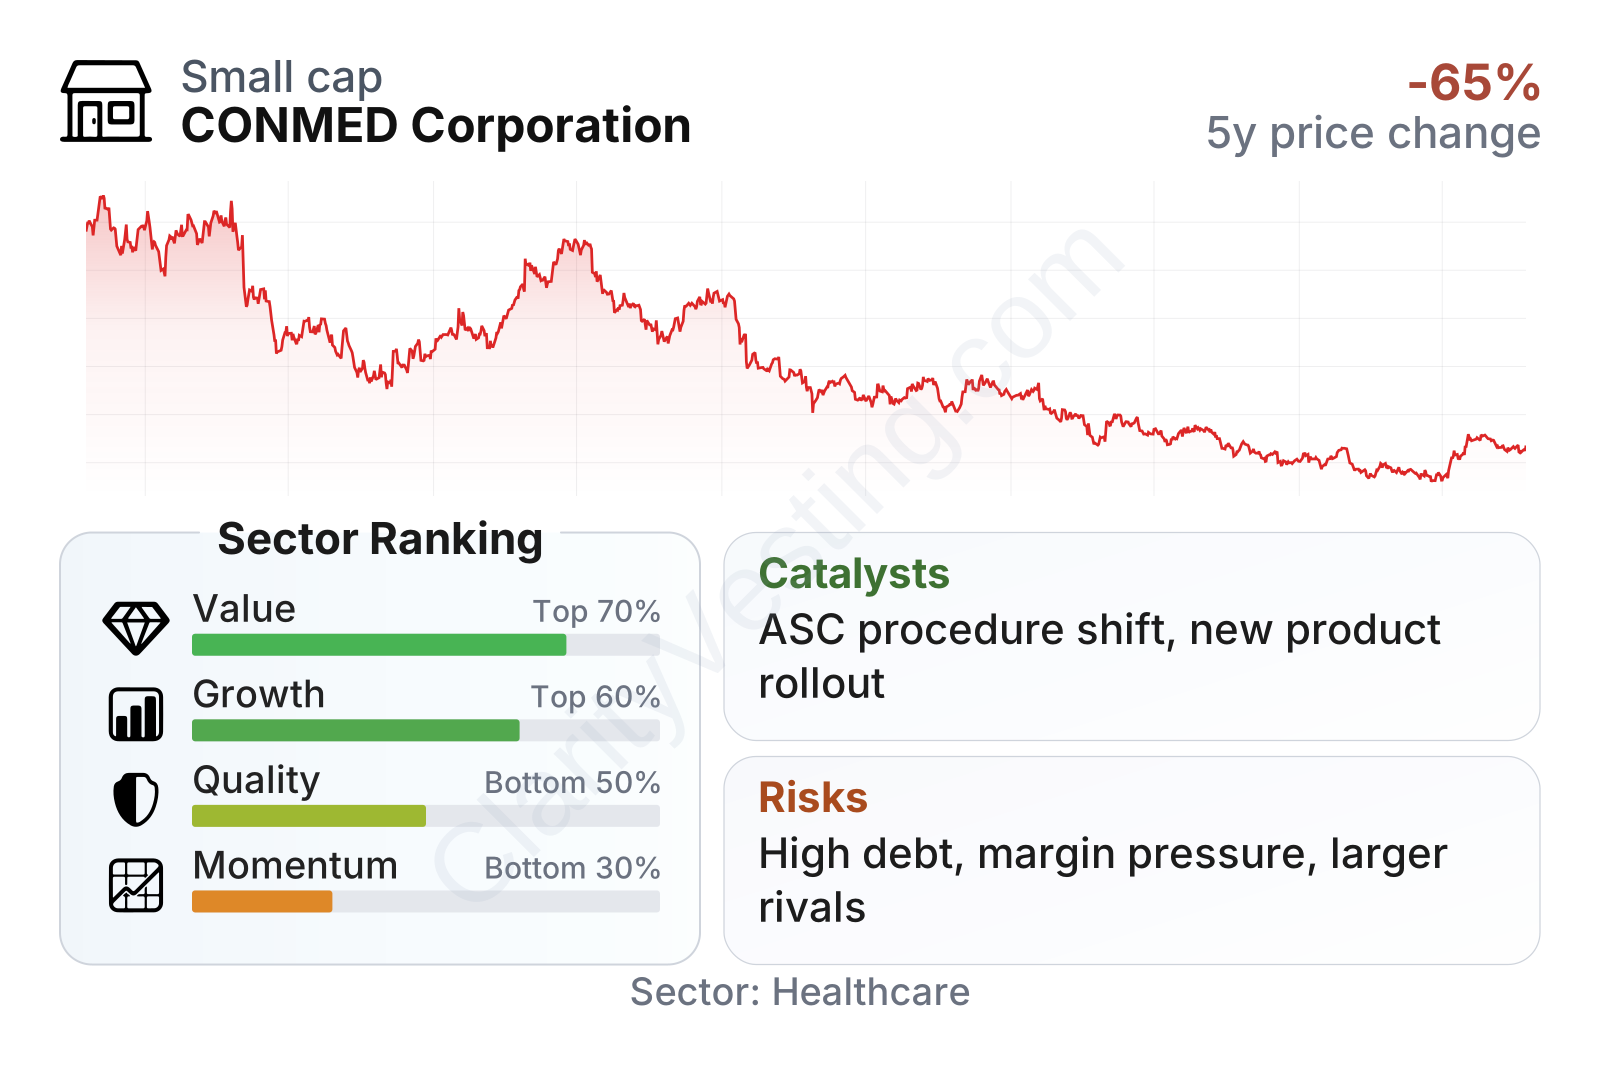
CONMED is a small-to-mid-sized medical device company with a stock that has been volatile over the last several years. In the latest factor view, valuation looks somewhat stronger than the sector on cash-flow-based measures, quality appears around the middle of the pack, growth is mixed, and market momentum remains weaker over multi-year periods despite a better recent rebound.
Several underlying metrics stand out. Free cash flow yield is well above the sector median, and price-to-book is below the sector median, which suggests the market is not assigning a premium multiple to the balance sheet. On the other hand, earnings-based valuation is closer to the sector norm, and leverage remains clearly elevated compared with many healthcare peers.
Growth
The company operates in the medical devices industry, which is generally supported by favorable long-term drivers: aging populations, rising procedure volumes, broader use of minimally invasive techniques, and continued migration of surgeries toward ambulatory surgery centers. These trends do not guarantee smooth quarterly performance, but they do support demand over long periods.
CONMED’s strategy is centered on specialty surgical categories where surgeon preference, product familiarity, and operating-room workflow can matter a lot. That approach makes strategic sense because it can support repeat usage, cross-selling, and recurring disposable revenue. The company has also emphasized product innovation and commercial execution in orthopedics and general surgery, where new systems and consumables can expand wallet share in existing hospital accounts.
Growth has not been linear. After a very strong phase in 2023 and steady mid-single-digit expansion through much of 2024 and 2025, the most recent year-over-year revenue readings slowed to around flat. That does not erase the longer trend, but it does show that near-term demand and execution have lost momentum compared with the prior expansion period. Over a five-year view, revenue per share growth has still been slightly ahead of the sector median.
Cash generation remains an important supportive element. Free cash flow improved sharply from earlier low levels and remains solid on a trailing basis, even after coming down from a peak. That matters because medical device businesses often need sustained investment in sales infrastructure, product development, and compliance, and internally generated cash gives management more flexibility to fund those needs while also addressing debt.
A meaningful catalyst is the continued expansion of outpatient procedures. CONMED’s product lineup is exposed to areas where ambulatory surgery centers can benefit from efficient, reliable tools and disposable products. If procedure volumes continue shifting to lower-cost settings, the company has an opportunity to deepen relationships in those channels. Another catalyst is international expansion, where the company still has room to broaden distribution and penetration. Product launches and upgrades in sports medicine and general surgery can also support growth if they improve surgeon adoption or help win conversions from competitors.
Recent company updates have also pointed to ongoing portfolio development and commercial initiatives rather than one single transformative event. For a business of this size, execution on product rollout, sales-force productivity, and margin discipline may be more important than any one headline catalyst.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


