Stock Analysis · Cimpress NV (CMPR)
Overview
Cimpress N.V. is a mass-customization company best known for helping small businesses and consumers design and order printed and promotional products. Its brands include Vistaprint, PrintBrothers, The Print Group, National Pen, Drukwerkdeal, Pixartprinting, Exaprint, Depositphotos, and VistaCreate. In simple terms, Cimpress combines software, design tools, manufacturing, and logistics so customers can order items such as business cards, flyers, signage, apparel, packaging, and promotional gifts in small or medium quantities.
The company’s model is built around e-commerce and digitally enabled production. Customers place orders online, often with personalized designs, and Cimpress routes those jobs through its manufacturing and fulfillment network. This model is attractive because it can serve many small orders efficiently, which is harder for traditional printers to do at scale.
Based on Cimpress’ recent annual reporting, revenue is spread across several business units rather than one single brand. Approximate revenue mix is as follows:
- Vista: about 48% of revenue. This is the largest business and includes Vistaprint and related offerings for small businesses such as marketing materials, signage, logo-related products, websites, and digital design tools.
- PrintBrothers: about 17%. This group serves mainly European customers through localized online print brands.
- The Print Group: about 13%. This unit focuses on upload-and-print and trade-oriented print services in Europe.
- National Pen: about 11%. This business sells custom promotional products, especially pens and branded accessories for small businesses.
- All Other Businesses: about 11%. This includes smaller operations such as photo, design-content, and adjacent customization businesses.
Cimpress has gradually increased total revenue over the last several years, and the financial flow also shows a meaningful improvement from earlier losses to positive earnings and stronger operating income. Gross profit has expanded as revenue rose, although the business still carries sizable operating and interest costs.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Industrials | |
| Industry | Specialty Business Services | |
| Market Cap ⓘ | $1.82B | |
| Beta ⓘ | 1.82 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 19.71 | 22.10 |
| P/B Ratio ⓘ | N/A | 1.97 |
| FCF Yield ⓘ | 9.18% | 6.38% |
| Dividend Yield ⓘ | N/A | 1.94% |
| EBIT / EV ⓘ | 7.52% | 4.79% |
| PEG ⓘ | 2.38 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 8.70% | 9.30% |
| RPS Growth (5Y CAGR) ⓘ | 7.46% | 7.81% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -13.06% |
| BVPS Growth (5Y CAGR) ⓘ | N/A | 6.14% |
| Margin Growth (5Y Trend) ⓘ | 3.16% | 0.88% |
| FCF Growth (5Y CAGR) ⓘ | 16.32% | 11.01% |
| DPS Growth (5Y CAGR) ⓘ | -66.55% | 9.48% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 14.76% | 10.84% |
| ROA (Latest) ⓘ | 4.60% | 5.41% |
| ROIC (5Y Median) ⓘ | 5.84% | 9.38% |
| ROA (5Y Median) ⓘ | 0.77% | 4.95% |
| Net Debt / EBIT (Latest) ⓘ | 5.76 | 2.08 |
| Net Debt / EBIT (5Y Median) ⓘ | 6.94 | 2.27 |
| Net Debt / EBITDA (Latest) ⓘ | 3.63 | 1.39 |
| Net Debt / Assets ⓘ | 67.67% | 19.28% |
| EBITDA / Interest ⓘ | 3.88 | 9.58 |
| Operating Margin (Latest) ⓘ | 6.92% | 10.50% |
| Operating Margin (5Y Median) ⓘ | 6.24% | 10.29% |
| Debt to Equity (Latest) ⓘ | -352.09% | 65.48% |
| Profit Margin (Latest) ⓘ | 2.57% | 6.67% |
| Free Cash Flow (Latest) ⓘ | $167.01M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +12.81% | +61.68% |
| 12M Return (excl. last month) ⓘ | +47.37% | +12.58% |
| 6M Return ⓘ | -8.76% | 0.00% |
| Price vs. 200-Day MA ⓘ | -12.77% | +0.02% |
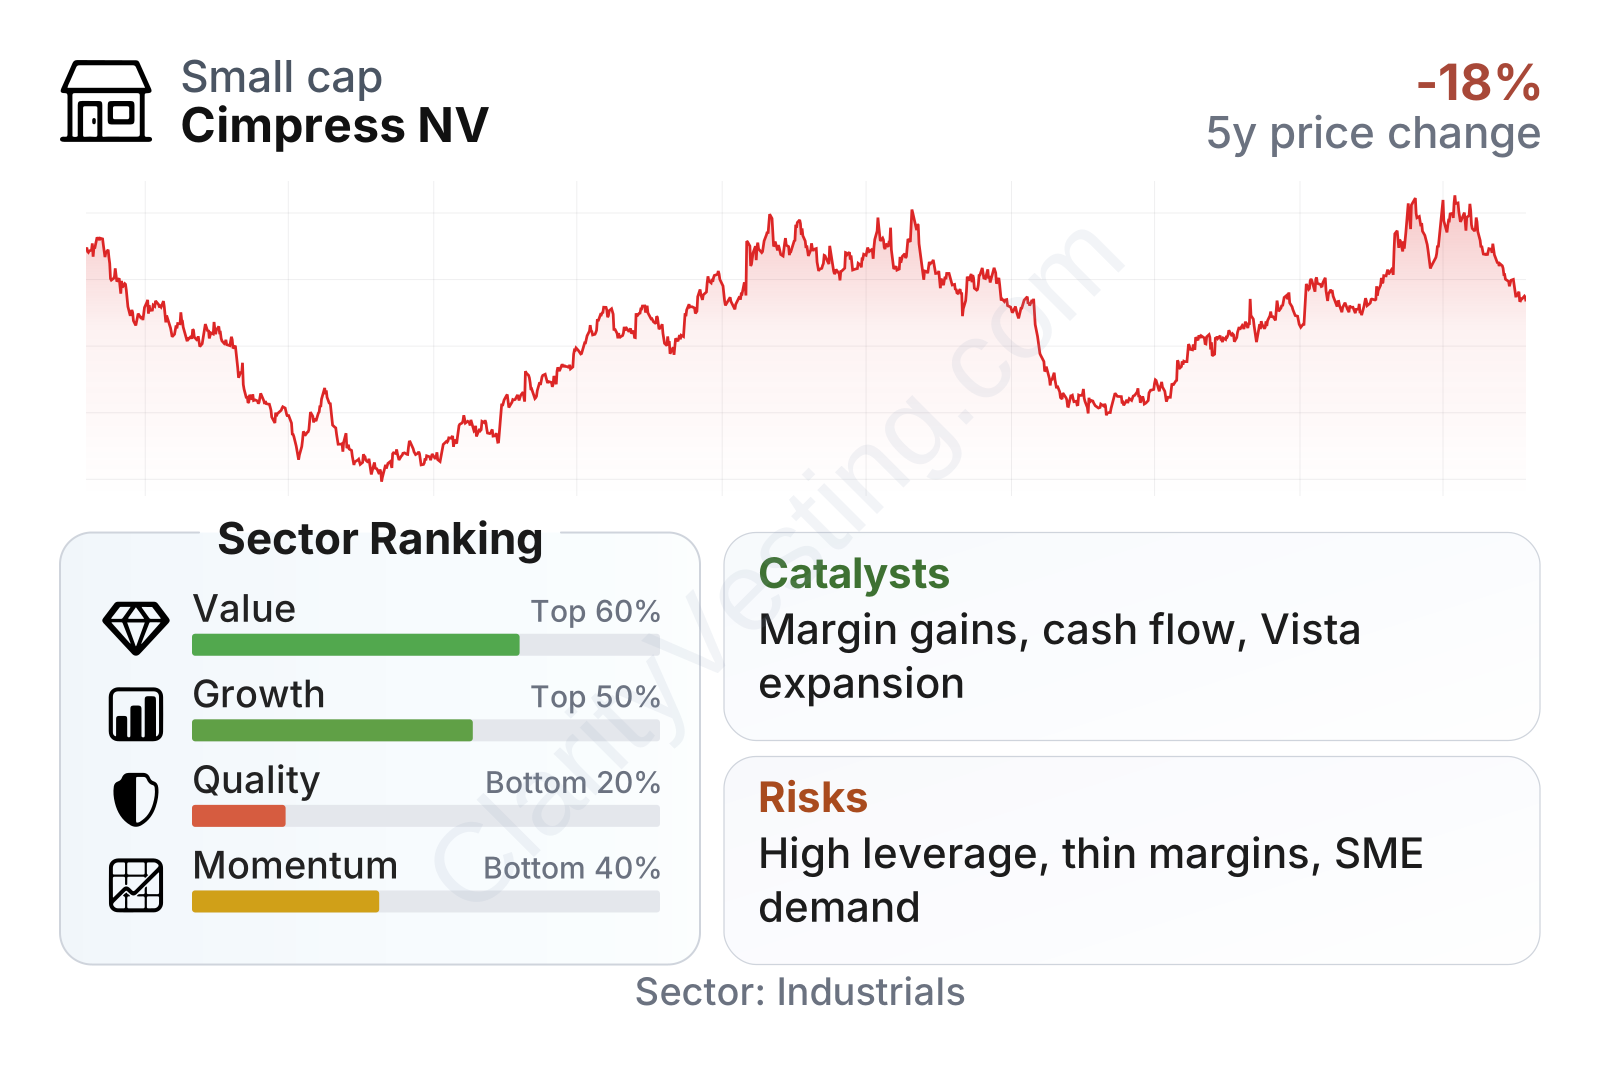
Cimpress is a mid-sized company with a stock that has been notably volatile, which matches its beta of roughly 1.8. The factor breakdown paints a mixed but interesting picture. On valuation and cash generation, the company screens better than many peers: free cash flow yield and EBIT relative to enterprise value are above sector medians. Growth is around the middle of the pack, with steady revenue expansion and a stronger long-term free cash flow trend than the sector median. The weak area is balance-sheet quality, where leverage remains elevated and profitability still trails many peers despite clear improvement from the low point in 2022 and 2023.
Growth
Cimpress operates in a sector that is mature in traditional printing but still has room to grow in digitally enabled, customized, small-batch production. That matters because demand is increasingly shifting away from large standardized print runs toward flexible, on-demand orders. Small businesses still need physical marketing materials, packaging, signage, and promotional items, but they increasingly expect easy online ordering, fast delivery, and integrated design tools. Cimpress is positioned around exactly that behavior.
The company’s strategy also makes sense for future growth. Management has spent years building a shared platform for manufacturing, procurement, software, and fulfillment while keeping customer-facing brands tailored to local markets and segments. This can support growth in two ways: it helps acquire customers through specialized brands, and it can improve economics behind the scenes by spreading technology and production capabilities across the portfolio.
Revenue growth has not been explosive, but it has been resilient. The recent pattern shows growth returning to the high-single-digit to low-double-digit range after a slower period in 2024 and early 2025. For a business of Cimpress’ size in a relatively mature industry, that suggests it is still taking share or expanding wallet share through product breadth, pricing, and better cross-selling.
Cash generation is one of the more encouraging parts of the profile. Free cash flow improved sharply from the levels seen a few years ago and has stayed around a solid level since then, even if it has recently flattened rather than continued rising. That matters because steady cash flow gives Cimpress more flexibility to invest in software, automation, marketing efficiency, and debt reduction.
A meaningful catalyst is the continued expansion of higher-value offerings around branding, design, apparel, packaging, and adjacent services for small businesses. Another is the use of artificial intelligence and automation in design creation, customer workflows, and production planning, which can make ordering easier and reduce service costs. Cimpress has also highlighted operational focus on margin improvement and capital discipline, which could be as important as revenue growth for long-term value creation.
Recent company updates have pointed to ongoing progress in profitability and cash flow discipline rather than a single headline event. For a company like Cimpress, that kind of operational execution may be more important than one-time news because the main opportunity is compounding improvement across a large customer base and manufacturing network.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


