Stock Analysis · CleanSpark Inc (CLSK)
Overview
CleanSpark Inc. is a Bitcoin mining company. In simple terms, it operates large computing facilities that help process and secure the Bitcoin network, and in return it earns Bitcoin block rewards and transaction fees. Over the last few years, the company has shifted away from its earlier energy software activities and is now primarily focused on running and expanding mining operations in the United States, with a strong footprint in Georgia, Mississippi, Tennessee, and Wyoming based on its recent company disclosures.
Its business model is fairly straightforward: build or acquire mining sites, install specialized machines, secure electricity at workable rates, and convert that infrastructure into Bitcoin production. Revenue therefore depends mainly on the amount of Bitcoin mined, the market price of Bitcoin, network difficulty, machine efficiency, and uptime across its sites.
The company’s revenue is now heavily concentrated in one activity. Based on recent annual reporting, the main sources of revenue are approximately:
- Bitcoin mining revenue: about 95% to 100% — this includes Bitcoin earned from self-mining operations and the accounting impact of digital asset activity tied to mining.
- Energy and other legacy operations: 0% to 5% — this reflects older software and energy-related activities that are no longer the main economic driver.
That concentration makes CleanSpark easy to understand, but it also means the company’s results are tightly linked to the economics of Bitcoin mining rather than to a diversified mix of businesses.
The longer-term picture shows a business that scaled revenue rapidly through expansion, while profitability swung sharply as the company moved from losses to a profitable period and then back to pressure more recently. That pattern is typical of a miner in a capital-intensive industry where earnings can change quickly with Bitcoin prices, network difficulty, and accounting revaluations.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Financial Services | |
| Industry | Capital Markets | |
| Market Cap ⓘ | $2.25B | |
| Beta ⓘ | 3.84 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | N/A | 12.46 |
| P/B Ratio ⓘ | 2.87 | 1.25 |
| FCF Yield ⓘ | -50.96% | 9.82% |
| Dividend Yield ⓘ | N/A | 2.94% |
| EBIT / EV ⓘ | -13.81% | 8.11% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | -30.50% | 9.10% |
| RPS Growth (5Y CAGR) ⓘ | 15.95% | 12.31% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -6.97% |
| BVPS Growth (5Y CAGR) ⓘ | -9.89% | 5.02% |
| Margin Growth (5Y Trend) ⓘ | N/A | -4.00% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 4.71% |
| DPS Growth (5Y CAGR) ⓘ | 53.89% | 8.92% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | -17.15% | 9.18% |
| ROE (Latest) ⓘ | -67.96% | 13.93% |
| ROA (Latest) ⓘ | -33.91% | 1.57% |
| ROIC (5Y Median) ⓘ | -8.33% | 7.80% |
| ROE (5Y Median) ⓘ | -13.54% | 12.15% |
| ROA (5Y Median) ⓘ | -12.84% | 1.28% |
| Net Debt / EBIT (Latest) ⓘ | N/A | 1.02 |
| Net Debt / EBIT (5Y Median) ⓘ | N/A | 0.72 |
| Net Debt / EBITDA (Latest) ⓘ | N/A | 0.88 |
| Operating Margin (Latest) ⓘ | -89.96% | 22.30% |
| Operating Margin (5Y Median) ⓘ | -29.66% | 24.50% |
| Debt to Equity (Latest) ⓘ | 234.13% | 59.34% |
| Profit Margin (Latest) ⓘ | -146.90% | 26.42% |
| Free Cash Flow (Latest) ⓘ | -$1.15B | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +91.54% | +95.73% |
| 12M Return (excl. last month) ⓘ | +10.19% | +17.30% |
| 6M Return ⓘ | -33.25% | +6.07% |
| Price vs. 200-Day MA ⓘ | -34.64% | +5.36% |
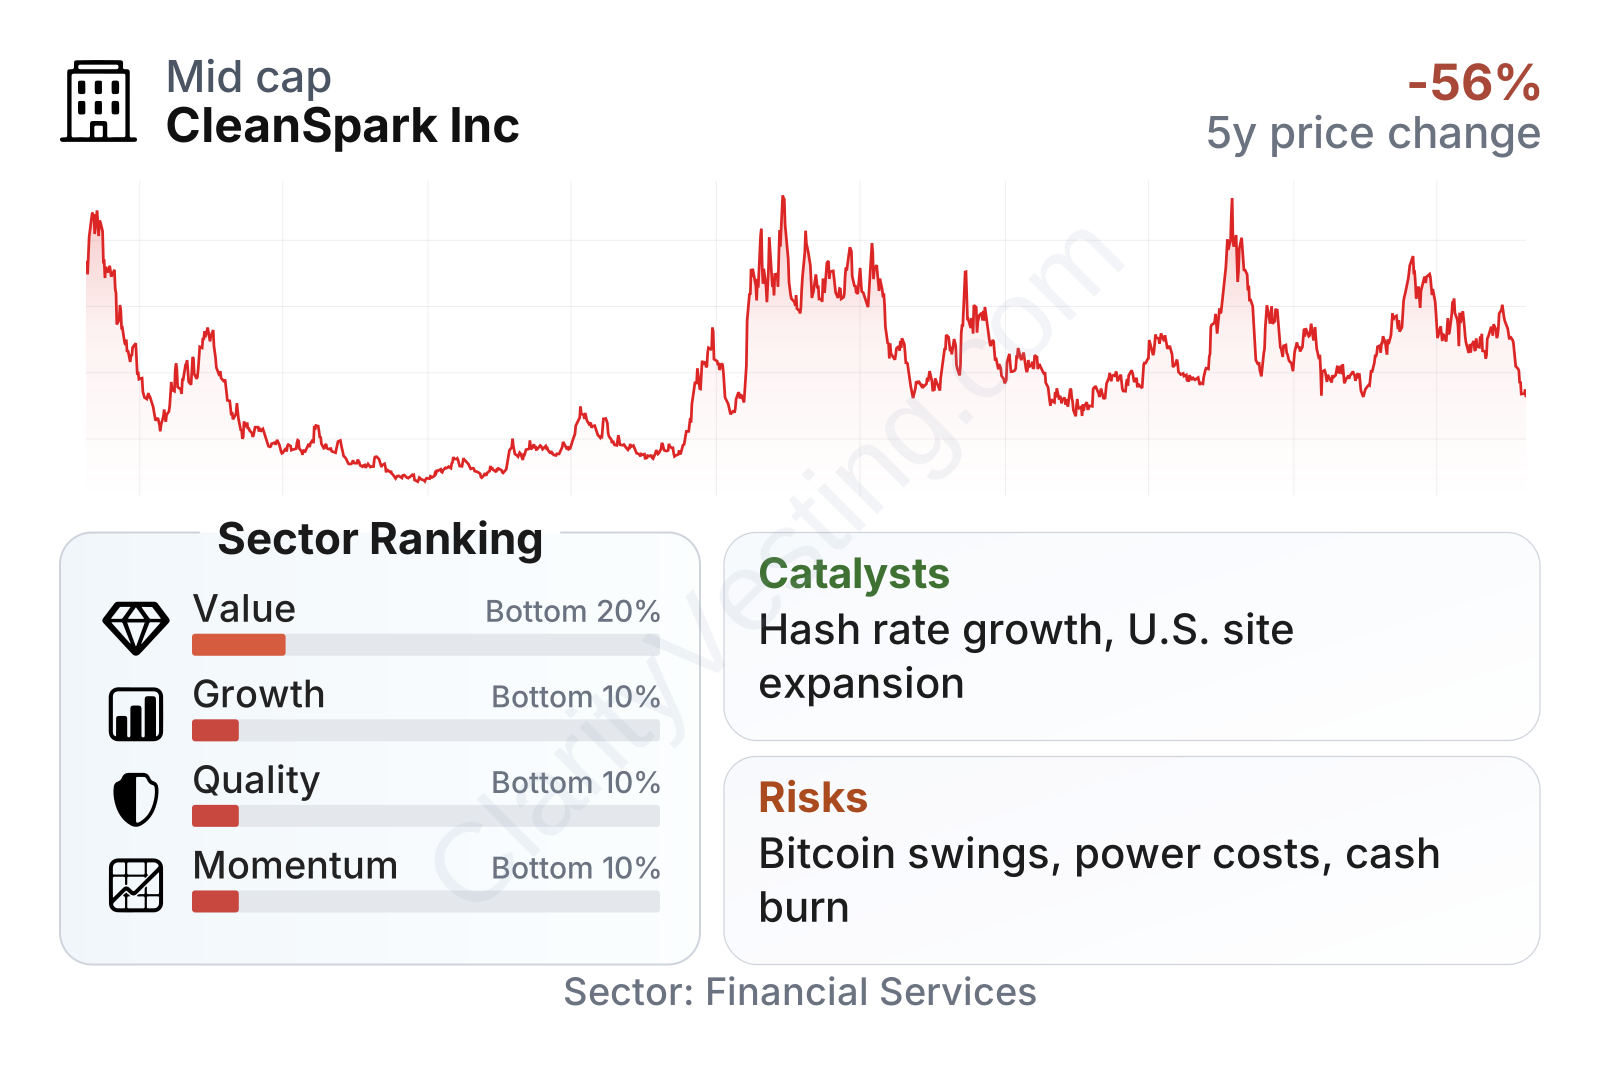
CleanSpark is now a mid-sized public company, but its market behavior remains unusually volatile, with a beta far above the broader market. The factor breakdown also points to a weak current fundamental profile relative to its sector: value, growth, and quality all rank near the bottom, while momentum is somewhat better. In practical terms, the stock has shown strong trading swings and decent recent price strength, but that market performance has not been matched by stable profitability, cash generation, or balance sheet quality.
The share price history reflects this clearly. The stock moved from low single digits in 2023 to much higher levels in 2024 and again in parts of 2025 before pulling back and rebounding. That kind of path can create large gains over some periods, but it also shows how strongly sentiment can shift around Bitcoin miners.
Growth
CleanSpark operates in a sector that still has meaningful long-term growth potential, but it is a specialized slice of the digital asset economy rather than a broad infrastructure utility. If Bitcoin adoption, institutional acceptance, and transaction activity continue to expand over time, efficient miners can benefit. The challenge is that the sector’s growth does not move in a straight line. It comes in cycles, often shaped by Bitcoin price moves, mining difficulty, and periodic halving events that reduce block rewards.
CleanSpark’s strategy has been logical for this industry. Management has focused on expanding hash rate, increasing site capacity, and pursuing domestic scale through acquisitions and infrastructure development. That approach can make sense because size matters in mining: larger operators can spread fixed costs, negotiate equipment and power arrangements more effectively, and maintain better operating flexibility than smaller peers.
Recent company updates have also highlighted expansion in operating capacity and fleet growth. Those are important catalysts because future production depends less on narrative and more on measurable inputs such as energized capacity, deployed miners, and average fleet efficiency. If the company continues executing on site buildouts and integration, it can increase its share of network production even in a more competitive post-halving environment.
Earnings illustrate both the opportunity and the instability. CleanSpark moved from losses in earlier years to positive earnings in 2024 and especially 2025, then slipped back into a large trailing loss by mid-2026. That does not automatically invalidate the growth case, but it shows that growth in this business is not the same as smooth earnings compounding. It is more dependent on timing, asset values, and mining economics.
Book value per share has also been uneven rather than steadily rising. For a capital-heavy miner, that matters because long-term value creation usually becomes more convincing when asset growth translates into durable per-share gains. So far, CleanSpark’s expansion has clearly increased operating scale, but the per-share balance sheet trend has been less consistent.
A notable opportunity is the continued consolidation of the U.S. mining industry. Smaller or financially weaker operators may struggle to fund new machines or secure power, while larger players with access to capital and operating experience can pick up assets, sites, or capacity. CleanSpark has been one of the more active consolidators in this space, which could remain a meaningful growth lever if acquisition discipline stays intact.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


