Stock Analysis · Colgate-Palmolive Company (CL)
Overview
Colgate-Palmolive is a global consumer products company focused on everyday household and personal care items. Its best-known businesses are oral care, personal care, home care, and pet nutrition. The company sells in more than 200 countries and territories, with a portfolio led by brands such as Colgate, Palmolive, Hill’s, Softsoap, Tom’s of Maine, Ajax, and Sanex. This is a classic consumer staples business: demand is usually steady because toothpaste, soap, dishwashing liquid, and pet food remain recurring purchases in most economic environments.
The company’s revenue base is fairly concentrated in a few large categories. Based on recent annual reporting, the main sources of revenue are approximately:
- Oral, Personal and Home Care: about 79% of sales. This includes toothpaste, toothbrushes, mouthwash, bar soap, liquid hand soap, body wash, shampoos, deodorants, dishwashing products, and household cleaners.
- Pet Nutrition: about 21% of sales. This is mainly Hill’s Science Diet and Hill’s Prescription Diet, sold through veterinarians, specialty retail, and e-commerce channels.
Within the larger Oral, Personal and Home Care segment, oral care is the company’s strongest category and an important profit engine. Colgate has long held a leading global toothpaste position, which gives the business scale in manufacturing, advertising, and shelf placement. Geographically, sales are widely diversified across North America, Latin America, Europe, Asia-Pacific, Africa, and Eurasia, which reduces reliance on any one market but also exposes results to currency swings.
Over the last several years, the business has shown a favorable pattern: revenue has risen from roughly $17 billion to above $20 billion, while gross profit expanded faster than cost of goods sold through pricing, mix, and productivity measures. However, operating costs jumped sharply in the latest annual flow, especially selling and administrative expenses, which helps explain why profit did not fully follow revenue higher.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Consumer Defensive | |
| Industry | Household & Personal Products | |
| Market Cap ⓘ | $71.73B | |
| Beta ⓘ | 0.32 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 35.43 | 17.88 |
| P/B Ratio ⓘ | 293.85 | 1.29 |
| FCF Yield ⓘ | 5.38% | 12.39% |
| Dividend Yield ⓘ | 2.37% | 2.85% |
| EBIT / EV ⓘ | 4.26% | 6.43% |
| PEG ⓘ | 1.57 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 4.90% | 4.10% |
| RPS Growth (5Y CAGR) ⓘ | 5.17% | 6.18% |
| EPS Growth (5Y CAGR) ⓘ | -10.50% | -13.59% |
| BVPS Growth (5Y CAGR) ⓘ | -44.82% | 3.20% |
| Margin Growth (5Y Trend) ⓘ | 2.40% | -0.15% |
| FCF Growth (5Y CAGR) ⓘ | 7.14% | 4.10% |
| DPS Growth (5Y CAGR) ⓘ | 3.23% | 6.79% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 27.49% | 12.34% |
| ROA (Latest) ⓘ | 11.88% | 6.30% |
| ROIC (5Y Median) ⓘ | 29.96% | 10.49% |
| ROA (5Y Median) ⓘ | 13.99% | 5.44% |
| Net Debt / EBIT (Latest) ⓘ | 2.03 | 1.96 |
| Net Debt / EBIT (5Y Median) ⓘ | 2.00 | 2.35 |
| Net Debt / EBITDA (Latest) ⓘ | 1.69 | 1.38 |
| Net Debt / Assets ⓘ | 38.64% | 21.51% |
| EBITDA / Interest ⓘ | 15.05 | 9.46 |
| Operating Margin (Latest) ⓘ | 15.19% | 8.87% |
| Operating Margin (5Y Median) ⓘ | 18.91% | 9.53% |
| Debt to Equity (Latest) ⓘ | 3329.24% | 72.35% |
| Profit Margin (Latest) ⓘ | 9.68% | 5.40% |
| Free Cash Flow (Latest) ⓘ | $3.86B | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +36.01% | +20.92% |
| 12M Return (excl. last month) ⓘ | +6.83% | +2.13% |
| 6M Return ⓘ | +8.39% | +1.26% |
| Price vs. 200-Day MA ⓘ | +2.00% | +1.39% |
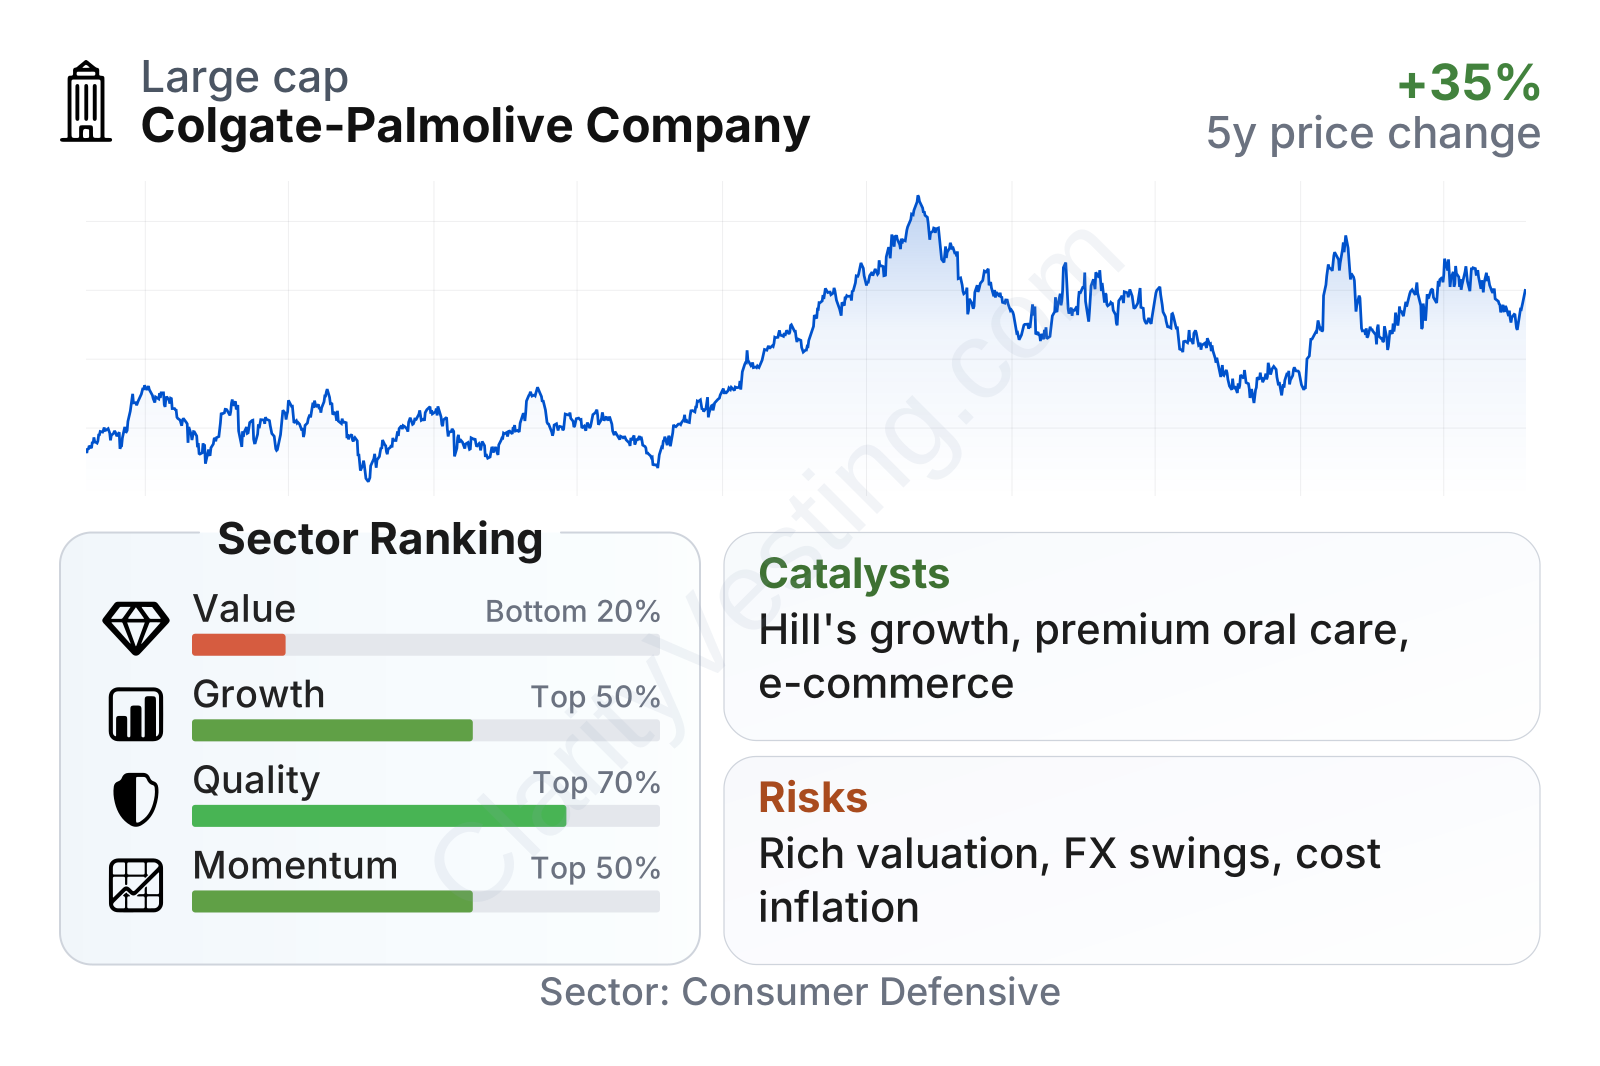
Colgate-Palmolive is a large, lower-volatility consumer staples company. The share price has advanced well over the past five years despite periods of inflation pressure and foreign exchange headwinds. In the current profile, quality metrics remain strong relative to much of the sector, growth looks respectable rather than exceptional, and valuation stands out as the weakest point. Profitability and returns on capital are clearly above many peers, while the stock trades at a premium multiple and offers a dividend yield slightly below the sector median.
Growth
Colgate-Palmolive operates in categories that are mature in developed markets but still capable of steady expansion globally. Oral care and basic hygiene products tend to grow with population, premiumization, and broader household spending, while pet nutrition benefits from long-running trends such as higher pet ownership, more spending per pet, and stronger interest in science-based nutrition. This means the company is not in a fast-disruption sector, but it is in one where durable brands can compound at moderate rates for long periods.
The company’s strategy for future growth is coherent. Management has emphasized pricing discipline, product innovation, premium offerings, and expansion in faster-growing channels such as e-commerce and professional or specialty distribution. Hill’s is particularly important here because pet nutrition usually carries attractive margins and has stronger structural growth than traditional household categories. Colgate also continues to invest in science-backed oral care, whitening, gum health, and therapeutic products, which can support better pricing than basic commodity-like items.
Recent sales growth has been uneven quarter to quarter, but the broader pattern is still constructive. Revenue growth accelerated strongly through 2023, slowed in parts of 2024 and 2025, and turned positive again more recently. The latest year-over-year pace is around the mid-single-digit range, slightly better than the sector median. That suggests the company is still finding ways to grow even after a period when many staples groups already pushed through substantial price increases.
Cash generation is another important support. Free cash flow has moved up meaningfully over the last few years and now sits near the upper end of its recent range. That matters because it gives the company flexibility to fund brand investment, dividends, debt service, and selective acquisitions without relying heavily on external financing. Recent company communications have also highlighted continued investment in innovation, digital commerce, and premium pet nutrition capacity, all of which can act as medium-term catalysts if execution remains solid.
A notable opportunity comes from Hill’s. Pet nutrition remains one of the most attractive corners of packaged consumer goods because it combines recurring demand with consumers’ willingness to pay for specialized products. If Hill’s continues gaining distribution and premium share, it can raise the group’s overall growth and margin profile. Emerging markets are another lever: Colgate’s oral care leadership gives it a platform to benefit from rising consumption in countries where branded penetration can still improve over time.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


