Stock Analysis · Chow Tai Fook Jewellery Group (CJEWY)
Overview
Chow Tai Fook Jewellery Group is a large jewelry retailer and brand operator focused mainly on Greater China, with additional presence in other Asian markets. The company designs, manufactures, and sells jewelry, gold products, platinum and karat gold pieces, gemstones, and watches. Its best-known business is mass-market and bridal jewelry sold through a very large store network under the Chow Tai Fook name and related brands.
The business is tied closely to consumer demand for gold jewelry and gifting. That makes it both a retail company and, to a meaningful extent, a precious-metals product company. Revenue can move not only with store traffic and unit sales, but also with changes in gold prices, product mix, and franchise expansion.
Based on the latest annual reporting and company disclosures, the main sources of revenue are approximately the following:
- Mainland China jewelry retail and franchise operations: roughly 85% to 90% of group revenue. This includes sales of gem-set jewelry, gold jewelry, fixed-price products, and franchise-related wholesale activity tied to the company’s extensive network.
- Hong Kong, Macau, and other markets: roughly 10% to 15% of revenue. This includes directly operated retail stores serving local demand and tourism, plus selected overseas markets.
- By product type, gold jewelry and gold products: typically the largest category, often around 75% to 85% of sales depending on the year and gold-price conditions.
- Gem-set, platinum, and karat gold jewelry: generally around 10% to 20% of sales, but usually a more important contributor to margin than to revenue share because branded and design-led products carry better profitability.
- Watches and other accessories: a small portion of revenue.
This mix matters because high-volume gold products support sales scale, while fixed-price and gem-set products usually matter more for margins and brand strength. In other words, the company’s long-term quality depends not just on selling more jewelry, but on improving the share of products that are less sensitive to raw gold prices and more driven by design, branding, and gifting demand.
The operating profile shows a business that remains highly profitable despite swings in revenue. The most recent year stands out for a strong rebound in operating income and net income, helped by a richer gross profit base. That suggests the group was not only selling more favorable products, but also extracting better earnings from each dollar of sales than in the prior year.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Consumer Cyclical | |
| Industry | Luxury Goods | |
| Market Cap ⓘ | $13.22B | |
| Beta ⓘ | 0.74 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 11.27 | 16.89 |
| P/B Ratio ⓘ | 0.49 | 1.61 |
| FCF Yield ⓘ | 74.67% | 8.99% |
| Dividend Yield ⓘ | 6.55% | 2.73% |
| EBIT / EV ⓘ | N/A | 6.69% |
| PEG ⓘ | 2.84 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 10.30% | 5.60% |
| RPS Growth (5Y CAGR) ⓘ | -1.77% | 8.91% |
| EPS Growth (5Y CAGR) ⓘ | 13.86% | -17.41% |
| BVPS Growth (5Y CAGR) ⓘ | -4.98% | 5.62% |
| Margin Growth (5Y Trend) ⓘ | 9.81% | -0.17% |
| FCF Growth (5Y CAGR) ⓘ | -56.94% | 4.91% |
| DPS Growth (5Y CAGR) ⓘ | 2.62% | 9.86% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 37.54% | 12.38% |
| ROA (Latest) ⓘ | 17.31% | 5.49% |
| ROIC (5Y Median) ⓘ | 13.26% | 10.75% |
| ROA (5Y Median) ⓘ | 7.38% | 5.44% |
| Net Debt / EBIT (Latest) ⓘ | 0.76 | 2.17 |
| Net Debt / EBIT (5Y Median) ⓘ | 1.30 | 2.30 |
| Net Debt / EBITDA (Latest) ⓘ | 0.66 | 1.50 |
| Net Debt / Assets ⓘ | 23.51% | 21.57% |
| EBITDA / Interest ⓘ | 23.98 | 9.13 |
| Operating Margin (Latest) ⓘ | 14.48% | 9.10% |
| Operating Margin (5Y Median) ⓘ | 9.42% | 9.56% |
| Debt to Equity (Latest) ⓘ | 97.44% | 75.99% |
| Profit Margin (Latest) ⓘ | 9.54% | 5.31% |
| Free Cash Flow (Latest) ⓘ | $9.87B | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +13.54% | +15.94% |
| 12M Return (excl. last month) ⓘ | -21.23% | -2.82% |
| 6M Return ⓘ | -3.83% | -1.58% |
| Price vs. 200-Day MA ⓘ | +3.66% | -3.31% |
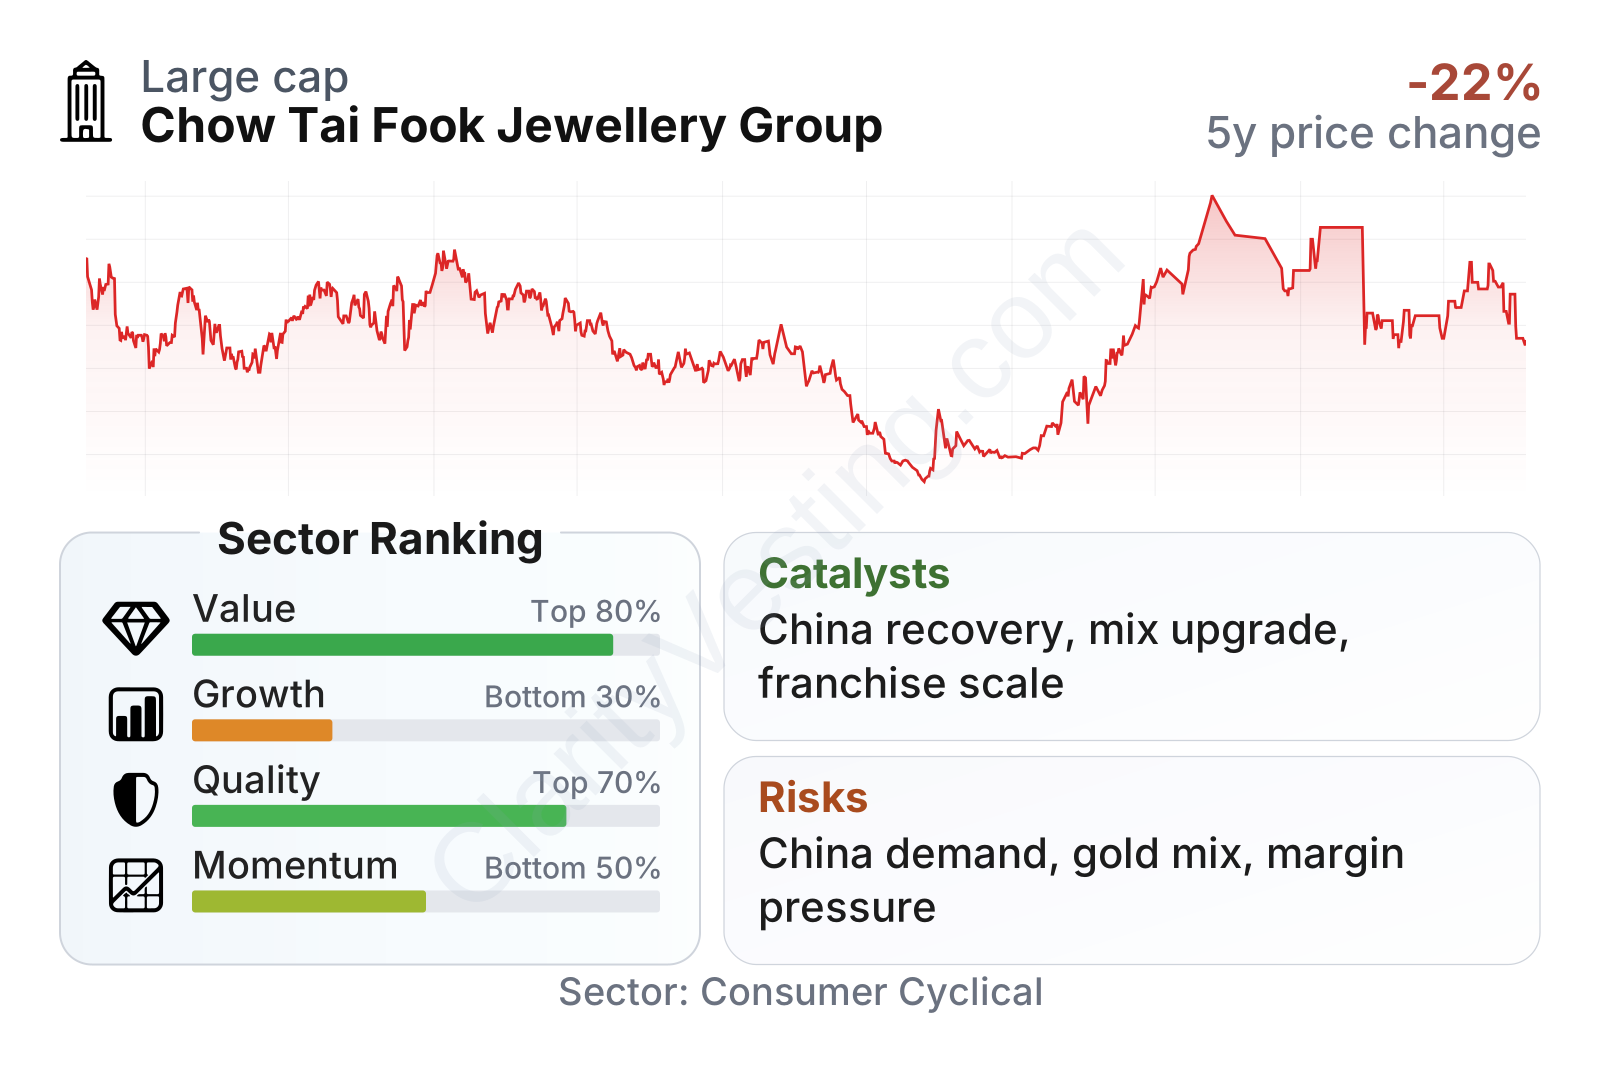
Chow Tai Fook currently screens as strong on valuation and solid on quality, while growth is less convincing over a longer horizon. The shares trade on earnings and book multiples below the sector median, and the cash generation profile is notably strong. Profitability is also better than many peers, with returns on capital and assets clearly above sector norms. The weaker point is consistency: recent revenue growth looks fine, but multi-year sales and free cash flow trends have been uneven, which explains the lower growth ranking despite healthy current margins.
The stock has also been volatile over the last few years. After a deep decline through 2024, it recovered sharply into 2025 and 2026, showing that market sentiment can change quickly when earnings improve. Even so, the share price path has not been smooth, which is typical for companies exposed to consumer confidence, tourism, and gold demand.
Growth
The company operates in a sector with attractive long-term characteristics but uneven short-term demand. Jewelry demand in Greater China benefits from cultural gifting, weddings, wealth preservation through gold, and rising interest in branded products. Over time, branded chains with scale, trust, and supply-chain control have tended to gain share from smaller independent jewelers, especially when consumers become more cautious and prefer established names.
Chow Tai Fook’s strategy broadly makes sense for that environment. Its scale gives it purchasing power, brand visibility, and a dense distribution network. It has also emphasized product upgrades, fixed-price gold collections, and store optimization. That matters because a pure dependence on weight-based gold sales can produce large revenue but weaker economics. A larger share of branded, design-led products can support healthier margins and improve resilience.
The most recent year-over-year revenue reading points to a soft near-term top-line trend, so growth is not currently linear. Still, that short-term weakness needs to be read alongside the much stronger profitability rebound in the latest fiscal year. In plain terms, the company appears to be focusing not only on sales volume but also on product mix and operating efficiency.
A meaningful catalyst is the company’s dominant position in Mainland China and its ability to keep expanding through franchising and store refinement rather than relying only on heavy capital spending. Another important driver is any recovery in discretionary spending and wedding-related demand in China and Hong Kong. Gold product demand can also rise during periods when consumers prefer tangible stores of value.
Recent company reporting for fiscal 2026 showed a strong rise in profit despite only moderate revenue recovery, which is a notable signal. It indicates that if consumer conditions improve further, earnings growth could move faster than sales growth because the business is already operating from a stronger margin base.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


