Stock Analysis · CIMC Enric Holdings Limited (CIMEF)
Overview
CIMC Enric Holdings Limited is a China-based equipment and engineering company focused on gases and energy-related infrastructure. It operates across natural gas, hydrogen, chemical, liquid food, and other cryogenic or pressurized storage and transport applications. In simple terms, the company builds the tanks, trailers, stations, processing systems, and integrated equipment used to store, move, and handle industrial gases and energy products.
The business sits at the intersection of traditional energy infrastructure and newer lower-carbon themes. That mix matters because it gives the company exposure to still-important natural gas investment while also positioning it for hydrogen and other cleaner-energy applications. CIMC Enric is part of the broader CIMC group, which adds industrial scale, manufacturing experience, and customer access.
Based on the company’s annual reporting structure, revenue mainly comes from three segments.
- Clean Energy: approximately 55% to 65% of revenue in recent years. This includes equipment and engineering services for natural gas, hydrogen, methanol, ammonia, LNG storage and transport, refueling stations, and related integrated solutions.
- Chemical & Environmental: approximately 20% to 30% of revenue. This segment includes tank containers, specialty storage and transport equipment, and products used in chemical logistics and environmental applications.
- Liquid Food: approximately 10% to 20% of revenue. This business provides stainless-steel processing, storage, and packaging-related equipment for industries such as beer, dairy, juice, and other liquid food applications.
This revenue mix gives the company a diversified industrial profile rather than dependence on a single end market. Over the last several years, total revenue has generally moved upward, but profitability has been less consistent. Sales rose from roughly 18.4 billion to 25.6 billion over 2021 to 2025, while operating income and net income stayed much flatter. That suggests the company has been winning business and expanding activity, but margin pressure and changing cost structure have limited how much of that growth has turned into earnings.
The long-term operating picture is therefore mixed but understandable: a larger business with broad industrial demand, yet one that still needs stronger margin conversion to fully translate scale into shareholder returns.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Energy | |
| Industry | Oil & Gas Equipment & Services | |
| Market Cap ⓘ | $1.86B | |
| Beta ⓘ | 0.78 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 11.24 | 15.44 |
| P/B Ratio ⓘ | 0.15 | 1.73 |
| FCF Yield ⓘ | 87.47% | 8.20% |
| Dividend Yield ⓘ | 30.02% | 3.59% |
| EBIT / EV ⓘ | N/A | 7.46% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 2.00% | 26.90% |
| RPS Growth (5Y CAGR) ⓘ | 8.20% | 6.90% |
| EPS Growth (5Y CAGR) ⓘ | -27.08% | -15.73% |
| BVPS Growth (5Y CAGR) ⓘ | 5.85% | 6.07% |
| Margin Growth (5Y Trend) ⓘ | -1.90% | 0.58% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 1.86% |
| DPS Growth (5Y CAGR) ⓘ | 23.16% | 16.79% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 11.40% |
| ROA (Latest) ⓘ | 6.07% | 6.06% |
| ROIC (5Y Median) ⓘ | 8.83% | 10.30% |
| ROA (5Y Median) ⓘ | 4.47% | 5.42% |
| Net Debt / EBIT (Latest) ⓘ | -2.00 | 1.64 |
| Net Debt / EBIT (5Y Median) ⓘ | -2.67 | 1.83 |
| Net Debt / EBITDA (Latest) ⓘ | -1.47 | 1.08 |
| Net Debt / Assets ⓘ | -13.96% | 17.29% |
| EBITDA / Interest ⓘ | N/A | 9.64 |
| Operating Margin (Latest) ⓘ | 5.05% | 16.27% |
| Operating Margin (5Y Median) ⓘ | 6.21% | 20.39% |
| Debt to Equity (Latest) ⓘ | 32.53% | 54.76% |
| Profit Margin (Latest) ⓘ | 4.10% | 8.82% |
| Free Cash Flow (Latest) ⓘ | $1.63B | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +11.58% | +67.38% |
| 12M Return (excl. last month) ⓘ | +16.98% | +49.19% |
| 6M Return ⓘ | -34.23% | +7.07% |
| Price vs. 200-Day MA ⓘ | -11.58% | +9.56% |
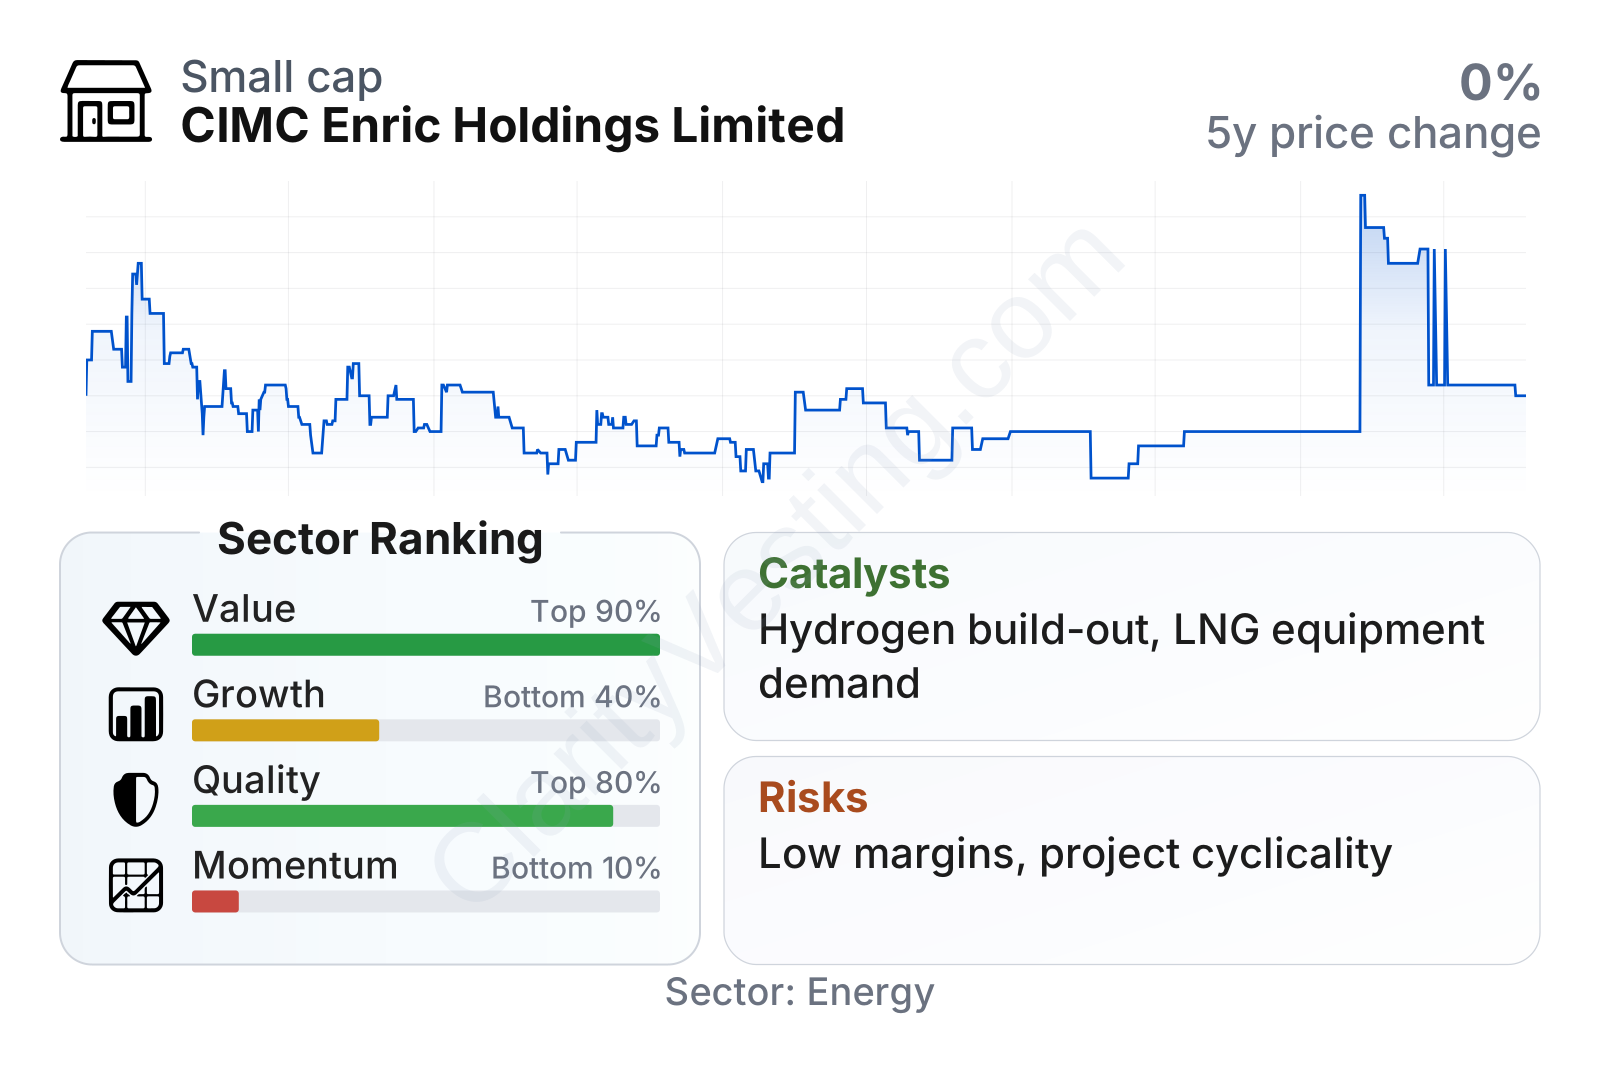
The current profile looks unusual in a good way on valuation and balance-sheet strength, but less impressive on near-term growth and share-price trend. Relative to the energy equipment peer group, the stock screens cheaply on earnings and especially on book value, while free-cash-flow yield and dividend yield stand out as very high. Quality is supported by a net cash position rather than net debt, which is a meaningful cushion in a cyclical industry. On the weaker side, recent revenue growth has been modest, profitability margins remain below sector medians, and market momentum has been soft, including a noticeable pullback over the last six months. The share price history also shows volatility, with a sharp rise earlier in 2026 followed by a retreat, which points to sentiment that can swing quickly.
Growth
CIMC Enric operates in sectors that still have room to expand over a multi-year horizon. Natural gas infrastructure continues to attract investment in many regions because LNG, storage, and transport systems remain important for energy security and fuel switching. At the same time, hydrogen, ammonia, and other cleaner-energy supply chains require specialized storage, transport, and fueling equipment, which directly matches the company’s engineering capabilities.
The strategic logic is fairly clear. The company is not relying on one narrow product line; it is using its cryogenic, high-pressure, and integrated-equipment expertise across multiple markets. That can be valuable because the same industrial know-how can serve LNG trailers, hydrogen stations, industrial gas systems, and process modules. For a long-term assessment, this kind of platform approach is more durable than a single-theme business.
One important catalyst is the company’s position in hydrogen and broader clean-energy infrastructure. If hydrogen deployment grows from pilot projects into larger commercial build-outs, demand for storage, transport, and refueling hardware could increase materially. Another support factor is the cleaner-energy transition within heavy industry and transport, where practical equipment providers may benefit earlier than more speculative technology developers.
Recent corporate updates have also pointed to ongoing project development, order activity, and continued emphasis on clean-energy applications. That does not guarantee fast earnings acceleration, but it does suggest the company is aligned with real industrial spending categories rather than purely conceptual future markets.
The main limitation is that recent top-line growth has slowed to low single digits year over year, which is much weaker than the broader sector median. So the growth case is more about medium-term optionality and business positioning than about a strong current acceleration in reported numbers.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


