Stock Analysis · China Mengniu Dairy Co Ltd (CIADY)
Overview
China Mengniu Dairy Co. Ltd. is one of China’s largest dairy producers. The company sells a wide range of milk and dairy products, including liquid milk, ice cream, milk formula, cheese, yogurt, and other dairy-based nutrition products. Its business is centered mainly in mainland China, where dairy consumption is tied to household spending, health awareness, and the modernization of food retail and cold-chain distribution.
Mengniu’s revenue mix has historically been led by liquid milk, while other categories such as ice cream, milk powder, cheese, and fermented dairy products add diversification. Based on company disclosures in recent annual reporting, the business can be summarized approximately as follows:
- Liquid milk: about 80% of revenue. This includes UHT milk, fresh milk, and flavored milk, and remains the company’s core category.
- Ice cream: about 6% to 8% of revenue. This is a branded consumer business with wide retail distribution.
- Milk formula: about 5% to 7% of revenue. This includes infant and adult nutrition products, a category with stricter regulation and heavier brand trust requirements.
- Cheese and other dairy products: about 5% to 7% of revenue. This includes cheese snacks, ingredients, and other adjacent dairy offerings.
The broad picture is that Mengniu is a scale consumer staples company with a strong presence in everyday dairy consumption. Over the last several years, revenue expanded through 2023, then turned weaker in 2024 and 2025, showing that size and brand strength did not fully protect it from softer demand and margin pressure. Even so, the business still generates substantial gross profit and cash flow, which helps explain why the market continues to view it as an important player rather than a structurally impaired one.
The operating profile shows a company that still converts a large sales base into meaningful gross profit, but with a much thinner profit layer after operating costs, interest, and taxes than it had a few years ago. That compression is one of the most important themes for long-term analysis.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Consumer Defensive | |
| Industry | Packaged Foods | |
| Market Cap ⓘ | $8.88B | |
| Beta ⓘ | 0.31 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 33.33 | 17.88 |
| P/B Ratio ⓘ | 0.22 | 1.29 |
| FCF Yield ⓘ | 144.35% | 12.39% |
| Dividend Yield ⓘ | 3.31% | 2.85% |
| EBIT / EV ⓘ | N/A | 6.43% |
| PEG ⓘ | 0.26 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 7.80% | 4.10% |
| RPS Growth (5Y CAGR) ⓘ | -2.02% | 6.18% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -13.59% |
| BVPS Growth (5Y CAGR) ⓘ | -1.69% | 3.20% |
| Margin Growth (5Y Trend) ⓘ | -2.38% | -0.15% |
| FCF Growth (5Y CAGR) ⓘ | 47.67% | 4.10% |
| DPS Growth (5Y CAGR) ⓘ | 17.21% | 6.79% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 12.34% |
| ROA (Latest) ⓘ | 1.50% | 6.30% |
| ROIC (5Y Median) ⓘ | 7.64% | 10.49% |
| ROA (5Y Median) ⓘ | 4.13% | 5.44% |
| Net Debt / EBIT (Latest) ⓘ | 1.78 | 1.96 |
| Net Debt / EBIT (5Y Median) ⓘ | 3.17 | 2.35 |
| Net Debt / EBITDA (Latest) ⓘ | 0.95 | 1.38 |
| Net Debt / Assets ⓘ | 13.16% | 21.51% |
| EBITDA / Interest ⓘ | 5.96 | 9.46 |
| Operating Margin (Latest) ⓘ | 4.42% | 8.87% |
| Operating Margin (5Y Median) ⓘ | 7.50% | 9.53% |
| Debt to Equity (Latest) ⓘ | 75.56% | 72.35% |
| Profit Margin (Latest) ⓘ | 2.19% | 5.40% |
| Free Cash Flow (Latest) ⓘ | $12.82B | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | -22.61% | +20.92% |
| 12M Return (excl. last month) ⓘ | +24.38% | +2.13% |
| 6M Return ⓘ | +9.73% | +1.26% |
| Price vs. 200-Day MA ⓘ | +8.15% | +1.39% |
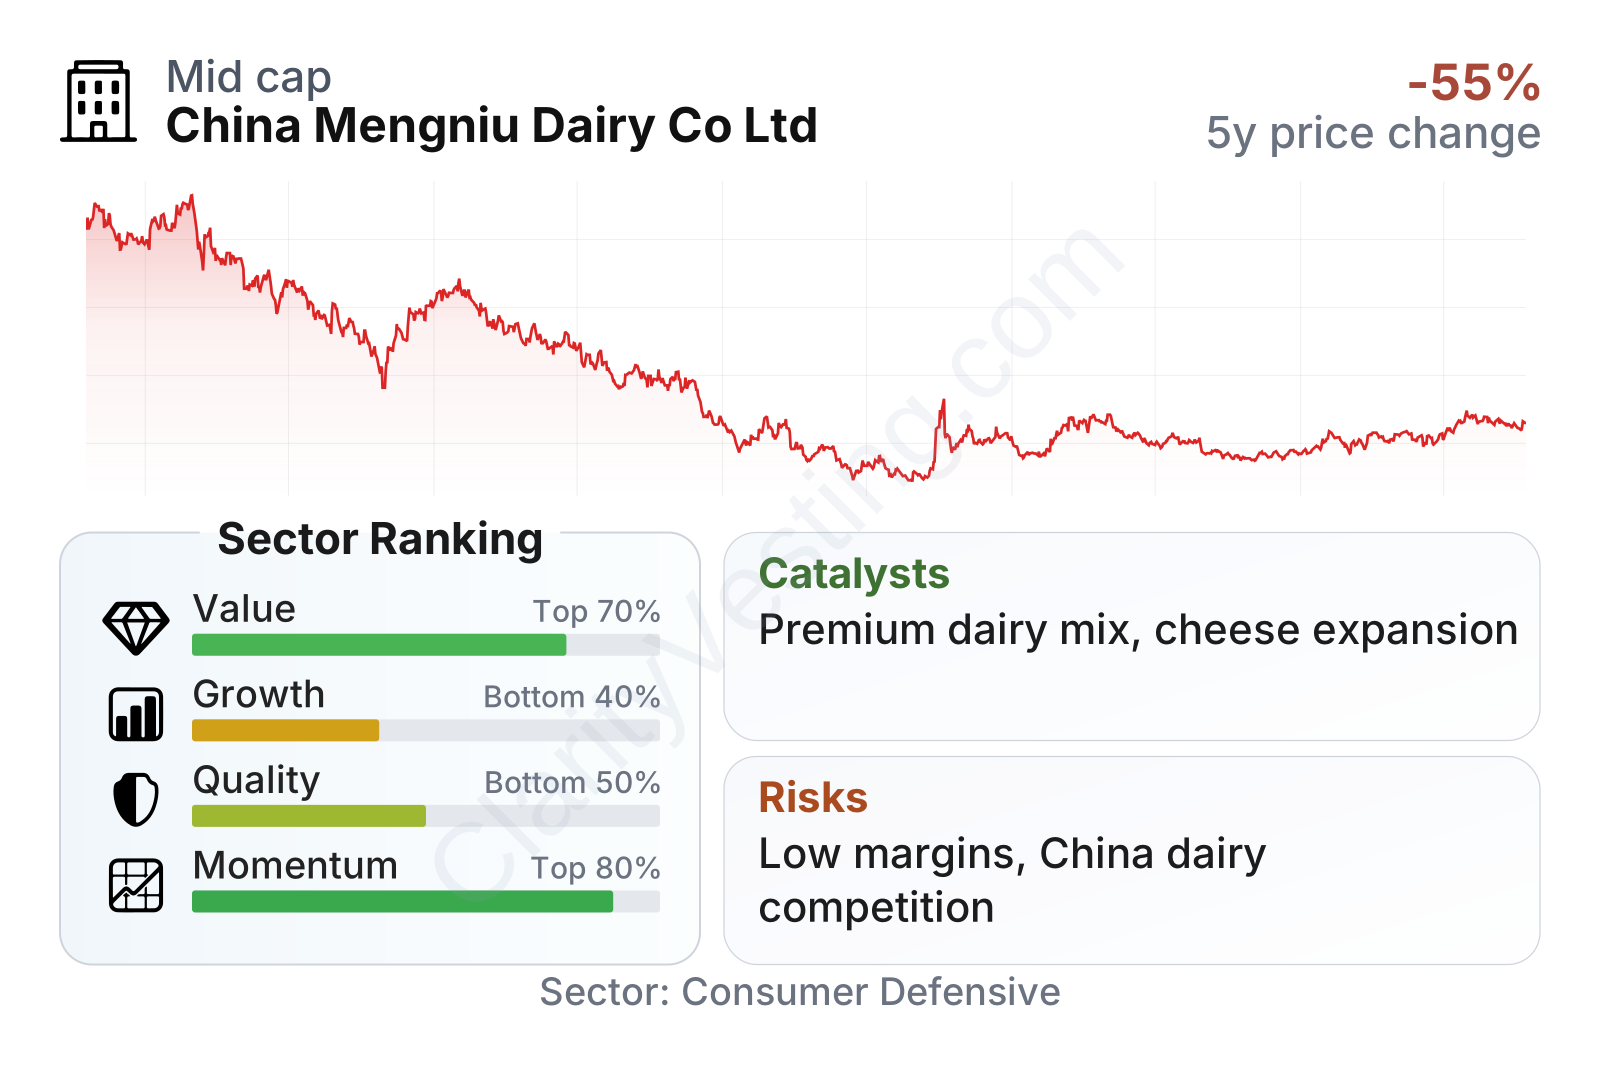
Mengniu is a large consumer defensive company with relatively low share-price volatility, as reflected by a beta well below 1. In factor terms, the picture is mixed. Value metrics look interesting in some areas, especially a very low price-to-book ratio and a free cash flow yield above the sector median, but the headline P/E appears elevated because earnings have been depressed. Growth and quality are less convincing: recent revenue growth has been better than the sector median, yet longer-term revenue per share and book value trends are weaker, while profitability and returns on assets remain below typical sector levels. Momentum has improved over the last year, suggesting sentiment has recovered somewhat from a long decline, but this is happening from a low base after several difficult years for the stock.
Growth
The dairy industry in China is still supported by long-term structural drivers: urbanization, cold-chain penetration, premiumization, convenience formats, and demand for higher-protein and nutrition-focused products. That said, it is not a simple straight-line growth market. Birth-rate weakness affects infant formula, competition is intense in mainstream milk, and consumer spending can shift quickly toward value products during softer economic periods.
Mengniu’s strategy broadly makes sense for future growth because it combines scale in mass-market dairy with exposure to premium and adjacent categories such as fresh milk, cheese, ice cream, and specialized nutrition. In theory, this reduces dependence on one product line and gives the company room to capture changing consumption habits. Cheese is especially relevant because per-capita cheese consumption in China remains low by global standards, leaving room for category development if consumer adoption continues.
A potential catalyst is margin recovery rather than pure sales acceleration. Input costs, product mix, and promotional intensity matter a great deal in dairy. If Mengniu can improve mix toward premium products while keeping costs under control, earnings can recover faster than revenue. Another supportive point is that free cash flow has held up much better than accounting profit, which suggests the business still has internal financial capacity even during a weaker earnings period.
Recent corporate developments have also reflected a focus on portfolio discipline, premium categories, and operating efficiency. For long-term observers, this matters because the company does not need explosive unit growth to improve its profile; it needs steadier execution, healthier margins, and better category balance. If consumer demand in China stabilizes, Mengniu has enough brand presence and distribution reach to participate meaningfully in any recovery.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


