Stock Analysis · China Hongqiao Group Limited (CHHQY)
Overview
China Hongqiao Group Limited is one of the world’s largest aluminum producers. The company operates across much of the aluminum value chain, from alumina and primary aluminum to fabricated aluminum products. In simple terms, it takes raw materials used in aluminum production, processes them at very large scale, and sells both basic aluminum metal and more value-added products to industrial customers.
Its business is closely tied to construction, transportation, power infrastructure, packaging, machinery, and increasingly lightweight manufacturing. Because aluminum is widely used in electric vehicles, solar frames, transmission systems, and industrial equipment, Hongqiao sits in a part of the materials sector that remains strategically important for manufacturing and electrification.
Based on the company’s annual reporting structure, revenue mainly comes from the following activities:
- Aluminum products: approximately 75% to 85% of revenue in recent years. This includes primary aluminum alloy, aluminum ingots and related processed aluminum products.
- Alumina products: approximately 10% to 20% of revenue. Alumina is the intermediate material used to produce primary aluminum.
- Other products and services: generally a small single-digit share of revenue, including steam supply and certain by-products or supporting industrial activities when disclosed separately.
The broad pattern is clear: Hongqiao is primarily an aluminum producer, with alumina serving as an important upstream business that supports both supply security and earnings diversification. That vertical integration matters because it can reduce reliance on outside suppliers and help protect margins when raw material markets become volatile.
Another important point is scale. Hongqiao is not a niche operator; it is a very large industrial producer with major assets in China and exposure to global aluminum pricing. That makes its results highly sensitive to metal prices, energy costs, and Chinese industrial demand, but it also gives the company purchasing power, operating efficiency, and relevance in a market where size can be a real advantage.
The long-term operating picture has improved meaningfully. Revenue has climbed from the low 100 billions in 2021 to the high 150 billions more recently, while operating income and net income rebounded strongly after a weaker 2022. What stands out most is that cost of revenue has grown far more slowly than sales since 2023, allowing profitability to expand sharply. That suggests a combination of stronger product pricing, improved product mix, and better cost absorption at scale.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Aluminum | |
| Market Cap ⓘ | $26.76B | |
| Beta ⓘ | 0.88 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 7.15 | 16.92 |
| P/B Ratio ⓘ | 0.19 | 1.66 |
| FCF Yield ⓘ | 197.99% | 5.83% |
| Dividend Yield ⓘ | 8.50% | 2.07% |
| EBIT / EV ⓘ | N/A | 6.38% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 8.00% | 11.25% |
| RPS Growth (5Y CAGR) ⓘ | 8.83% | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | -11.88% | -15.24% |
| BVPS Growth (5Y CAGR) ⓘ | 11.50% | 5.49% |
| Margin Growth (5Y Trend) ⓘ | 0.26% | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | 6.08% | 0.37% |
| DPS Growth (5Y CAGR) ⓘ | 11.57% | 5.91% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 9.59% |
| ROA (Latest) ⓘ | 19.52% | 4.92% |
| ROIC (5Y Median) ⓘ | 13.60% | 7.91% |
| ROA (5Y Median) ⓘ | 8.69% | 3.92% |
| Net Debt / EBIT (Latest) ⓘ | 0.14 | 1.36 |
| Net Debt / EBIT (5Y Median) ⓘ | 0.75 | 1.69 |
| Net Debt / EBITDA (Latest) ⓘ | 0.12 | 0.93 |
| Net Debt / Assets ⓘ | 3.87% | 13.69% |
| EBITDA / Interest ⓘ | 19.78 | 12.38 |
| Operating Margin (Latest) ⓘ | 23.56% | 13.24% |
| Operating Margin (5Y Median) ⓘ | 22.87% | 11.82% |
| Debt to Equity (Latest) ⓘ | 43.74% | 40.30% |
| Profit Margin (Latest) ⓘ | 16.28% | 6.38% |
| Free Cash Flow (Latest) ⓘ | $52.98B | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +249.94% | +73.47% |
| 12M Return (excl. last month) ⓘ | -3.10% | +27.59% |
| 6M Return ⓘ | -47.95% | -4.02% |
| Price vs. 200-Day MA ⓘ | -30.57% | -0.65% |
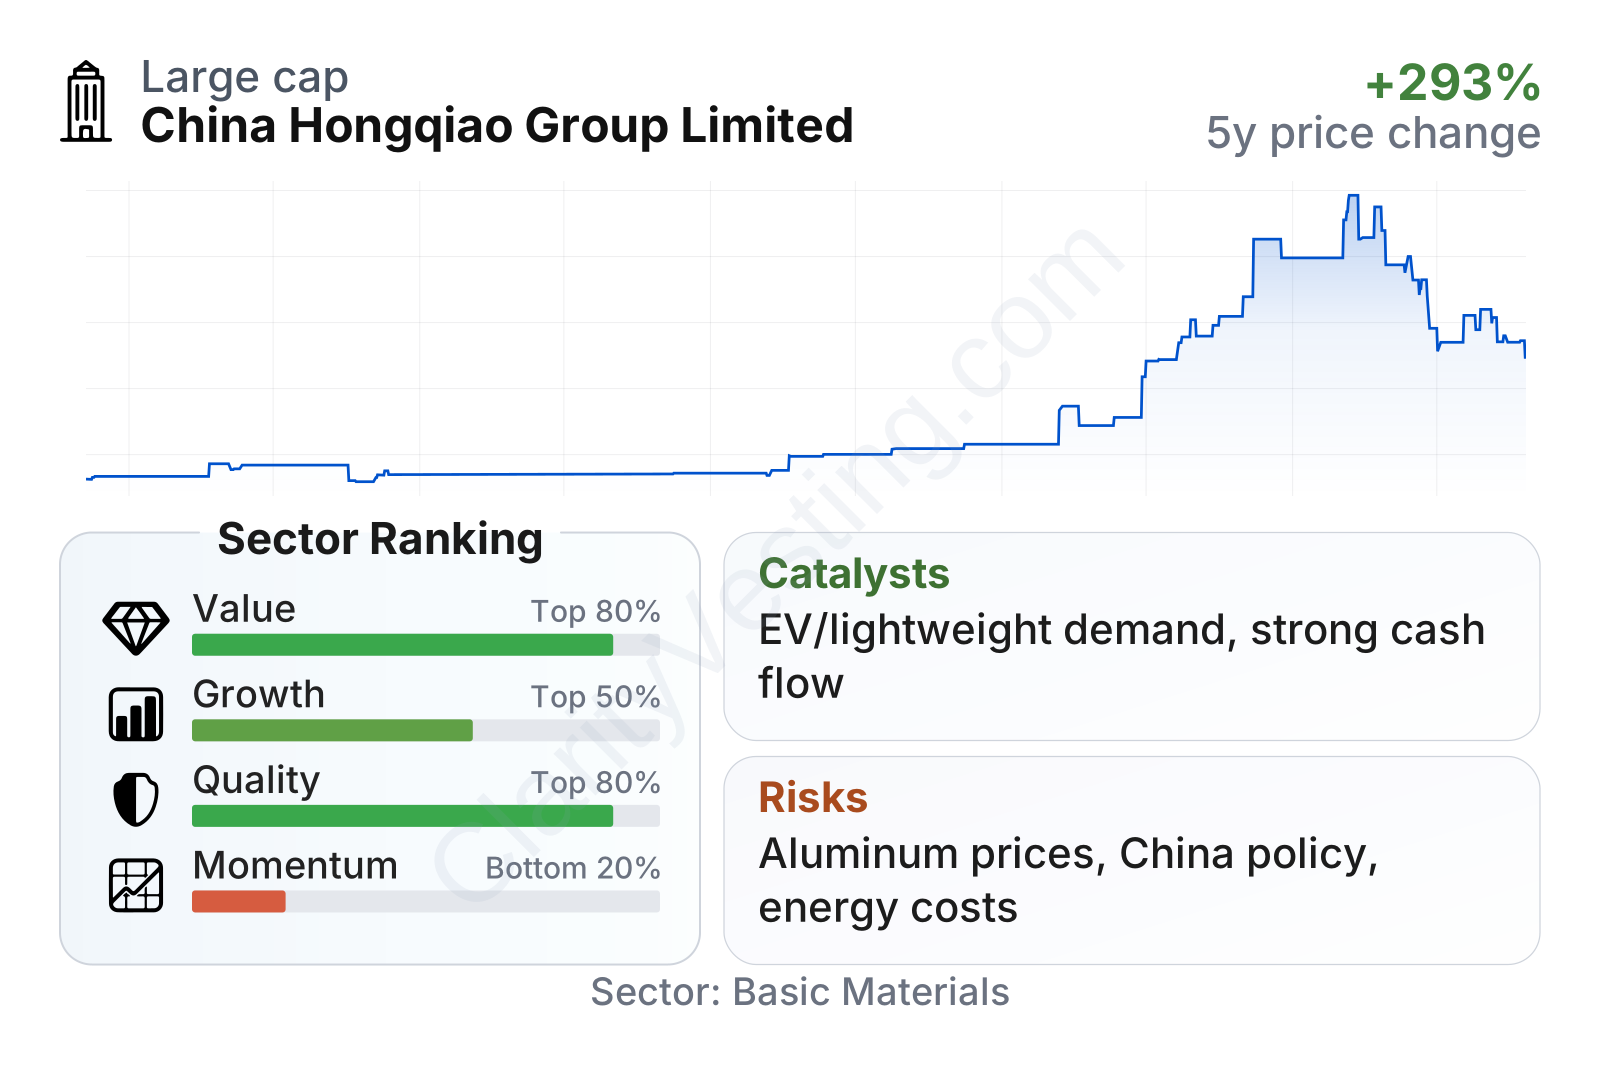
China Hongqiao combines a low valuation profile with solid profitability and a stronger-than-average balance sheet for its sector. The stock trades at a single-digit earnings multiple and a very low price-to-book ratio, while its free cash flow yield and dividend yield stand well above sector norms. At the same time, operating margin and profit margin are materially stronger than many basic materials peers, and net debt remains modest relative to earnings. The weaker point is recent share-price momentum: after a very strong multi-year rise, the stock has pulled back noticeably over the last several months and now trades below its longer-term trend line.
The company is also large enough to matter in global aluminum markets, yet its market sensitivity appears moderate rather than extreme, with beta below 1. That does not remove cyclical risk, but it suggests the stock has not been behaving like the most volatile names in the sector.
Growth
Hongqiao operates in a sector that has a credible long-term demand foundation. Aluminum is increasingly used wherever industries need lighter weight, corrosion resistance, conductivity, and recyclability. That includes electric vehicles, renewable power equipment, transmission infrastructure, consumer packaging, rail, and aircraft supply chains. Even when near-term demand fluctuates with the economy, the broader use cases for aluminum remain attractive.
The company’s strategy makes industrial sense because it combines scale, vertical integration, and cost control. In commodities, growth is not only about selling more volume; it is also about securing raw materials, keeping energy costs competitive, and maintaining margins through the cycle. Hongqiao’s presence in alumina and aluminum gives it more control over input risk than a stand-alone smelter would have.
Its five-year profile also looks better than a simple reading of annual commodity swings might suggest. Revenue per share growth, book value per share growth, free cash flow growth, and dividend growth have all outpaced sector medians. Earnings per share over five years have still been uneven, but that is common in cyclical materials businesses. More important is that margins have held up better than many peers, which hints at structural efficiency rather than a one-off windfall.
A notable catalyst is the industry’s push toward higher-value aluminum demand tied to electrification and lightweight transport. Another is China’s continued emphasis on advanced manufacturing and power-grid investment, both of which support aluminum consumption. If aluminum prices stay healthy while energy and raw material costs remain contained, Hongqiao has the scale to convert that into strong cash generation.
Recent operating trends also support that view. The company’s revenue advanced again in the latest full-year period, and profit levels stayed near multi-year highs after a major rebound in 2024. That matters because it suggests the earnings recovery was not immediately reversed. In addition, high free cash flow and a sizeable dividend indicate that recent profitability has translated into real cash rather than remaining only an accounting result.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


