Stock Analysis · COSCO SHIPPING International Co. Ltd (CHDGF)
Overview
COSCO SHIPPING International Co. Ltd is a Hong Kong-listed subsidiary within the wider COSCO SHIPPING group. Its business is not the same as a pure ocean freight carrier. Instead, it is mainly focused on services and products that support ships and shipping operations, especially marine fuel supply, coatings, equipment, spare parts, and related technical services. That makes it more of a shipping-support and maritime services company than a direct bet on container freight rates alone.
Based on the company’s recent annual reporting structure, revenue is mainly generated from the following activities:
- Marine fuel and related products: approximately 75% to 85% of revenue. This business generally includes the trading and supply of marine fuels and lubricant-related products to vessels.
- Coatings and coating services: approximately 10% to 20% of revenue. This typically covers marine and industrial coatings used for shipbuilding, maintenance, and repair.
- Marine equipment, spare parts, and technical services: approximately 5% to 10% of revenue. This area includes ship equipment trading, spare parts supply, and support services for vessel operations.
The revenue mix matters because the fuel supply operation tends to be large in sales but often thinner in margin, while coatings and specialized marine services can contribute more to profitability. That helps explain why earnings can behave differently from revenue in a given year.
Over the last few years, the company’s sales base has stayed in the low single-digit billions of Hong Kong dollars equivalent in reported terms, while profitability and cash generation have improved materially. The business model appears relatively asset-light compared with many shipping operators, and that is visible in its very low leverage and strong cash position.
The long-term pattern shows a business with fluctuating revenue but much stronger profit retention in recent years. Costs of revenue remain the dominant outflow, which is typical for fuel and trading activities, yet net income has risen faster than sales, suggesting that mix, cost control, and possibly non-operating contributions have supported results.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Industrials | |
| Industry | Aerospace & Defense | |
| Market Cap ⓘ | $1.17B | |
| Beta ⓘ | 0.62 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 11.41 | 22.10 |
| P/B Ratio ⓘ | 0.15 | 1.97 |
| FCF Yield ⓘ | 61.60% | 6.38% |
| Dividend Yield ⓘ | 65.08% | 1.94% |
| EBIT / EV ⓘ | N/A | 4.79% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 8.20% | 9.30% |
| RPS Growth (5Y CAGR) ⓘ | -3.85% | 7.81% |
| EPS Growth (5Y CAGR) ⓘ | -36.18% | -13.06% |
| BVPS Growth (5Y CAGR) ⓘ | -0.31% | 6.14% |
| Margin Growth (5Y Trend) ⓘ | -1.83% | 0.88% |
| FCF Growth (5Y CAGR) ⓘ | 108.28% | 11.01% |
| DPS Growth (5Y CAGR) ⓘ | 20.90% | 9.48% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 10.84% |
| ROA (Latest) ⓘ | 15.94% | 5.41% |
| ROIC (5Y Median) ⓘ | 2.74% | 9.38% |
| ROA (5Y Median) ⓘ | 6.44% | 4.95% |
| Net Debt / EBIT (Latest) ⓘ | -5.89 | 2.08 |
| Net Debt / EBIT (5Y Median) ⓘ | -7.29 | 2.27 |
| Net Debt / EBITDA (Latest) ⓘ | -5.48 | 1.39 |
| Net Debt / Assets ⓘ | -57.66% | 19.28% |
| EBITDA / Interest ⓘ | N/A | 9.58 |
| Operating Margin (Latest) ⓘ | 13.34% | 10.50% |
| Operating Margin (5Y Median) ⓘ | 5.53% | 10.29% |
| Debt to Equity (Latest) ⓘ | 0.28% | 65.48% |
| Profit Margin (Latest) ⓘ | 19.91% | 6.67% |
| Free Cash Flow (Latest) ⓘ | $721.54M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +179.86% | +61.68% |
| 12M Return (excl. last month) ⓘ | +24.85% | +12.58% |
| 6M Return ⓘ | +1.54% | 0.00% |
| Price vs. 200-Day MA ⓘ | +119.31% | +0.02% |
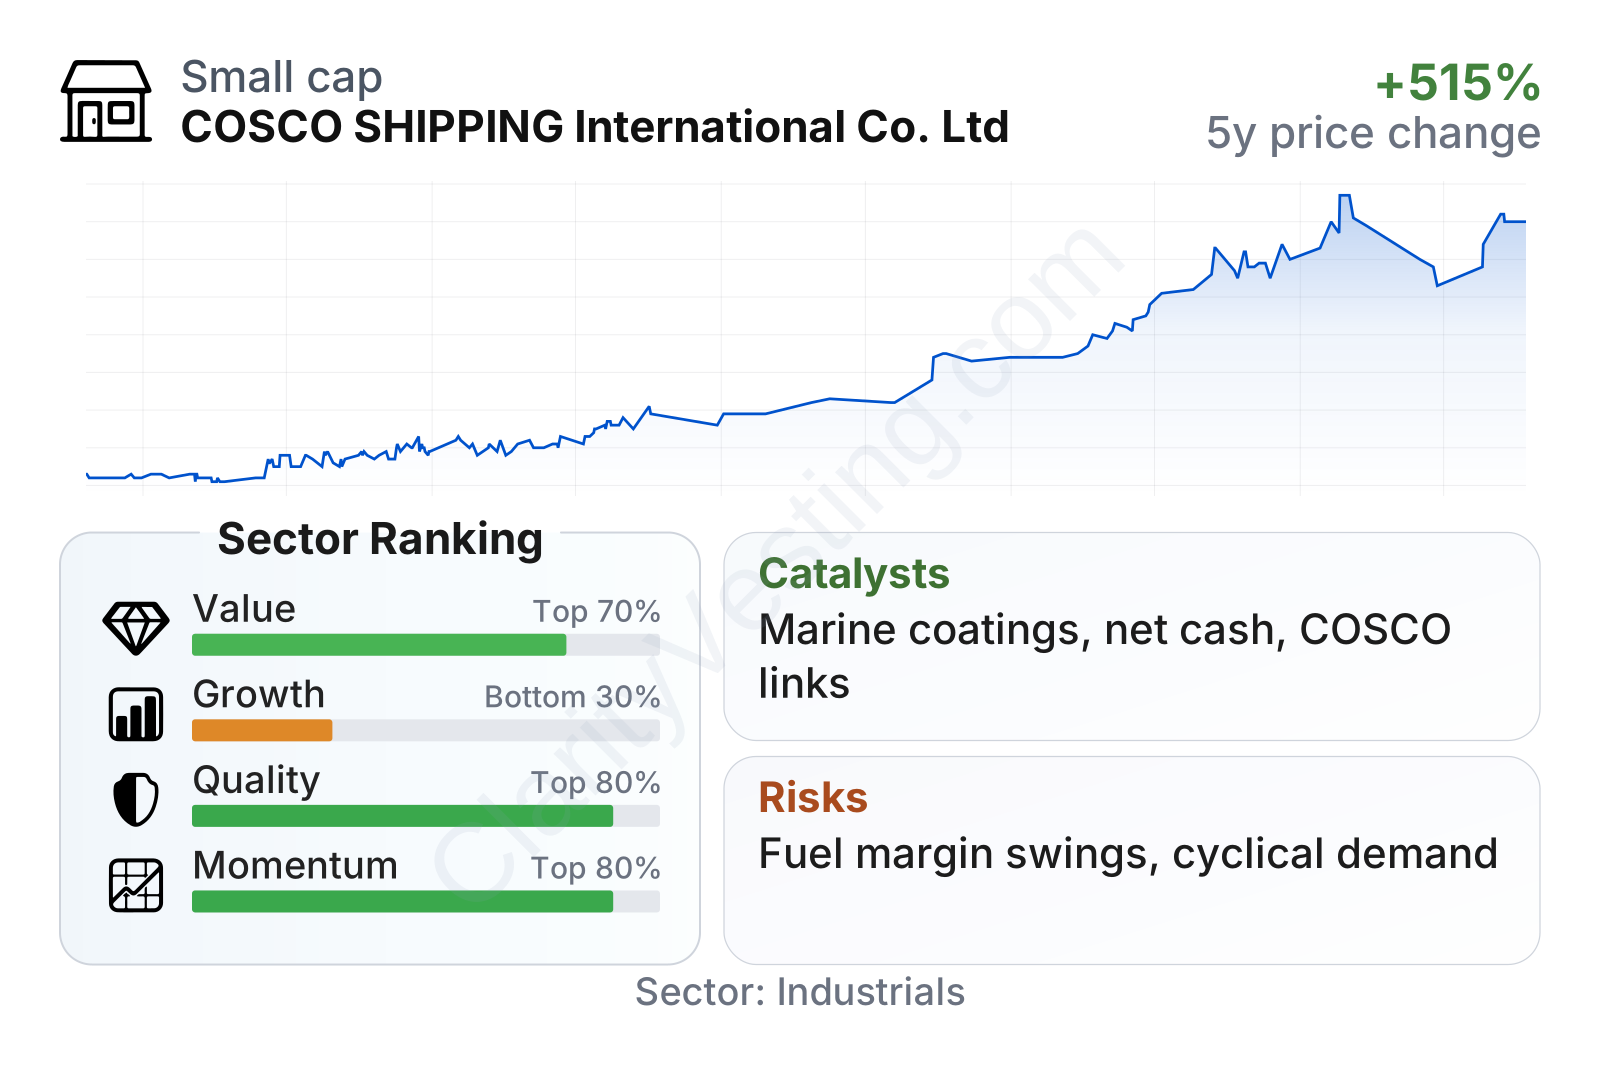
The overall profile is unusual in a positive way: valuation and balance-sheet metrics screen very strong, while growth metrics are much weaker. The company ranks well on quality, helped by a high recent return on assets, solid operating margin, and a net cash balance sheet rather than net debt. It also stands out on cash generation and dividend yield. The weaker area is long-term growth consistency, where revenue per share, earnings growth over five years, and book value growth trail the sector median. Recent share-price performance has been strong over three years, although shorter-term momentum has been more mixed.
The historical stock chart shows a major rerating from 2021 to late 2025. That kind of move usually reflects both stronger fundamentals and a market reassessment of earnings durability. Even after that rise, the company still screens as inexpensive on several standard measures relative to the broader industrials universe.
Growth
The company operates in a sector that has long-term support from global trade, fleet maintenance, environmental regulation, and the ongoing need for vessels to refuel, repair, and comply with stricter operating standards. Even when freight cycles weaken, ships still need coatings, consumables, spare parts, and technical support. That gives COSCO SHIPPING International exposure to recurring maritime activity rather than only freight-rate spikes.
Its strategy also fits several durable industry themes. Marine coatings can benefit from tighter efficiency and environmental requirements, as shipowners increasingly want solutions that reduce fuel consumption, corrosion, and maintenance downtime. Marine fuel supply remains essential, and any expansion into higher-value fuel services or cleaner-fuel support can help keep this business relevant as the shipping industry evolves. The group connection to COSCO SHIPPING is also important because it can provide customer access, procurement advantages, and credibility across the maritime ecosystem.
One notable positive feature is that recent profitability appears to have strengthened faster than revenue. Revenue growth in the latest period is modest rather than exceptional, but earnings, margins, and free cash flow are much stronger than the longer-term averages. That can matter more than top-line growth if it reflects better business mix and tighter execution.
Another potential catalyst is the company’s financial position. With net cash, minimal balance-sheet strain, and strong cash generation, it has flexibility for dividends, expansion, partnerships, or bolt-on acquisitions in specialized marine services. In a fragmented shipping-services market, balance-sheet strength can create opportunities when weaker players struggle.
Recent company reporting also points to continued emphasis on marine environmental protection, coatings, and shipping-related supply chain services. Those segments are aligned with practical needs in shipping rather than speculative themes, which can support steadier long-term demand.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


