Stock Analysis · CG Oncology Inc (CGON)
Overview
CG Oncology is a biotechnology company focused on bladder cancer. Its lead program is cretostimogene grenadenorepvec, an investigational oncolytic immunotherapy delivered directly into the bladder. The company is primarily targeting non-muscle invasive bladder cancer, a form of the disease that often returns and can be difficult to manage after standard treatment with Bacillus Calmette-Guérin, commonly called BCG.
This is still a development-stage business rather than a commercial pharmaceutical company. That distinction matters for long-term analysis: the company’s value today depends much more on clinical progress, regulatory milestones, and future launch potential than on current sales.
Recent filings show that revenue remains very limited and is not yet coming from broad product commercialization. The company’s revenue base appears to be made up mostly of collaboration-related or other non-core items rather than recurring drug sales.
- Collaboration, licensing, and other operating revenue: approximately 100% of current revenue. This reflects the fact that CG Oncology does not yet have an approved product generating meaningful commercial sales.
- Product revenue: 0% at this stage, based on currently available filings and the absence of a marketed therapy.
The financial structure reflects a classic biotech profile: very small revenue, heavy research and development spending, and rising operating losses as the lead asset advances through late-stage development. Expenses are concentrated in clinical trials, manufacturing preparation, regulatory work, and the buildout needed to support a possible launch.
The overall pattern is clear: spending has expanded sharply over the last several years while revenue has remained minimal. Research and development is the dominant use of cash, which is typical for a company trying to move a lead cancer therapy toward approval.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Healthcare | |
| Industry | Biotechnology | |
| Market Cap ⓘ | $5.52B | |
| Beta ⓘ | 0.28 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | N/A | 25.42 |
| P/B Ratio ⓘ | 5.36 | 3.08 |
| FCF Yield ⓘ | -3.25% | 3.12% |
| Dividend Yield ⓘ | N/A | 1.85% |
| EBIT / EV ⓘ | -4.09% | 0.56% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 1982.70% | 7.50% |
| RPS Growth (5Y CAGR) ⓘ | -23.85% | 8.60% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -17.73% |
| BVPS Growth (5Y CAGR) ⓘ | 100.37% | 3.72% |
| Margin Growth (5Y Trend) ⓘ | N/A | -0.57% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 0.96% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 6.69% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | -19.59% | 3.17% |
| ROA (Latest) ⓘ | -24.72% | 2.98% |
| ROIC (5Y Median) ⓘ | N/A | 4.56% |
| ROA (5Y Median) ⓘ | -24.42% | 1.87% |
| Net Debt / EBIT (Latest) ⓘ | N/A | 1.34 |
| Net Debt / EBIT (5Y Median) ⓘ | N/A | 1.86 |
| Net Debt / EBITDA (Latest) ⓘ | N/A | 1.00 |
| Net Debt / Assets ⓘ | -1.00% | 5.06% |
| EBITDA / Interest ⓘ | N/A | 9.55 |
| Operating Margin (Latest) ⓘ | -3602.68% | 9.25% |
| Operating Margin (5Y Median) ⓘ | -7729.50% | 7.33% |
| Debt to Equity (Latest) ⓘ | 0.86% | 26.68% |
| Profit Margin (Latest) ⓘ | N/A | 3.34% |
| Free Cash Flow (Latest) ⓘ | -$179.34M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | N/A | +51.61% |
| 12M Return (excl. last month) ⓘ | +109.88% | +19.90% |
| 6M Return ⓘ | -10.50% | +10.10% |
| Price vs. 200-Day MA ⓘ | -4.54% | +6.44% |
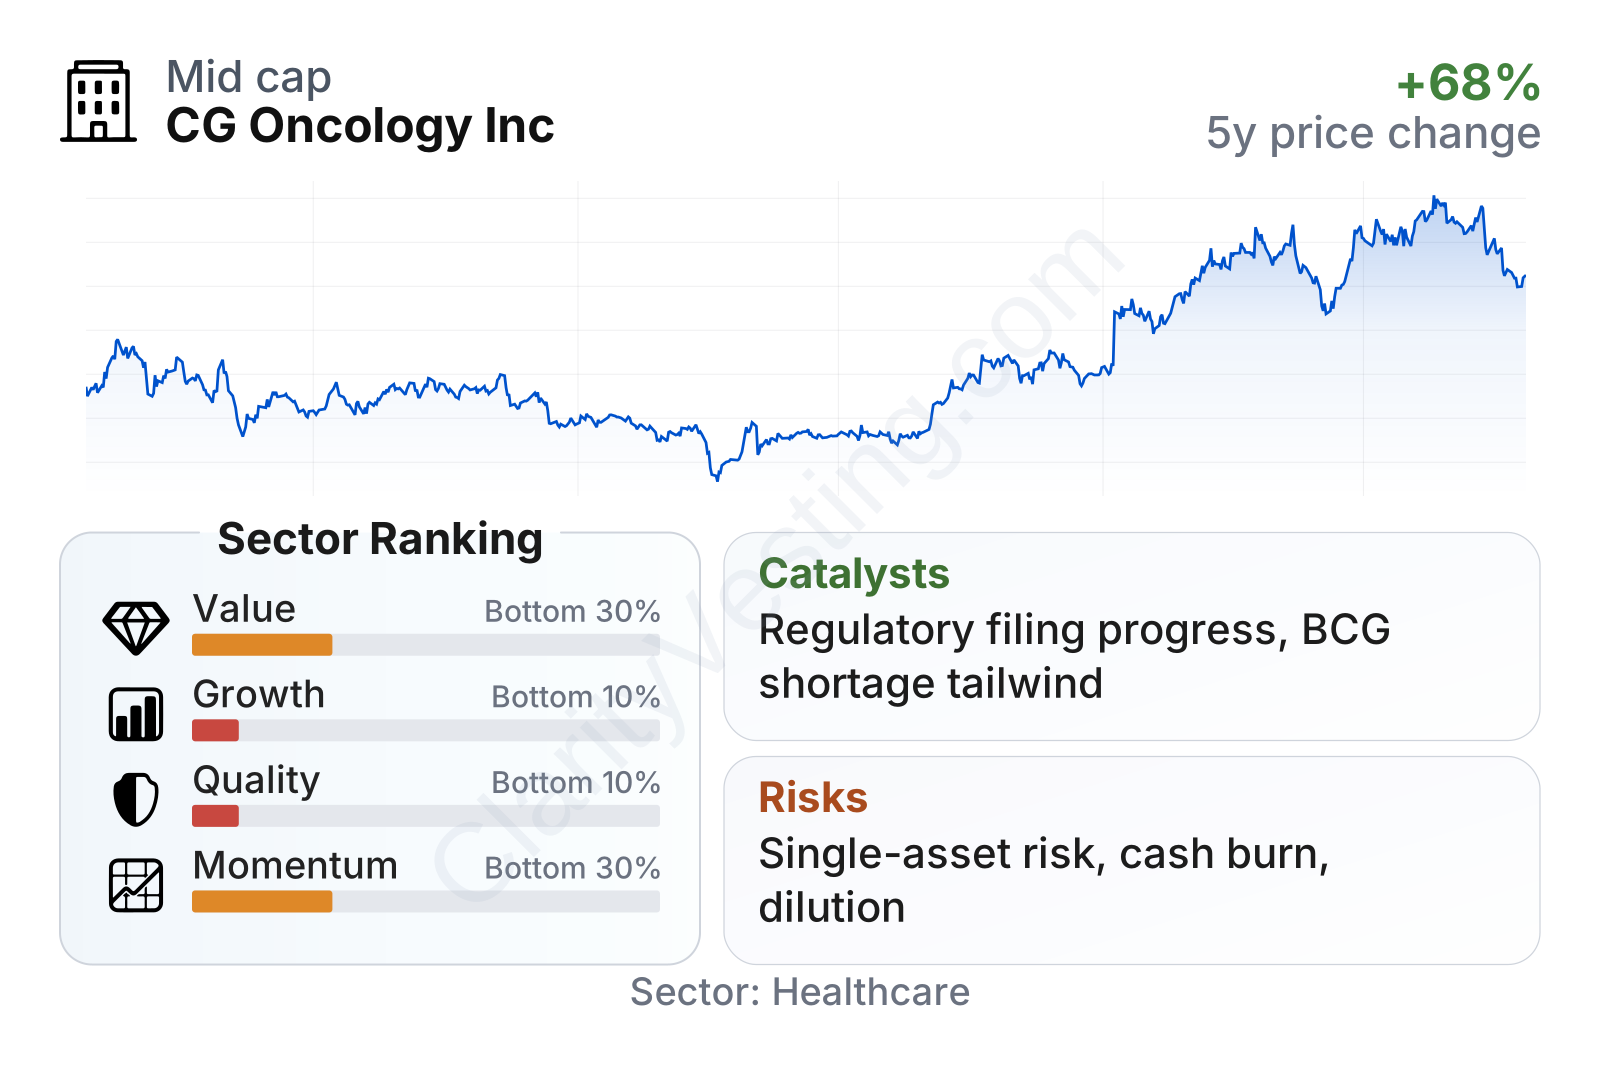
CG Oncology is now a mid-sized biotech by market value, and the stock has shown strong momentum over the past year. At the same time, the underlying financial profile remains weak by traditional operating standards. Relative to much of the healthcare sector, valuation measures look demanding, profitability is deeply negative, and free cash flow remains meaningfully below zero. The most favorable areas are balance-sheet conservatism, with very low leverage, and market performance, which suggests rising expectations tied to the pipeline.
Growth
The company operates in a healthcare niche with real unmet need. Non-muscle invasive bladder cancer is a large market, and patients whose disease returns after BCG treatment have limited bladder-preserving options. That gives CG Oncology exposure to a growing and medically important segment where successful new therapies can gain attention quickly.
The strategy is coherent for long-term growth. Instead of spreading resources across many unrelated programs, the company has concentrated on advancing its lead bladder cancer therapy through registrational development while also exploring broader use settings. If the treatment secures regulatory approval and demonstrates durable efficacy and safety, the business could shift from a research-stage model to a commercial oncology company with a more scalable revenue base.
One of the most important catalysts is the company’s progress toward regulatory submissions for cretostimogene. Public company updates during 2026 have emphasized late-stage clinical execution, expansion of supporting data, and commercial-readiness planning. For a company at this stage, these milestones matter more than current income statement figures because they shape the probability, timing, and eventual size of future revenue.
Reported revenue growth rates look dramatic, but they are not the main indicator to watch here because the starting revenue base is still tiny and not driven by established product sales. In practical terms, the real growth question is whether CG Oncology can convert clinical momentum into approval and then into adoption by physicians.
Cash use has been moving higher, which is consistent with a company entering a more expensive phase of development and preparation. That is not unusual in biotech, but it means long-term upside depends on whether today’s spending creates a commercially viable franchise later.
A second positive industry backdrop is supply disruption in traditional BCG over recent years. That has kept attention on alternative bladder cancer treatments and may improve the commercial opening for new options that can demonstrate strong results. If CG Oncology reaches the market at the right time, that context could help adoption.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


