Stock Analysis · Centerra Gold Inc (CGAU)
Overview
Centerra Gold Inc. is a mid-sized gold mining company that produces gold and, to a smaller extent, copper. Its operating base is centered on the Mount Milligan mine in British Columbia, Canada, and the Öksüt mine in Türkiye. The company also owns the Molybdenum Business Unit in the United States, which processes and sells molybdenum products, and it has a pipeline of development and exploration assets including the Kemess project in British Columbia and the Goldfield District project in Nevada.
For long-term readers, the business is relatively straightforward: Centerra digs metals out of the ground, sells them into global commodity markets, and tries to expand reserves and mine life through exploration, project development, and operational improvements. Its results are heavily influenced by gold prices, production volumes, operating costs, and the timing of mine development spending.
Based on the company’s recent reporting, revenue is mainly generated from the following sources:
- Gold sales from Mount Milligan and Öksüt: approximately 85% to 90% of revenue. This is the core of the business and includes doré and concentrate sales tied primarily to gold production.
- Copper sales from Mount Milligan: approximately 10% to 15% of revenue. Copper is produced as a by-product at Mount Milligan and adds meaningful diversification.
- Molybdenum business: a small but recurring contribution, generally below 10% of revenue. This segment includes roasted molybdenum concentrates and related products.
The broad financial picture has improved meaningfully over the last few years. Revenue has risen from roughly $0.9 billion in 2021 to about $1.4 billion in 2025, while operating income and net income have recovered sharply after a weaker 2022-2023 period. That recovery reflects a mix of stronger production, better margins, and a more favorable gold price backdrop.
The longer-term trend shows a business that went through a difficult stretch and then regained profitability with much stronger operating earnings by 2024 and especially 2025. Costs have not disappeared as a challenge, but the earnings profile is clearly stronger than it was two to three years earlier.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Gold | |
| Market Cap ⓘ | $4.28B | |
| Beta ⓘ | 1.60 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 6.94 | 16.90 |
| P/B Ratio ⓘ | 1.96 | 1.65 |
| FCF Yield ⓘ | 2.16% | 5.76% |
| Dividend Yield ⓘ | 0.89% | 2.13% |
| EBIT / EV ⓘ | 22.12% | 6.30% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 53.50% | 11.10% |
| RPS Growth (5Y CAGR) ⓘ | 22.05% | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -13.47% |
| BVPS Growth (5Y CAGR) ⓘ | 9.80% | 5.51% |
| Margin Growth (5Y Trend) ⓘ | 8.06% | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | -26.39% | 0.37% |
| DPS Growth (5Y CAGR) ⓘ | 7.59% | 6.08% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 31.50% | 9.26% |
| ROA (Latest) ⓘ | 22.11% | 4.91% |
| ROIC (5Y Median) ⓘ | 4.86% | 7.70% |
| ROA (5Y Median) ⓘ | -3.19% | 3.86% |
| Net Debt / EBIT (Latest) ⓘ | -0.46 | 1.40 |
| Net Debt / EBIT (5Y Median) ⓘ | -2.87 | 1.70 |
| Net Debt / EBITDA (Latest) ⓘ | -0.40 | 0.95 |
| Net Debt / Assets ⓘ | -13.09% | 13.69% |
| EBITDA / Interest ⓘ | 60.01 | 12.34 |
| Operating Margin (Latest) ⓘ | 52.34% | 13.20% |
| Operating Margin (5Y Median) ⓘ | 14.42% | 11.80% |
| Debt to Equity (Latest) ⓘ | 2.11% | 40.56% |
| Profit Margin (Latest) ⓘ | 36.92% | 6.43% |
| Free Cash Flow (Latest) ⓘ | $92.32M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +369.97% | +68.89% |
| 12M Return (excl. last month) ⓘ | +138.35% | +30.21% |
| 6M Return ⓘ | +7.05% | -4.16% |
| Price vs. 200-Day MA ⓘ | +13.73% | -1.27% |
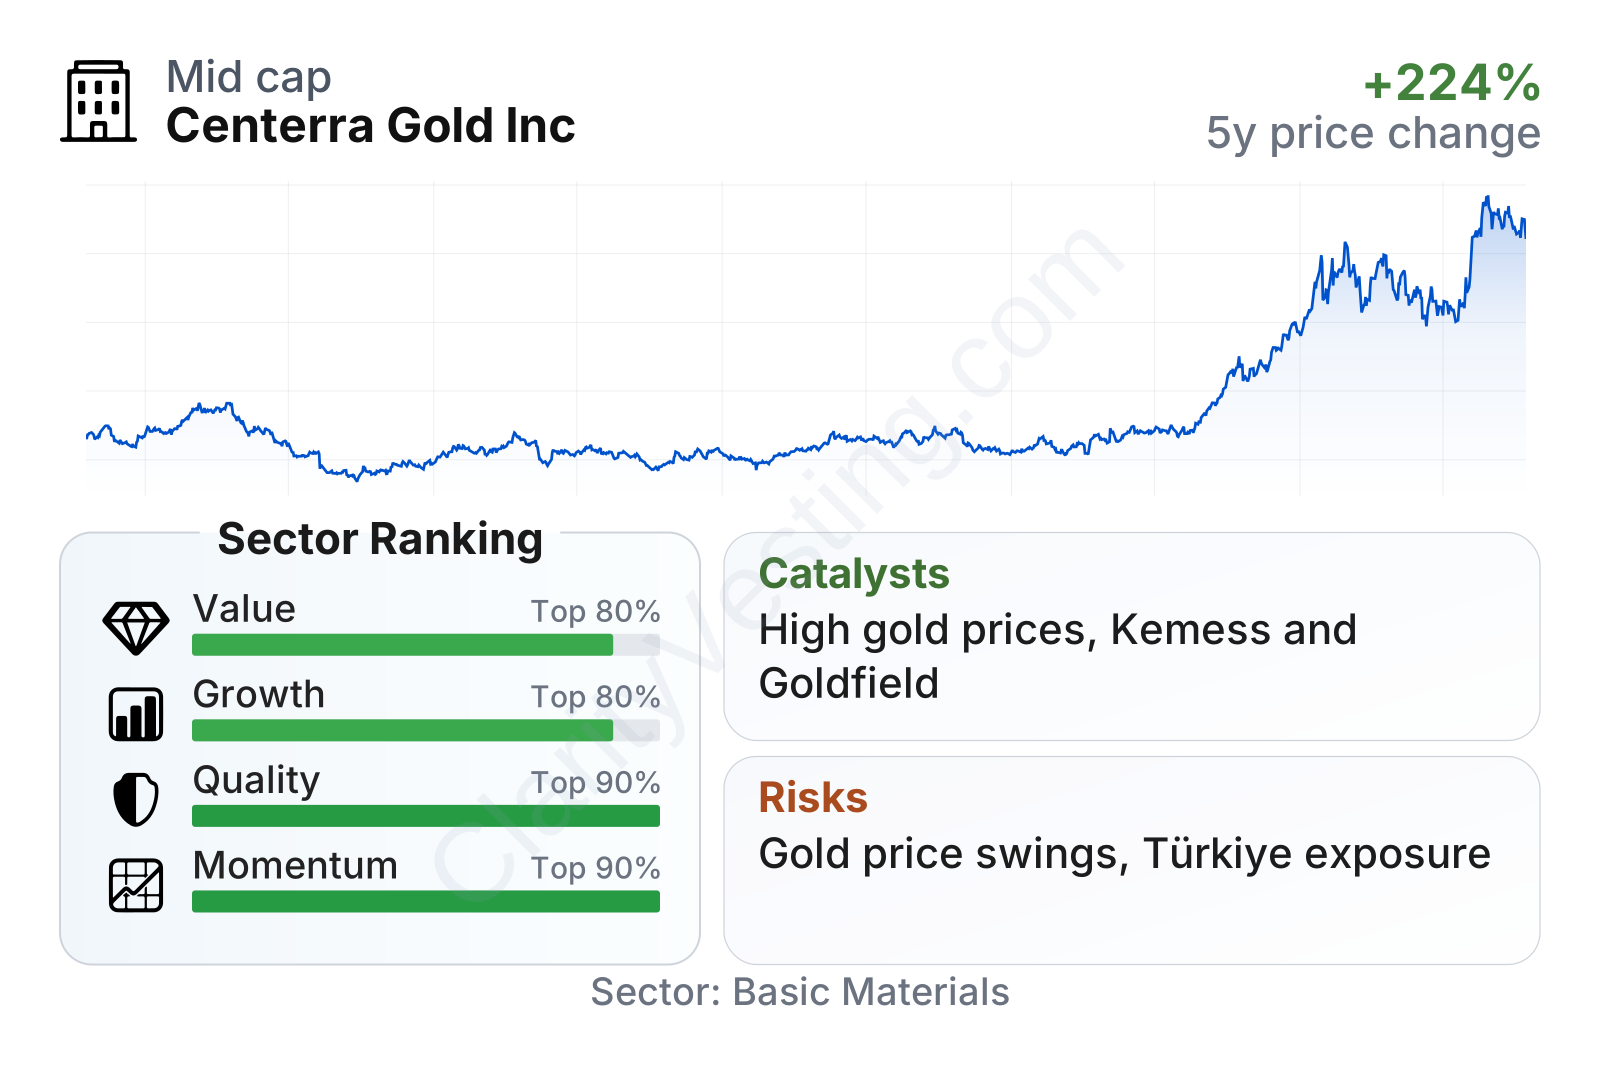
Centerra currently looks strong on quality, growth, and market performance relative to much of the gold sector. Profitability and returns on capital are well above sector medians, while leverage remains extremely low. The weaker point in the table is income distribution and cash generation relative to market value: free cash flow yield and dividend yield are below sector medians, which suggests the stock’s recent re-rating has already absorbed part of the operational improvement.
The share price history also shows how cyclical sentiment can be in mining. After a long weak period through 2022 and 2023, the stock rose sharply across 2025 and into 2026. That kind of move usually reflects both better company execution and stronger expectations for gold-related earnings, but it also means the market is no longer viewing the company as distressed.
Growth
Gold mining is a mature industry, but it can still be part of a growing demand picture. Gold benefits from central bank purchases, investor demand during periods of inflation or geopolitical stress, and its role as a store of value. Copper also adds an important angle, because it is tied to electrification, power networks, and industrial investment. That combination gives Centerra exposure to both defensive and industrial demand drivers.
Centerra’s strategy appears sensible for long-term growth because it is built on three pillars: improving current mines, extending mine life, and advancing development assets. Mount Milligan is important not only for gold output but also because copper adds diversification. Öksüt gives the company another producing gold asset with relatively high strategic importance. Beyond current production, projects such as Kemess and Goldfield give the company future optionality if commodity prices and project economics remain supportive.
Recent revenue growth has been strong, with year-over-year gains well above the sector median. The pattern has been volatile, which is normal in mining, but the latest readings point to a business that is benefiting from both operational recovery and stronger realized pricing. That matters because volume growth in mining is often hard to achieve; when it does happen alongside stronger metal prices, earnings can expand quickly.
Free cash flow has been uneven, which is typical for a miner because working capital swings, sustaining capital, and development spending can move sharply from one period to another. Even so, the company remains cash-generative overall and, importantly, it is doing so without relying on heavy debt. That gives management flexibility to fund projects, maintain dividends, and absorb commodity downturns better than more leveraged peers.
A notable recent catalyst is the strength of gold prices, which has a direct impact on Centerra’s earnings power. Another is the company’s ongoing effort to optimize existing operations and convert its project pipeline into longer mine life. If development milestones at Kemess or Goldfield progress favorably, the market may begin assigning more value to assets that are not yet contributing fully to current earnings.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


