Stock Analysis · Certara Inc (CERT)
Overview
Certara is a healthcare technology company focused on drug development software, biosimulation, and specialized scientific services. In simple terms, it helps pharmaceutical, biotechnology, and medical research organizations make better decisions while developing medicines. Its tools are used to predict how a drug may behave in the body, support trial design, analyze evidence, and prepare material for regulators. The company operates in a niche where software, regulatory science, and consulting come together.
Its business model combines recurring software revenue with service revenue from scientific experts. Based on recent annual disclosures, revenue is mainly organized around software products and expert services tied to drug development and regulatory work.
- Software: approximately 40% to 45% of revenue. This includes subscription-based platforms for biosimulation, data analytics, and model-informed drug development.
- Services: approximately 55% to 60% of revenue. This includes consulting, regulatory science, market access, and other scientific support provided to drug developers.
That mix matters. Software usually brings more predictable and scalable economics, while services can deepen customer relationships and create cross-selling opportunities. Over the last several years, the company has also expanded through acquisitions, aiming to build a broader end-to-end platform for drug development.
The broader financial flow shows a business with high gross profit, but one that has had uneven bottom-line performance because operating expenses, acquisition-related costs, and interest expense have absorbed a meaningful share of revenue. Revenue has still increased from roughly $286 million in 2021 to about $419 million in 2025, while operating income recovered in 2025 after a weak 2023 and modest 2024.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 03, 2026 | |
| Context | ||
| Sector | Healthcare | |
| Industry | Health Information Services | |
| Market Cap ⓘ | $1.40B | |
| Beta ⓘ | 1.41 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | N/A | 24.06 |
| P/B Ratio ⓘ | 1.49 | 3.08 |
| FCF Yield ⓘ | 4.39% | 3.07% |
| Dividend Yield ⓘ | N/A | 2.05% |
| EBIT / EV ⓘ | 2.23% | 0.63% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 1.00% | 7.50% |
| RPS Growth (5Y CAGR) ⓘ | 8.14% | 8.70% |
| EPS Growth (5Y CAGR) ⓘ | -27.19% | -18.20% |
| BVPS Growth (5Y CAGR) ⓘ | -1.20% | 3.95% |
| Margin Growth (5Y Trend) ⓘ | 1.83% | -0.58% |
| FCF Growth (5Y CAGR) ⓘ | 7.89% | 0.88% |
| DPS Growth (5Y CAGR) ⓘ | -85.25% | 6.80% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 1.88% | 3.29% |
| ROA (Latest) ⓘ | -4.66% | 3.02% |
| ROIC (5Y Median) ⓘ | 0.25% | 4.75% |
| ROA (5Y Median) ⓘ | -0.77% | 1.93% |
| Net Debt / EBIT (Latest) ⓘ | 3.38 | 1.33 |
| Net Debt / EBIT (5Y Median) ⓘ | 5.53 | 1.83 |
| Net Debt / EBITDA (Latest) ⓘ | 1.29 | 0.99 |
| Net Debt / Assets ⓘ | 7.69% | 5.33% |
| EBITDA / Interest ⓘ | 1.69 | 9.63 |
| Operating Margin (Latest) ⓘ | 7.79% | 9.25% |
| Operating Margin (5Y Median) ⓘ | 4.71% | 7.80% |
| Debt to Equity (Latest) ⓘ | 30.19% | 28.99% |
| Profit Margin (Latest) ⓘ | -16.22% | 3.60% |
| Free Cash Flow (Latest) ⓘ | $61.64M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | -35.14% | +37.48% |
| 12M Return (excl. last month) ⓘ | -25.28% | +20.85% |
| 6M Return ⓘ | +69.82% | +9.73% |
| Price vs. 200-Day MA ⓘ | +30.07% | +4.69% |
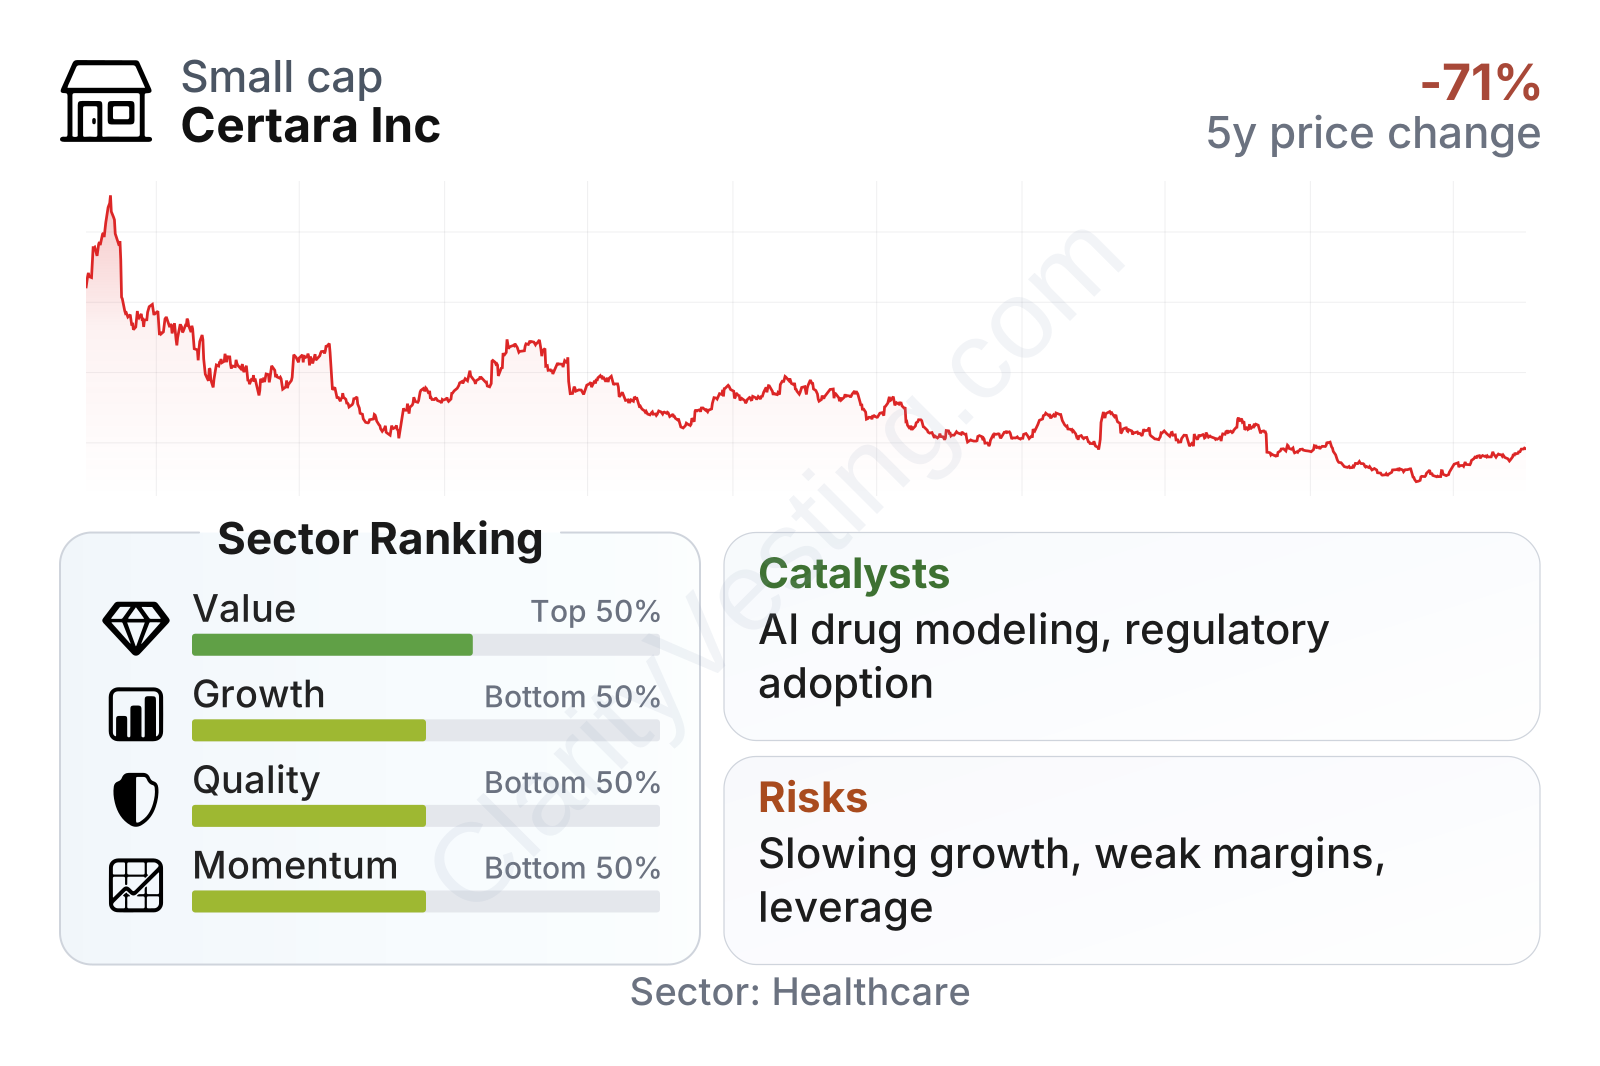
Certara is a small-to-mid-sized healthcare technology company by market value, and its share price history has been volatile. The stock is far below its 2021 level, although it has shown a rebound over the last six months from a very low base. In the factor snapshot, valuation looks more favorable than much of the sector, supported by a price-to-book ratio below the sector median and a free cash flow yield above the median. Growth and quality are less convincing, however, with weak recent sales momentum, low returns on capital, and leverage metrics that remain heavier than many healthcare peers.
Growth
Certara operates in a part of healthcare that still has long-term structural tailwinds. Drug developers face rising costs, more complex clinical programs, and pressure to use data and modeling earlier in the process. Biosimulation and model-informed drug development can potentially reduce failed experiments, improve trial design, and support regulatory interactions. That gives the company exposure to a growing need rather than a passing theme.
Its strategy also makes logical sense. Certara is trying to be more than a single-product vendor by combining software with high-value expert services. That can make the platform stickier: a customer may start with consulting or regulatory support and later adopt software, or begin with software and then add scientific services. The company has also emphasized newer areas such as AI-enabled workflows and expanded regulatory and evidence capabilities, which could widen its relevance across the drug development cycle.
The growth picture, however, has clearly cooled. Revenue expanded at solid double-digit rates in earlier periods, but the pace slowed materially through 2025 and turned negative in mid-2026 on a year-over-year basis. That does not erase the longer-term expansion record, but it does show that demand has become less consistent. Relative to the healthcare sector, recent growth has lagged.
One encouraging point is cash generation. Free cash flow has remained positive and fairly resilient, staying around the low tens of millions of dollars even as earnings have been uneven. Over a five-year view, free cash flow growth has been stronger than the sector median, which suggests the business still has useful financial flexibility if management can stabilize demand and protect margins.
Recent company announcements have continued to highlight partnerships, product enhancements, and the use of AI across drug development workflows. The most important opportunity is not one single headline but the possibility that regulators and drug developers increasingly embed biosimulation and model-based evidence into standard practice. If that trend continues, Certara is positioned in a specialized segment with meaningful relevance.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


