Stock Analysis · Central Garden & Pet Company (CENT)
Overview
Central Garden & Pet Company is a consumer products company focused on two everyday categories: lawn and garden care, and pet care. Its products are sold through home centers, mass merchants, farm and feed stores, pet specialty chains, e-commerce platforms, and distributors. The business is built around a large portfolio of brands rather than a single flagship name, which gives it exposure to many recurring household purchases.
The company reports two main operating segments. Based on its latest annual filing for fiscal 2025, revenue is split roughly as follows:
- Pet segment: about 56% of revenue. This includes dog and cat treats, toys, waste management products, animal health items, pet bedding, aquatics, reptile products, and small animal supplies.
- Garden segment: about 44% of revenue. This includes grass seed, wild bird feed, fertilizer, weed and insect control, decorative outdoor products, and other lawn and garden supplies.
This mix matters because it combines a relatively steady category in pet care with a more seasonal category in gardening. That gives Central some diversification, but it also means results can swing with weather patterns and consumer demand in outdoor products.
The company’s recent financial flow shows a business with annual revenue a little above $3.1 billion in fiscal 2025, gross profit just under $1.0 billion, and net income rebounding after a softer fiscal 2024. One positive sign is that gross profit held up better than sales over the past few years, suggesting cost and pricing discipline helped cushion weaker top-line performance.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Consumer Defensive | |
| Industry | Packaged Foods | |
| Market Cap ⓘ | $2.56B | |
| Beta ⓘ | 0.59 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 15.16 | 17.88 |
| P/B Ratio ⓘ | 1.47 | 1.29 |
| FCF Yield ⓘ | 13.49% | 12.39% |
| Dividend Yield ⓘ | N/A | 2.85% |
| EBIT / EV ⓘ | 10.23% | 6.43% |
| PEG ⓘ | 2.01 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | -8.20% | 4.10% |
| RPS Growth (5Y CAGR) ⓘ | -4.84% | 6.18% |
| EPS Growth (5Y CAGR) ⓘ | 8.18% | -13.59% |
| BVPS Growth (5Y CAGR) ⓘ | 2.91% | 3.20% |
| Margin Growth (5Y Trend) ⓘ | 1.18% | -0.15% |
| FCF Growth (5Y CAGR) ⓘ | 14.31% | 4.10% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 6.79% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 7.15% | 12.34% |
| ROA (Latest) ⓘ | 4.49% | 6.30% |
| ROIC (5Y Median) ⓘ | 7.52% | 10.49% |
| ROA (5Y Median) ⓘ | 4.54% | 5.44% |
| Net Debt / EBIT (Latest) ⓘ | 1.54 | 1.96 |
| Net Debt / EBIT (5Y Median) ⓘ | 3.71 | 2.35 |
| Net Debt / EBITDA (Latest) ⓘ | 1.18 | 1.38 |
| Net Debt / Assets ⓘ | 10.87% | 21.51% |
| EBITDA / Interest ⓘ | 6.09 | 9.46 |
| Operating Margin (Latest) ⓘ | 8.65% | 8.87% |
| Operating Margin (5Y Median) ⓘ | 7.59% | 9.53% |
| Debt to Equity (Latest) ⓘ | 80.69% | 72.35% |
| Profit Margin (Latest) ⓘ | 5.39% | 5.40% |
| Free Cash Flow (Latest) ⓘ | $345.63M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +20.79% | +20.92% |
| 12M Return (excl. last month) ⓘ | +12.73% | +2.13% |
| 6M Return ⓘ | +8.37% | +1.26% |
| Price vs. 200-Day MA ⓘ | +5.41% | +1.39% |
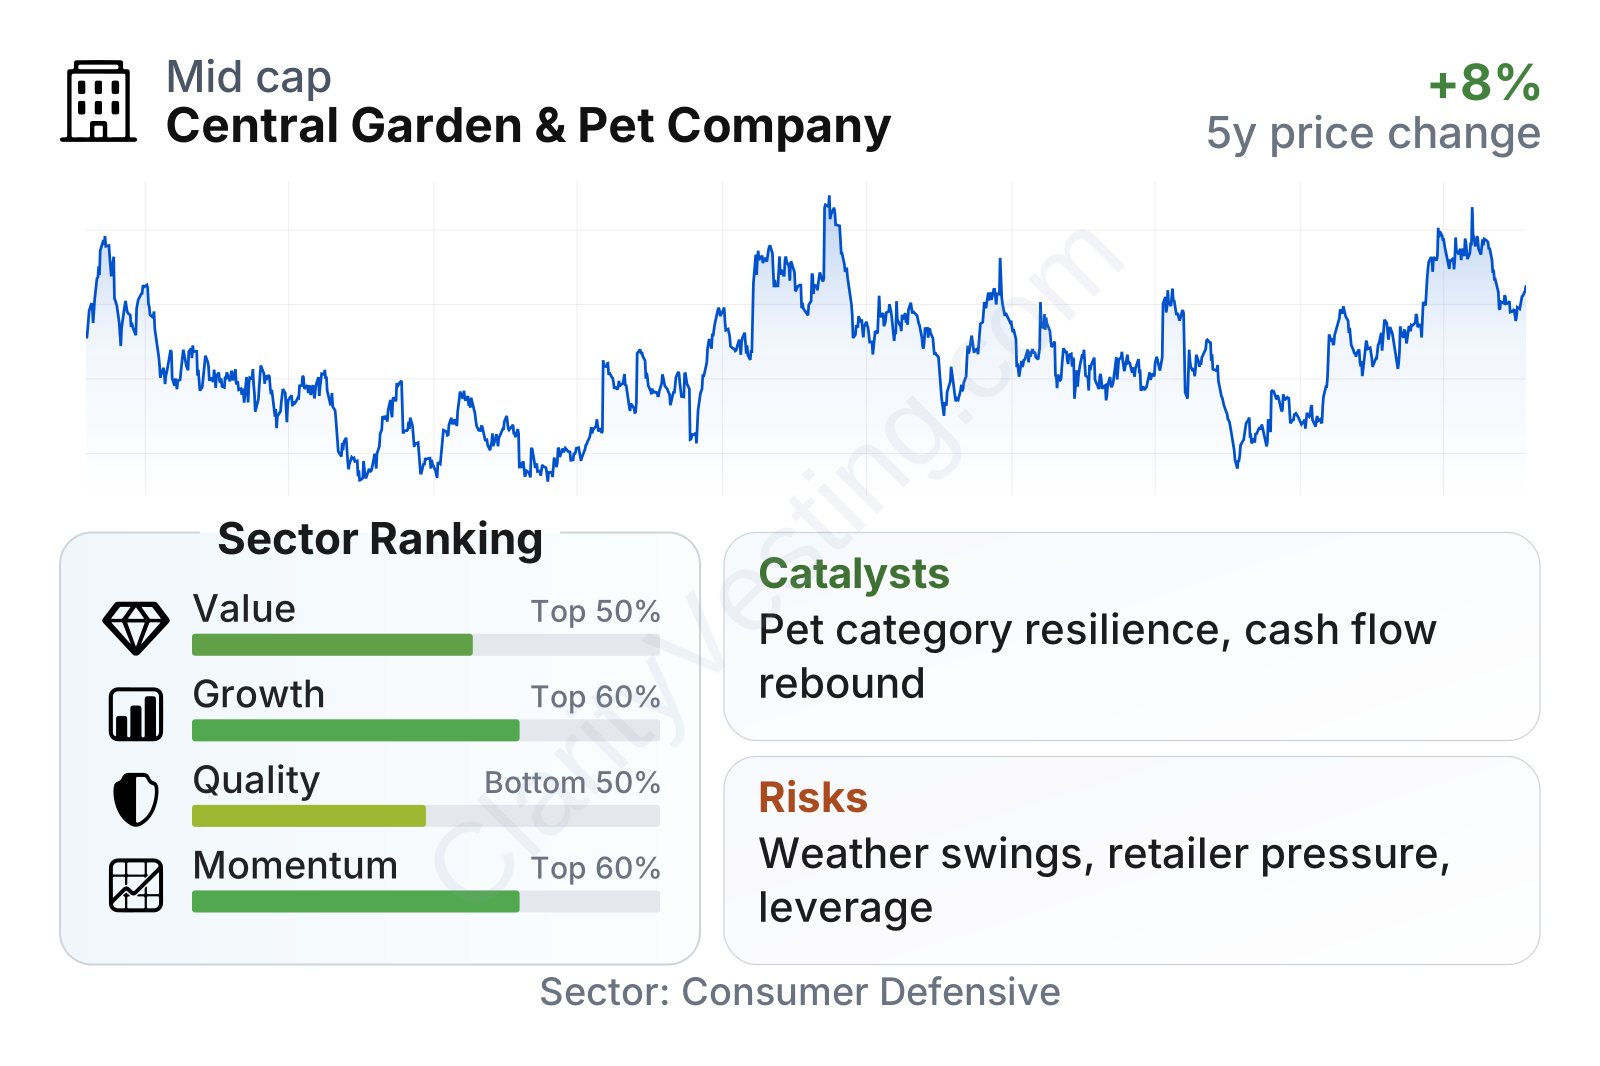
Central is a mid-sized consumer products company with a relatively low beta, which means its share price has historically moved less than the broader market. On valuation, the stock trades at an earnings multiple below the sector median, while cash generation metrics look stronger than many peers. Growth is the weaker area: recent revenue has been uneven and below the sector median, but earnings and free cash flow have improved more favorably over a multi-year period. Quality is more mixed, with returns on capital and assets below many sector peers even though leverage has become more manageable.
Growth
Central operates in categories that can support long-term demand, but they are not fast-growing in a straight line. Pet care has attractive structural support from high pet ownership, premiumization, and recurring spending on food-related and maintenance products. Garden products are more cyclical and heavily influenced by weather, housing activity, and seasonal retailer orders. That makes the company’s end markets decent for long-term participation, but not naturally high-growth.
Its strategy is centered on brand management, selective acquisitions, product innovation, and operational improvement. That approach makes sense for this type of company because scale helps with retail shelf space, sourcing, logistics, and cross-selling. Management has also been working on simplifying the portfolio and improving margins, which matters because this is a business where small efficiency gains can have a meaningful effect on earnings.
Revenue growth has been choppy. The company moved from stronger post-pandemic demand into a period of softer sales, and the latest year-over-year readings still show volatility. That said, the pattern also suggests the business is capable of returning to growth in individual quarters when conditions normalize, especially in seasonal categories.
Free cash flow is one of the more encouraging parts of the profile. After being negative earlier in the cycle, it improved sharply and has remained solid, even with some pullback from the recent peak. For a company with moderate growth, dependable cash generation is important because it supports debt reduction, acquisitions, capital spending, and resilience during slower sales periods.
A recent development with strategic significance is the company’s continued emphasis on operational efficiency and higher-margin brand categories. Central has also remained active in bolt-on acquisitions over time, using its broad platform to add products that fit existing retail channels. In a fragmented pet and garden landscape, that can remain a practical catalyst if integration stays disciplined.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


