Stock Analysis · Celsius Holdings Inc (CELH)
Overview
Celsius Holdings is a beverage company focused on fitness and energy drinks. Its main brand, Celsius, is positioned around products marketed as supporting active lifestyles, with formulas that typically include caffeine, vitamins, and other functional ingredients. Over time, the company has expanded from a niche wellness drink brand into a much larger player in the fast-growing energy drink category, helped by broad retail distribution and international expansion.
The business is still highly concentrated around one core platform: ready-to-drink functional energy beverages sold under the Celsius name and a small number of related line extensions. Based on recent company filings, revenue is mainly generated by beverage sales through retail channels and distribution partners, with the PepsiCo distribution relationship remaining central to scale in North America.
The revenue mix is not broken out in a very detailed public segment format, but the business can be understood approximately as follows:
- North America beverage sales: approximately 85% to 90% of revenue. This includes Celsius branded energy drinks sold in the United States and Canada through grocery, convenience, club, fitness, e-commerce, and foodservice channels.
- International beverage sales: approximately 10% to 15% of revenue. This includes expansion outside North America through local distributors and market launches in selected countries.
- Other revenue: a very small share of revenue. This can include legacy brands, powders, and smaller adjacent offerings, but these do not appear to drive the investment case.
The financial profile shows how dramatically Celsius has scaled. Revenue rose from roughly $314 million in 2021 to about $2.5 billion in 2025, while gross profit also expanded sharply. At the same time, selling and marketing costs climbed materially as the company spent to support distribution, shelf space, and brand awareness. That helps explain why revenue has surged faster than bottom-line consistency.
The business has become far larger in a short time, but it is also showing the classic pattern of a fast-growing consumer brand: strong top-line expansion, meaningful cash generation, and profit margins that can move around as the company invests for scale.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Consumer Defensive | |
| Industry | Beverages - Non-Alcoholic | |
| Market Cap ⓘ | $7.18B | |
| Beta ⓘ | 1.00 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 123.43 | 17.88 |
| P/B Ratio ⓘ | 2.42 | 1.29 |
| FCF Yield ⓘ | 6.44% | 12.39% |
| Dividend Yield ⓘ | N/A | 2.85% |
| EBIT / EV ⓘ | 2.13% | 6.43% |
| PEG ⓘ | 0.27 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 10.60% | 4.10% |
| RPS Growth (5Y CAGR) ⓘ | 67.46% | 6.18% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -13.59% |
| BVPS Growth (5Y CAGR) ⓘ | 91.03% | 3.20% |
| Margin Growth (5Y Trend) ⓘ | 8.21% | -0.15% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 4.10% |
| DPS Growth (5Y CAGR) ⓘ | 33.81% | 6.79% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 8.74% | 12.34% |
| ROA (Latest) ⓘ | 2.11% | 6.30% |
| ROIC (5Y Median) ⓘ | 13.35% | 10.49% |
| ROA (5Y Median) ⓘ | 3.14% | 5.44% |
| Net Debt / EBIT (Latest) ⓘ | 0.19 | 1.96 |
| Net Debt / EBIT (5Y Median) ⓘ | -2.58 | 2.35 |
| Net Debt / EBITDA (Latest) ⓘ | 0.16 | 1.38 |
| Net Debt / Assets ⓘ | 0.71% | 21.51% |
| EBITDA / Interest ⓘ | 4.29 | 9.46 |
| Operating Margin (Latest) ⓘ | 6.43% | 8.87% |
| Operating Margin (5Y Median) ⓘ | 6.92% | 9.53% |
| Debt to Equity (Latest) ⓘ | 22.57% | 72.35% |
| Profit Margin (Latest) ⓘ | 4.24% | 5.40% |
| Free Cash Flow (Latest) ⓘ | $462.77M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | -48.81% | +20.92% |
| 12M Return (excl. last month) ⓘ | -52.92% | +2.13% |
| 6M Return ⓘ | -17.02% | +1.26% |
| Price vs. 200-Day MA ⓘ | -22.17% | +1.39% |
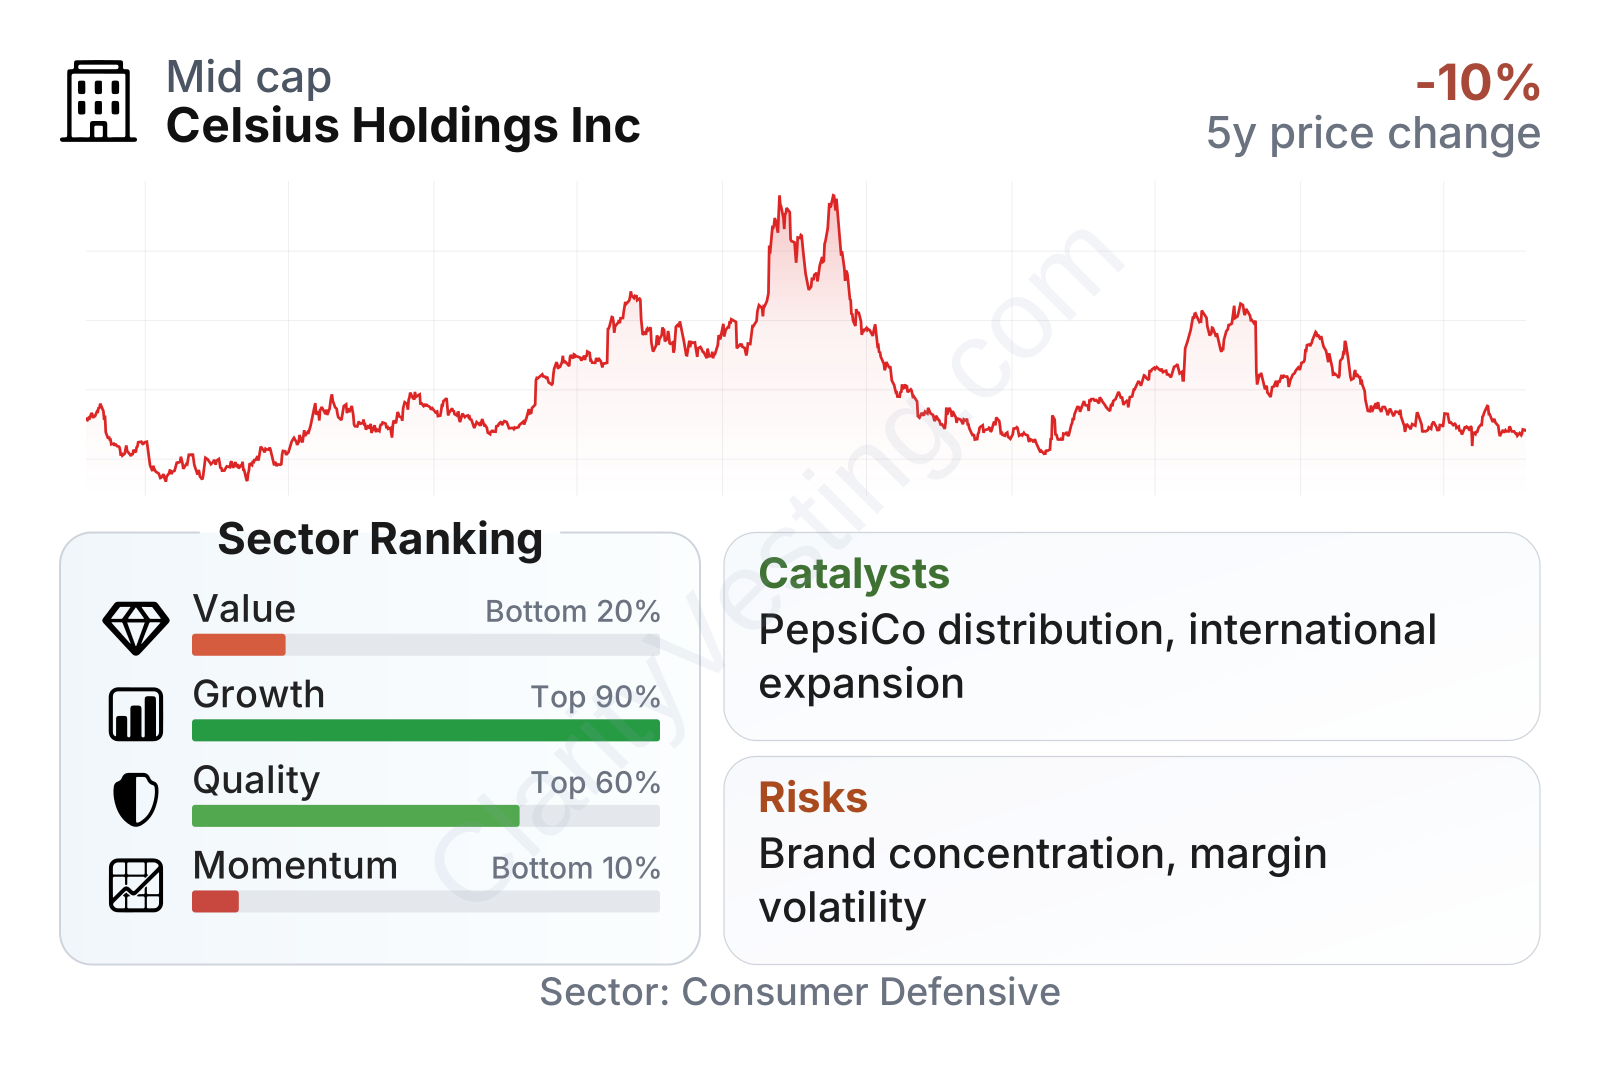
Celsius sits in a mixed position across the main financial factors. Growth remains one of its clearest strengths, ranking near the top of its sector, while quality is more middle-of-the-pack and value looks weak because the stock still trades at a much higher earnings multiple than most beverage peers. Momentum is currently the weakest area, reflecting a steep share-price reset from earlier highs rather than a collapse in the business itself.
The company is now a mid-sized public beverage company with a market value around $7 billion. Its balance sheet is still relatively light on leverage compared with the sector, and free cash flow remains positive, which gives Celsius more flexibility than many younger growth brands. The main tension in the numbers is simple: operating performance is still expanding faster than many peers, but the stock has not become conventionally cheap.
Growth
Celsius operates in one of the more attractive pockets of consumer staples: energy and functional beverages. This part of the drink market has benefited from several long-running trends, including demand for convenience, higher caffeine consumption, fitness-oriented branding, sugar-free formulations, and consumer interest in drinks that sit between traditional soda and sports nutrition. That broader backdrop supports long-term category growth even if quarterly results can be uneven.
The company’s strategy is also logical for this category. Celsius has relied on a focused brand identity, premium placement in retail, and an asset-light distribution approach rather than building a huge manufacturing network itself. Its relationship with PepsiCo has been especially important because it gave the brand access to a much broader route-to-market, helping Celsius move from rapid niche growth to mass-market availability. That kind of distribution support is difficult for smaller rivals to replicate.
Revenue growth has been exceptionally strong over the multi-year period, although it has clearly become more volatile as the business has gotten larger. After explosive gains in 2022 and 2023, growth cooled, briefly turned negative, and then rebounded sharply before moderating again into 2026. That pattern suggests Celsius is no longer in the easiest phase of expansion, but it is still growing faster than the typical company in its sector.
Cash generation is another important positive. Free cash flow has improved substantially from negative territory a few years ago to several hundred million dollars on a trailing basis. That matters because it shows growth has not been purely accounting-based. Celsius is converting a meaningful portion of its expansion into actual cash that can support inventory, international launches, and brand investment without depending heavily on debt.
A major catalyst for future growth is international development. Celsius has already built a very strong base in the United States, so the next leg increasingly depends on extending brand awareness into new markets and deepening placement in existing ones. Additional product innovation also matters, especially new flavors, pack sizes, and adjacent functional offerings that can increase sales per customer without requiring a new brand from scratch.
Recent company communications have also pointed to ongoing efforts to broaden retail penetration, improve execution with distribution partners, and expand globally. None of that guarantees smooth results, but these are the right operational levers for a beverage company trying to move from a successful domestic growth brand to a broader international platform.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


