Stock Analysis · China BlueChemical Ltd (CBLUF)
Overview
China BlueChemical Ltd is a Chinese chemical and fertilizer producer focused on products used in agriculture and industrial manufacturing. The company is best known for making urea and other nitrogen fertilizers, which are essential for crop yields, but it also has a meaningful chemicals business serving industrial customers. Its operations are tied to basic demand drivers that tend to persist over long periods: food production, domestic fertilizer supply, and industrial chemical consumption.
The business is generally organized around a few main product categories. Based on the company’s public reporting in recent annual materials, revenue is primarily generated from fertilizer and chemical products, with fertilizer remaining the core contributor.
- Urea and other fertilizer products: approximately 55% to 70% of revenue in recent years. This includes nitrogen fertilizer used by farmers and distributors across China.
- Methanol and other chemical products: approximately 25% to 40% of revenue. These products are used in industrial processes and can be more cyclical than agricultural demand.
- Phosphate and compound fertilizer, along with other smaller businesses: generally a low-to-mid single share of revenue when disclosed separately, depending on the year and product pricing.
This mix matters because it gives the company some diversification, but it does not remove the fact that profits are still heavily influenced by commodity pricing, feedstock costs, and domestic Chinese supply-demand conditions. Over the last several years, revenue has drifted lower from the 2022 peak, while profits have been more volatile than sales, showing how sensitive results are to margins rather than just volume.
The multi-year earnings flow shows a business that still converts a large portion of sales into gross profit, but with noticeable compression since 2023. Revenue has declined moderately from earlier highs, while operating income and net income have fallen more sharply, which suggests pricing and margin pressure rather than a collapse in demand. Selling and administrative costs have stayed fairly steady, so the main swing factor has been product economics.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Agricultural Inputs | |
| Market Cap ⓘ | $1.73B | |
| Beta ⓘ | 0.88 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 12.50 | 16.90 |
| P/B Ratio ⓘ | 0.05 | 1.65 |
| FCF Yield ⓘ | 64.17% | 5.76% |
| Dividend Yield ⓘ | 43.08% | 2.13% |
| EBIT / EV ⓘ | N/A | 6.30% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | -3.90% | 11.10% |
| RPS Growth (5Y CAGR) ⓘ | -3.28% | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | 26.67% | -13.47% |
| BVPS Growth (5Y CAGR) ⓘ | 2.84% | 5.51% |
| Margin Growth (5Y Trend) ⓘ | -10.05% | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | -15.07% | 0.37% |
| DPS Growth (5Y CAGR) ⓘ | 10.85% | 6.08% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 9.26% |
| ROA (Latest) ⓘ | 7.25% | 4.91% |
| ROIC (5Y Median) ⓘ | 8.07% | 7.70% |
| ROA (5Y Median) ⓘ | 7.10% | 3.86% |
| Net Debt / EBIT (Latest) ⓘ | 1.32 | 1.40 |
| Net Debt / EBIT (5Y Median) ⓘ | 0.85 | 1.70 |
| Net Debt / EBITDA (Latest) ⓘ | 0.70 | 0.95 |
| Net Debt / Assets ⓘ | 6.71% | 13.69% |
| EBITDA / Interest ⓘ | N/A | 12.34 |
| Operating Margin (Latest) ⓘ | 6.20% | 13.20% |
| Operating Margin (5Y Median) ⓘ | 12.72% | 11.80% |
| Debt to Equity (Latest) ⓘ | 12.90% | 40.56% |
| Profit Margin (Latest) ⓘ | 7.13% | 6.43% |
| Free Cash Flow (Latest) ⓘ | $1.11B | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +3.92% | +68.89% |
| 12M Return (excl. last month) ⓘ | -26.67% | +30.21% |
| 6M Return ⓘ | -39.53% | -4.16% |
| Price vs. 200-Day MA ⓘ | -4.08% | -1.27% |
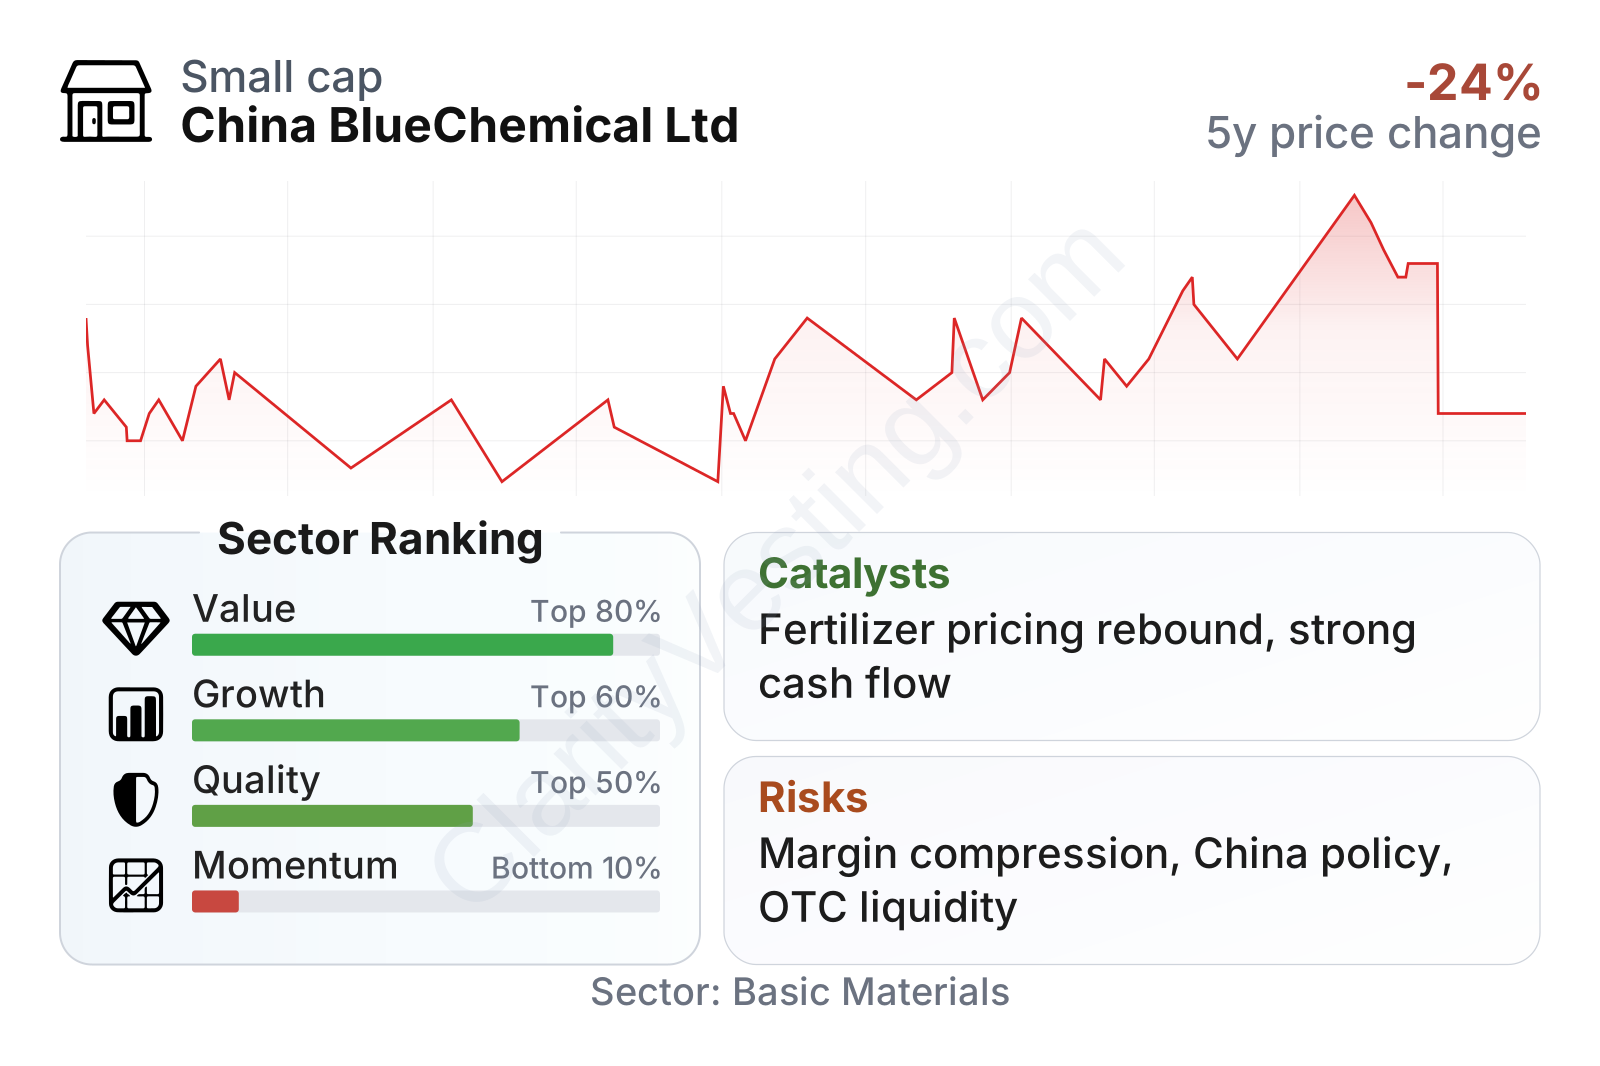
China BlueChemical currently looks inexpensive on common valuation measures compared with much of the agricultural inputs sector. Its earnings multiple is below the sector median, and the price-to-book ratio is unusually low. Free cash flow yield is also exceptionally high, helped by strong cash generation relative to its current market value. The company also stands out for a very high trailing dividend yield, although investors should remember that payouts in cyclical industries can move significantly from year to year.
On balance sheet strength, the company looks relatively solid. Debt is modest, with debt-to-equity around 13%, and net debt appears manageable relative to EBIT and EBITDA. Profit margin is slightly above the sector median, but operating margin has recently weakened and now sits below typical sector levels. That combination suggests the company is still profitable and financially stable, but not operating at peak efficiency.
The market’s recent view has been weak. The share price has fallen sharply over the past 6 to 12 months and has materially lagged the broader sector over one- and three-year periods. That poor momentum likely reflects concern about slowing growth, softer margins, and the company’s exposure to cyclical product prices rather than a balance-sheet problem.
Growth
China BlueChemical operates in a sector that has a durable long-term foundation but not an especially smooth growth path. Fertilizer demand benefits from the need to sustain agricultural productivity, especially in a country such as China where food security remains strategically important. That gives the business a structural demand base. However, this is not a high-growth technology-like market. Growth tends to come from product mix upgrades, cost control, capacity optimization, and favorable pricing cycles rather than from rapid expansion in end demand.
The company’s strategy makes sense in that context. It has scale in nitrogen fertilizer, exposure to a necessary agricultural input, and a second leg in methanol and chemicals. This combination can support cash generation across cycles when conditions are favorable. The challenge is that recent numbers show weaker top-line growth, with revenue slightly down year over year and revenue per share lower over five years. Earnings per share over five years have still grown strongly, which implies the company has had periods of strong profitability even without consistent sales expansion.
A practical catalyst is any improvement in fertilizer pricing or reduction in feedstock pressure. Because the company’s earnings are very sensitive to margins, even a moderate recovery in pricing conditions can have a larger impact on profit than on revenue. Another supportive factor is its strong cash generation and low leverage, which give it flexibility to maintain operations, fund maintenance spending, and continue shareholder distributions when business conditions allow.
Recent public company materials also continue to frame fertilizer as a strategically important industry in China. That does not guarantee fast growth, but it does support the relevance of domestic producers with established capacity and distribution channels. In a market where supply discipline improves or input costs ease, China BlueChemical could see a meaningful rebound in profitability without needing dramatic revenue growth.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


