Stock Analysis · Close Brothers Group plc (CBGPF)
Overview
Close Brothers Group plc is a U.K.-based merchant banking group focused on specialist lending, wealth management, and securities services. Unlike a large universal bank, it concentrates on narrower markets where pricing and underwriting discipline matter more than scale alone. Its activities are mainly domestic, with the United Kingdom as the core market.
The business has historically been built around three operating areas:
- Banking, roughly 75% to 85% of operating income in normal years: this is the largest activity and includes specialist lending to small businesses and consumers, asset finance, commercial finance, motor finance, invoice finance, and property-related lending. It is the engine of the group.
- Wealth Management, roughly 10% to 20%: discretionary investment management, financial advice, and related client services for individuals, families, charities, and professionals. Revenue here is tied more to client assets and fees than to loan growth.
- Winterflood, roughly 5% to 10%: securities market-making and execution services, mainly for U.K. retail platforms, brokers, and institutional counterparties. This unit can be more cyclical because trading activity changes with market conditions.
That mix matters for long-term analysis. Specialist lending provides the main earnings base, wealth management adds recurring fee income, and Winterflood offers some diversification, although it can also add volatility.
More recently, the group’s earnings profile has been under pressure. Revenue and profitability have been affected by higher funding costs, weaker returns, and conduct-related issues around motor finance. The business still has several revenue streams, but the bank remains the dominant driver of results.
The business mix has become less favorable over the last few years. Revenue has fallen from earlier peaks, while interest expense rose sharply and operating profit moved into loss. That shift shows how sensitive Close Brothers currently is to funding costs and credit or conduct pressures inside the banking division.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Financial Services | |
| Industry | Banks - Regional | |
| Market Cap ⓘ | $1.09B | |
| Beta ⓘ | 1.24 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | N/A | 12.26 |
| P/B Ratio ⓘ | 0.67 | 1.23 |
| FCF Yield ⓘ | 25.58% | 10.40% |
| Dividend Yield ⓘ | N/A | 3.02% |
| EBIT / EV ⓘ | -0.61% | 8.14% |
| PEG ⓘ | 3.73 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | -11.10% | 9.35% |
| RPS Growth (5Y CAGR) ⓘ | -13.72% | 12.19% |
| EPS Growth (5Y CAGR) ⓘ | 5.52% | -9.53% |
| BVPS Growth (5Y CAGR) ⓘ | -7.21% | 4.99% |
| Margin Growth (5Y Trend) ⓘ | -27.94% | -3.86% |
| FCF Growth (5Y CAGR) ⓘ | 44.33% | 4.81% |
| DPS Growth (5Y CAGR) ⓘ | -28.60% | 8.79% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 9.49% |
| ROE (Latest) ⓘ | -9.63% | 13.90% |
| ROA (Latest) ⓘ | -1.15% | 1.55% |
| ROIC (5Y Median) ⓘ | 1.80% | 7.86% |
| ROE (5Y Median) ⓘ | 4.91% | 12.17% |
| ROA (5Y Median) ⓘ | 0.62% | 1.30% |
| Net Debt / EBIT (Latest) ⓘ | N/A | 0.96 |
| Net Debt / EBIT (5Y Median) ⓘ | 6.94 | 0.73 |
| Net Debt / EBITDA (Latest) ⓘ | 3.02 | 0.92 |
| Operating Margin (Latest) ⓘ | -0.59% | 22.30% |
| Operating Margin (5Y Median) ⓘ | 8.51% | 24.63% |
| Debt to Equity (Latest) ⓘ | 115.41% | 58.56% |
| Profit Margin (Latest) ⓘ | -10.14% | 26.57% |
| Free Cash Flow (Latest) ⓘ | $277.56M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | -27.04% | +88.33% |
| 12M Return (excl. last month) ⓘ | +28.11% | +19.38% |
| 6M Return ⓘ | 0.00% | +4.75% |
| Price vs. 200-Day MA ⓘ | +1.05% | +3.50% |
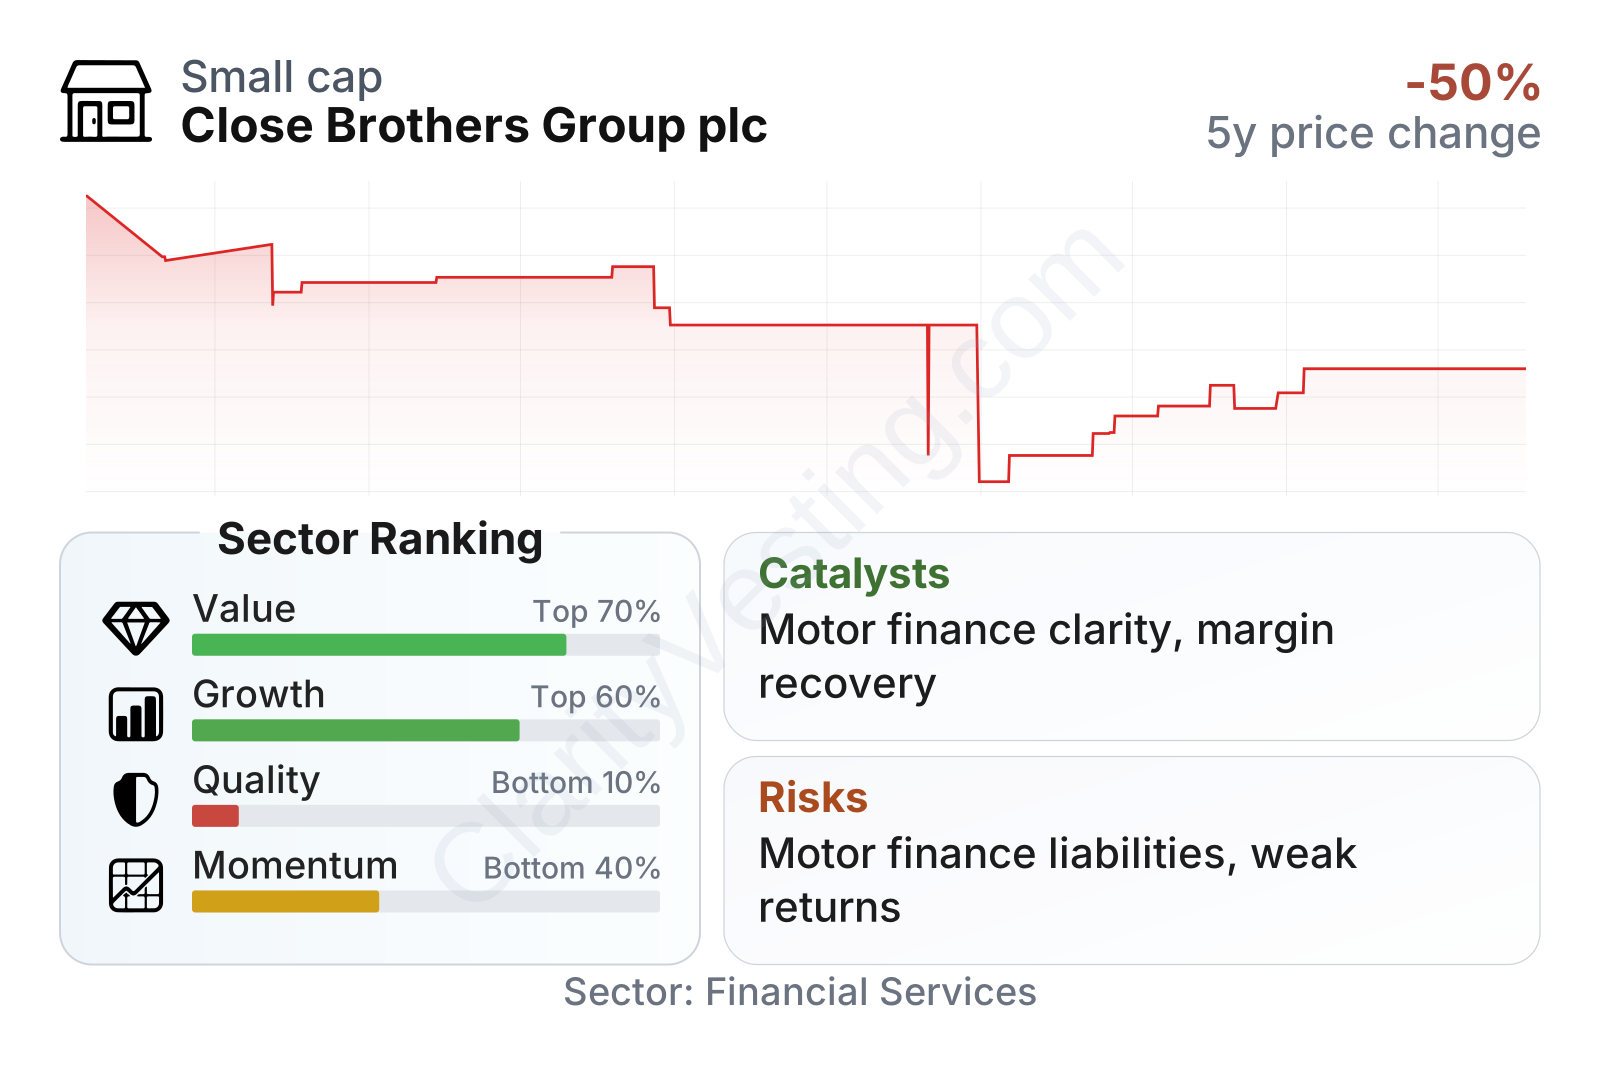
Close Brothers is currently a mid-sized financial company by market value, with share-price volatility somewhat above the broader market. The most important takeaway from the latest metrics is the contrast between cheap-looking valuation measures and weak recent quality metrics. The stock trades below the sector median on price-to-book, but profitability and returns on equity and assets are well below typical peers, and recent margins turned negative. Growth indicators are mixed: long-term earnings per share growth is better than the sector median, but revenue growth, book value growth, and dividend progression have been weak.
The share-price history also reflects that tension. After a steep decline from 2022 into 2025, the stock has recovered from the lows, but it still sits far below earlier levels. That suggests the market has acknowledged some stabilization, while continuing to discount unresolved business and legal uncertainties.
Growth
Close Brothers operates in parts of financial services that can still grow over time. Specialist lending to small businesses, asset-backed borrowing, wealth management for affluent clients, and outsourced securities execution are all durable markets. In that sense, the company is not in a declining industry. The challenge is that these are also areas where growth depends heavily on credit discipline, funding costs, regulation, and confidence.
Its strategy remains understandable for long-term observers. The group focuses on niches where tailored underwriting and long-standing customer relationships can matter more than headline scale. That approach has historically allowed it to earn attractive returns through cycles. Wealth management also gives it access to recurring fee income, which can help smooth results when lending conditions weaken.
Even so, recent earnings do not yet show a clean growth pattern. The latest annual outcome remained loss-making at the group level, despite some signs of operational resilience in the underlying franchise. For a lender, earnings recovery matters more than revenue growth alone, because spreads, impairments, and funding costs can move sharply. The key medium-term question is whether normalized profitability can return once legal uncertainty and funding pressure ease.
Book value per share has also moved down materially in the latest period. For banks and lenders, this is an important signal because book value represents the capital base that supports future lending and earnings. A declining book value does not automatically mean structural damage, but it does reduce room for error and helps explain why the market remains cautious.
The clearest catalyst is resolution of the U.K. motor finance issue. If the final legal and regulatory outcome proves manageable, Close Brothers could regain a more normal earnings profile. Another possible growth support is lower interest-rate pressure over time, which could ease funding costs and improve lending margins. Wealth management may also provide steadier support if client assets and market levels improve. In addition, the company has been simplifying and protecting capital, which can help rebuild confidence if execution improves.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


