Stock Analysis · Buzzi Unicem S.p.A (BZZUF)
Overview
Buzzi Unicem S.p.A. is a building materials producer centered on cement, ready-mix concrete, and aggregates. These are basic inputs used in residential construction, commercial buildings, roads, bridges, industrial sites, and other infrastructure projects. The company is headquartered in Italy and operates across several countries, with particularly important positions in the United States and Europe.
The business is relatively simple to understand: Buzzi sells cement and clinker, then uses part of that output in downstream products such as ready-mix concrete and aggregates. Cement is the core product and usually carries the greatest strategic importance because it feeds both outside sales and the company’s own concrete network. This makes Buzzi more vertically integrated than a pure cement seller.
Based on recent annual reporting, revenue is mainly generated from the following activities:
- Cement and clinker: approximately 70% to 75% of revenue. This includes bulk and bagged cement sold to construction companies, distributors, and internal concrete operations.
- Ready-mix concrete: approximately 20% to 25% of revenue. This is concrete delivered for building sites and infrastructure projects.
- Aggregates and other activities: approximately 5% to 10% of revenue. This includes quarry materials and smaller related operations.
Geographically, the United States is one of the most important profit centers, while Italy, Germany, Luxembourg, the Netherlands, Czech Republic, Poland, and other markets add diversification. That mix matters because it reduces reliance on one construction cycle, although the business still remains closely linked to overall building activity.
The recent profit flow shows a notable improvement versus earlier years: revenue has increased over time, operating income has expanded much faster than sales, and interest expense has remained modest. That combination points to stronger pricing and operating discipline rather than growth driven only by volume.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 10, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Building Materials | |
| Market Cap ⓘ | $7.94B | |
| Beta ⓘ | 1.02 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 8.11 | 17.36 |
| P/B Ratio ⓘ | 1.10 | 1.73 |
| FCF Yield ⓘ | 9.30% | 5.81% |
| Dividend Yield ⓘ | 1.56% | 1.98% |
| EBIT / EV ⓘ | N/A | 6.34% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 0.10% | 11.15% |
| RPS Growth (5Y CAGR) ⓘ | 8.62% | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | -30.52% | -12.80% |
| BVPS Growth (5Y CAGR) ⓘ | 14.30% | 5.49% |
| Margin Growth (5Y Trend) ⓘ | 10.43% | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | 6.71% | 0.20% |
| DPS Growth (5Y CAGR) ⓘ | -8.50% | 5.91% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 9.26% |
| ROA (Latest) ⓘ | 15.55% | 4.92% |
| ROIC (5Y Median) ⓘ | N/A | 7.82% |
| ROA (5Y Median) ⓘ | 10.46% | 3.88% |
| Net Debt / EBIT (Latest) ⓘ | N/A | 1.37 |
| Net Debt / EBIT (5Y Median) ⓘ | -0.44 | 1.70 |
| Net Debt / EBITDA (Latest) ⓘ | N/A | 0.92 |
| Net Debt / Assets ⓘ | N/A | 13.56% |
| EBITDA / Interest ⓘ | N/A | 12.28 |
| Operating Margin (Latest) ⓘ | 29.24% | 13.20% |
| Operating Margin (5Y Median) ⓘ | 24.15% | 11.82% |
| Debt to Equity (Latest) ⓘ | N/A | 39.91% |
| Profit Margin (Latest) ⓘ | 18.96% | 6.43% |
| Free Cash Flow (Latest) ⓘ | $738.82M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +81.44% | +68.93% |
| 12M Return (excl. last month) ⓘ | -6.86% | +36.53% |
| 6M Return ⓘ | -14.30% | 0.00% |
| Price vs. 200-Day MA ⓘ | -1.48% | -0.18% |
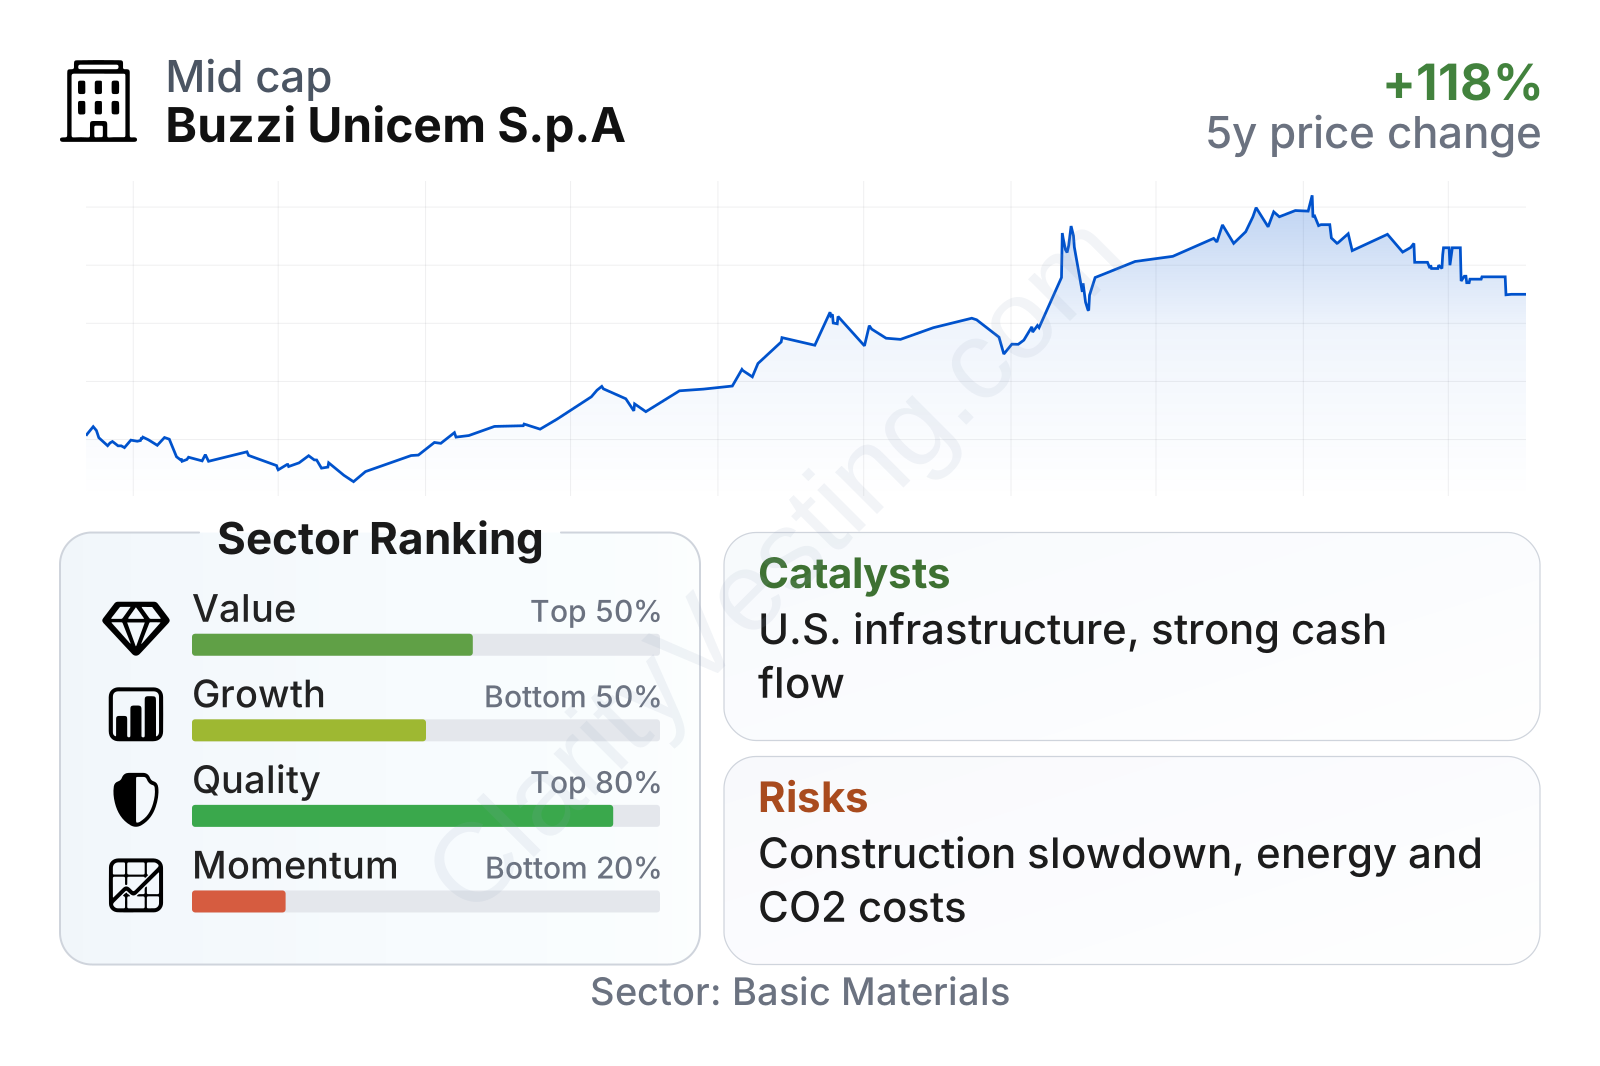
Buzzi is a large building materials company by industry standards, with share-price volatility close to the broader market rather than unusually extreme. The most striking point in the latest metrics is the contrast between strong quality and weaker recent momentum. Profitability stands well above sector medians, balance-sheet pressure appears limited, and free cash flow generation is solid. On valuation, multiples such as earnings and book value sit below typical sector levels, suggesting the market is not assigning a premium despite strong margins and asset returns. Growth is more mixed: long-term per-share revenue and cash generation trends are constructive, but recent year-over-year revenue growth has been subdued.
Growth
The company operates in a sector with long-term relevance rather than rapid structural expansion. Cement, concrete, and aggregates are essential to construction and infrastructure, so demand is tied to urbanization, renovation, energy-transition projects, logistics facilities, roads, and public works. In mature economies, the growth profile is usually cyclical, but replacement needs and infrastructure spending can still support durable activity over long periods.
Buzzi’s strategy is sensible for that environment. It combines core cement capacity with downstream concrete and aggregates, giving the group more control over distribution, customer relationships, and plant utilization. The company has also emphasized efficiency, modernization, and selective capital allocation rather than chasing volume at any price. That matters in cement because pricing discipline and plant efficiency often drive returns more than simple shipment growth.
Recent top-line growth has flattened after a strong earlier expansion phase, which is not unusual for a cyclical materials producer after pricing catches up with inflation and energy cost swings. Even so, the longer trend remains favorable: over five years, revenue per share has grown at a pace above the sector median, showing that Buzzi has created more business value for each share outstanding over time.
Cash generation is one of the strongest parts of the current profile. Free cash flow is robust, and the multi-year trend is stronger than the typical peer in the sector. That gives the company flexibility for plant upgrades, acquisitions, dividends, and balance-sheet protection during weaker parts of the cycle.
A meaningful catalyst is the company’s exposure to U.S. infrastructure and nonresidential construction markets, where public funding, industrial reshoring, and large project pipelines can support cement demand. Another growth lever is pricing: in cement, even modest volume growth can translate into stronger earnings if prices remain firm and energy or transport costs stay under control. Recent annual reporting also shows operating margins improving significantly over the last several years, which suggests Buzzi has been executing well on that front.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


