Stock Analysis · Brambles Ltd (BXBLY)
Overview
Brambles Ltd is a logistics and supply-chain company best known for CHEP, its global pallet and container pooling business. Instead of selling pallets, crates, and reusable containers outright, Brambles rents them to manufacturers, retailers, and distributors, then collects, repairs, and redistributes them through a large network. This model helps customers move goods more efficiently while reducing one-way packaging waste.
The company operates in a part of the economy that is easy to overlook but deeply embedded in daily commerce. Consumer staples, fresh produce, beverages, and many retail goods are transported on Brambles platforms. That gives the business recurring demand tied to the flow of essential products rather than to a single end market.
Revenue is heavily concentrated in pooling services, with regional exposure spread across major consumer goods and retail supply chains. Based on recent annual reporting, the business mix is approximately:
- CHEP Americas: about 54% of revenue. This includes pallet, crate, and container pooling mainly in the United States, Canada, and Latin America.
- CHEP Europe, Middle East and Africa: about 32% of revenue. This segment serves fast-moving consumer goods, fresh food, beverage, and general retail supply chains across the region.
- CHEP Asia-Pacific: about 14% of revenue. This includes Australia, New Zealand, and Asian markets, with a similar reusable-platform model.
The business is also notable for the way profits are created. Revenue has risen over time, and operating income has generally improved as scale and pricing discipline supported margins, although the latest cost split visible in the flow chart appears unusually distorted versus prior years and should be treated cautiously as a presentation issue rather than as a clean indication of a structural collapse in profitability.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Industrials | |
| Industry | Specialty Business Services | |
| Market Cap ⓘ | $19.10B | |
| Beta ⓘ | 0.42 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 20.70 | 22.29 |
| P/B Ratio ⓘ | 6.07 | 1.98 |
| FCF Yield ⓘ | 9.37% | 6.26% |
| Dividend Yield ⓘ | 3.24% | 1.92% |
| EBIT / EV ⓘ | 11.23% | 4.83% |
| PEG ⓘ | 5.14 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 5.00% | 9.30% |
| RPS Growth (5Y CAGR) ⓘ | 6.21% | 7.76% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -13.17% |
| BVPS Growth (5Y CAGR) ⓘ | 8.27% | 6.13% |
| Margin Growth (5Y Trend) ⓘ | 1.55% | 0.74% |
| FCF Growth (5Y CAGR) ⓘ | 9.27% | 10.79% |
| DPS Growth (5Y CAGR) ⓘ | 20.11% | 9.41% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 10.75% |
| ROA (Latest) ⓘ | N/A | 5.41% |
| ROIC (5Y Median) ⓘ | 16.53% | 9.37% |
| ROA (5Y Median) ⓘ | 8.67% | 4.95% |
| Net Debt / EBIT (Latest) ⓘ | 1.27 | 2.04 |
| Net Debt / EBIT (5Y Median) ⓘ | 2.46 | 2.27 |
| Net Debt / EBITDA (Latest) ⓘ | 0.75 | 1.39 |
| Net Debt / Assets ⓘ | 30.11% | 19.27% |
| EBITDA / Interest ⓘ | 14.27 | 9.58 |
| Operating Margin (Latest) ⓘ | 17.61% | 10.49% |
| Operating Margin (5Y Median) ⓘ | 17.03% | 10.30% |
| Debt to Equity (Latest) ⓘ | 93.71% | 64.82% |
| Profit Margin (Latest) ⓘ | 13.15% | 6.67% |
| Free Cash Flow (Latest) ⓘ | $1.79B | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +75.05% | +67.77% |
| 12M Return (excl. last month) ⓘ | -17.13% | +12.05% |
| 6M Return ⓘ | -8.73% | 0.00% |
| Price vs. 200-Day MA ⓘ | +0.72% | +0.67% |
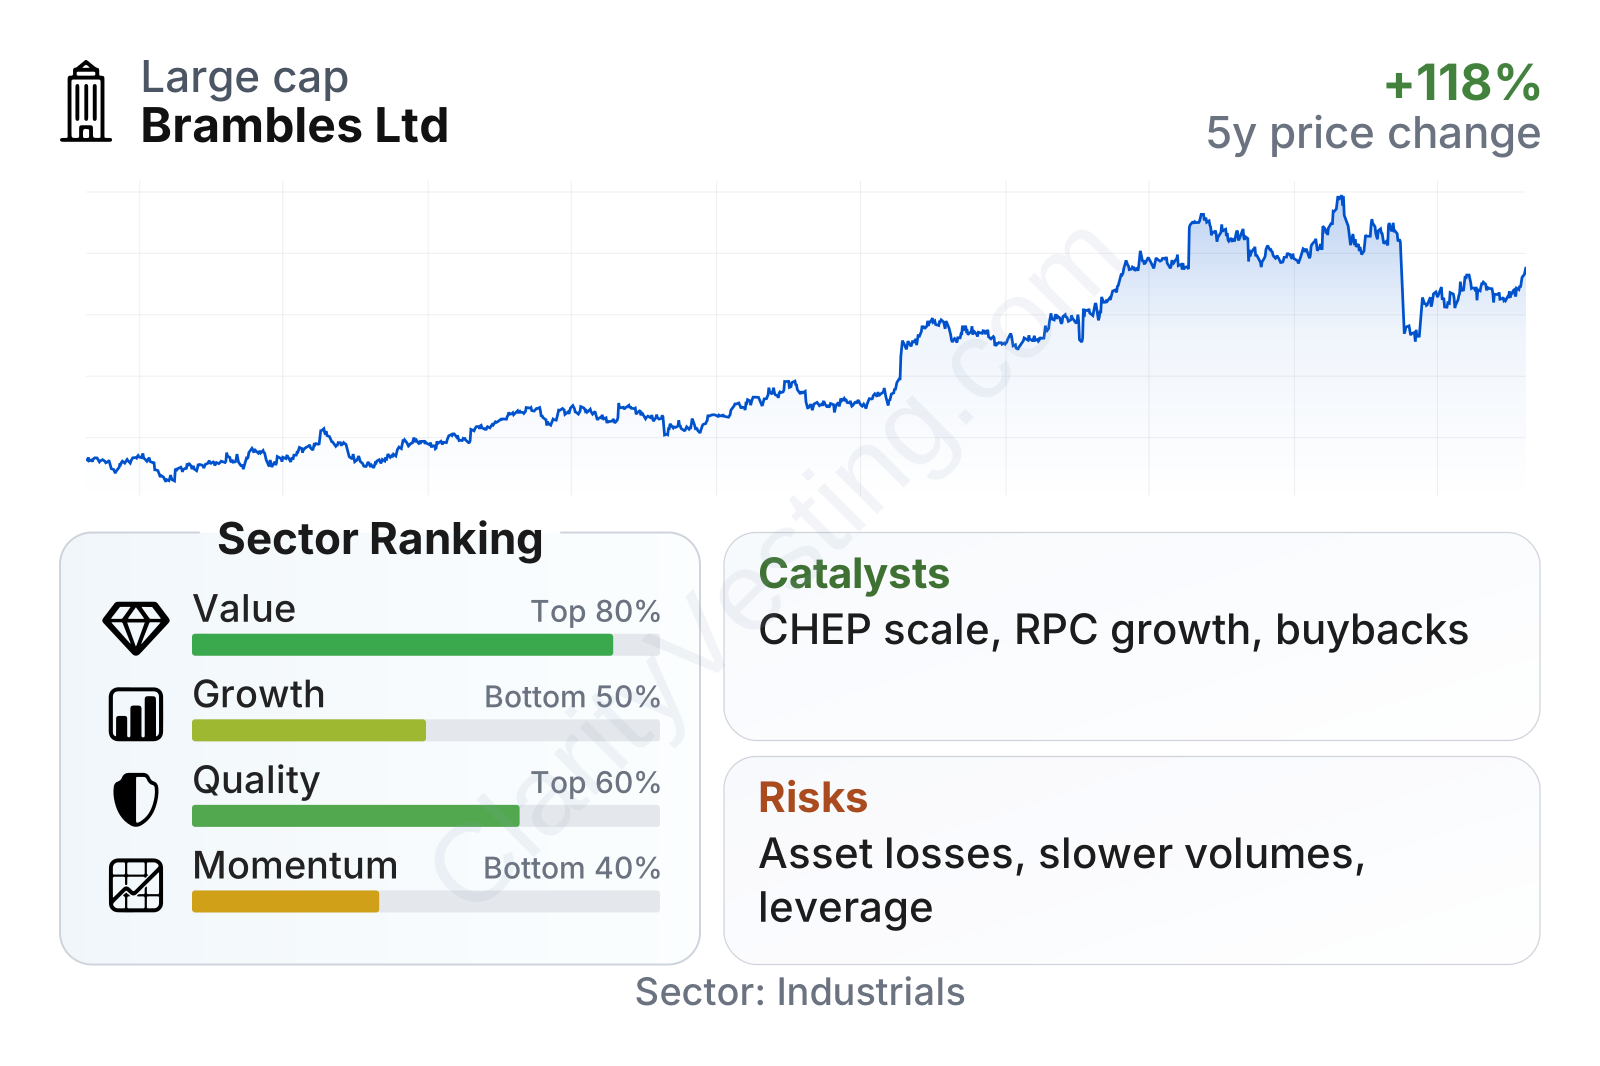
Brambles is a large industrial services company with a comparatively low share-price sensitivity to broad market swings, as suggested by its beta well below 1. On valuation, the earnings multiple sits below the sector median, while cash generation metrics look stronger than many peers. Quality indicators are solid overall: operating margin and profit margin are clearly ahead of the sector median, and interest coverage is healthy. The weaker area is growth, where revenue expansion has been positive but slower than the broader sector. Market momentum has also softened recently, with the shares pulling back from earlier highs.
Growth
Brambles operates in a structurally attractive niche. Reusable transport packaging fits well with long-term trends in supply-chain efficiency, cost control, and sustainability. Large manufacturers and retailers increasingly want systems that reduce product loss, improve asset tracking, and cut single-use packaging. Those trends support demand for pallet pooling and reusable containers over time.
The company’s strategy also makes industrial sense. Its network becomes more valuable as density increases: the more customers, service centers, and transport lanes it has, the easier it is to reposition assets efficiently and keep utilization high. That scale advantage can support pricing, customer retention, and margin resilience.
Revenue growth has moderated from stronger periods seen earlier in the cycle, and the latest yearly pace is around the mid-single-digit range. That is not fast for the sector, but it is consistent with a mature infrastructure-like business serving staple supply chains. For Brambles, the more important issue is whether moderate sales growth can continue to translate into stronger cash flow and steady earnings expansion.
That is where the company looks more compelling. Free cash flow has improved significantly over the past several years, and the latest trailing twelve-month figure is substantial for a business of this size. This matters because Brambles must continually invest in pallets and containers, so healthy cash conversion is a sign that the model is functioning efficiently.
Potential catalysts are tied less to breakthrough products and more to operational execution. Expansion of reusable plastic containers, deeper penetration with large retail and consumer goods customers, productivity gains from digital asset tracking, and continued supply-chain standardization can all support growth. Recent company updates have also emphasized ongoing share buybacks, pricing discipline, and efficiency programs, which can reinforce per-share progress even if headline revenue growth stays moderate.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


