Stock Analysis · Bioventus Inc (BVS)
Overview
Bioventus Inc is a medical device company focused on products used in orthopedics and wound care. In simple terms, it sells devices and therapies that aim to help bones heal, reduce joint pain, improve mobility, and support the treatment of hard-to-heal wounds. Its portfolio is centered on areas where doctors often look for non-drug and non-surgical or surgery-supporting solutions, especially for patients with osteoarthritis, fractures, and chronic wounds.
The business is organized around two main operating segments. Based on the latest annual filing, revenue is led by Pain Treatments and then Restorative Therapies. The mix can shift somewhat from year to year, but the broad breakdown is:
- Pain Treatments: approximately 55% to 60% of revenue. This segment mainly includes joint pain injection products, especially hyaluronic acid-based therapies used for knee osteoarthritis.
- Restorative Therapies: approximately 40% to 45% of revenue. This includes bone stimulation devices, ultrasonic products for bone healing, and advanced wound care offerings.
That structure matters because it shows Bioventus is not a one-product company, but it is still meaningfully exposed to a few important categories. Over the last several years, revenue moved from about $431 million in 2021 to about $568 million in 2025, while profitability improved sharply after a difficult period marked by losses and restructuring. The business model also carries healthy gross profit, but selling and administrative costs have historically taken up a large share of revenue, which has made execution especially important.
The long-term pattern is a recovery rather than a straight-line expansion. Revenue has grown since 2021, gross profit has remained strong, and operating results turned positive again in 2025 after deep losses in 2022 and 2023. Interest expense also eased in 2025, which supports the improvement in net income.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 31, 2026 | |
| Context | ||
| Sector | Healthcare | |
| Industry | Medical Devices | |
| Market Cap ⓘ | $1.02B | |
| Beta ⓘ | 0.64 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 19.06 | 24.88 |
| P/B Ratio ⓘ | 5.88 | 3.16 |
| FCF Yield ⓘ | 9.28% | 2.92% |
| Dividend Yield ⓘ | N/A | 1.78% |
| EBIT / EV ⓘ | 4.74% | 0.56% |
| PEG ⓘ | 1.53 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 3.80% | 7.50% |
| RPS Growth (5Y CAGR) ⓘ | -3.42% | 8.46% |
| EPS Growth (5Y CAGR) ⓘ | 25.07% | -17.36% |
| BVPS Growth (5Y CAGR) ⓘ | -30.00% | 3.71% |
| Margin Growth (5Y Trend) ⓘ | N/A | -0.61% |
| FCF Growth (5Y CAGR) ⓘ | 46.22% | 1.10% |
| DPS Growth (5Y CAGR) ⓘ | 1.89% | 6.66% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 18.20% | 5.22% |
| ROA (Latest) ⓘ | 7.92% | 3.01% |
| ROIC (5Y Median) ⓘ | -1.53% | 4.52% |
| ROA (5Y Median) ⓘ | -4.36% | 1.85% |
| Net Debt / EBIT (Latest) ⓘ | 4.00 | 1.34 |
| Net Debt / EBIT (5Y Median) ⓘ | N/A | 1.84 |
| Net Debt / EBITDA (Latest) ⓘ | 2.26 | 0.98 |
| Net Debt / Assets ⓘ | 34.80% | 4.48% |
| EBITDA / Interest ⓘ | 5.22 | 9.65 |
| Operating Margin (Latest) ⓘ | 10.06% | 9.44% |
| Operating Margin (5Y Median) ⓘ | -1.80% | 7.33% |
| Debt to Equity (Latest) ⓘ | 115.52% | 27.22% |
| Profit Margin (Latest) ⓘ | 9.36% | 3.41% |
| Free Cash Flow (Latest) ⓘ | $94.29M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +320.06% | +55.86% |
| 12M Return (excl. last month) ⓘ | +111.48% | +16.75% |
| 6M Return ⓘ | +53.77% | +14.89% |
| Price vs. 200-Day MA ⓘ | +36.76% | +7.77% |
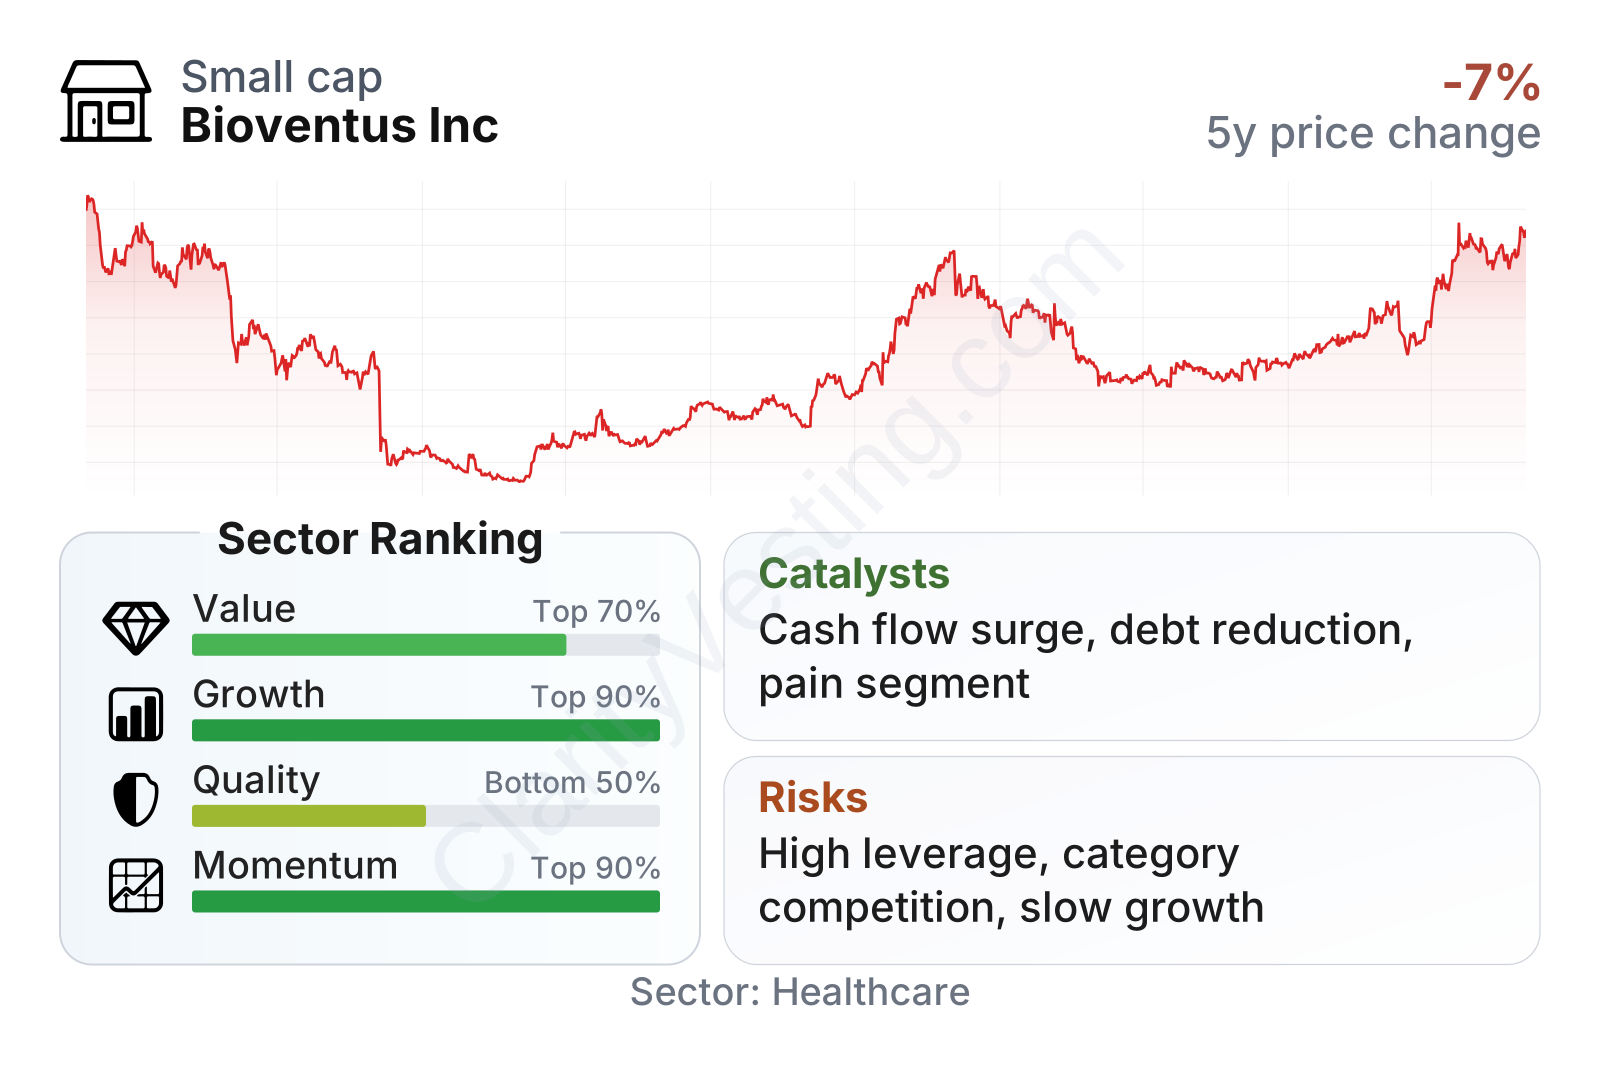
Bioventus is a small-to-mid-sized healthcare company with a market value around $1 billion and a stock that has been far less volatile than many smaller medical device names, as reflected by a beta below 1. The recent factor profile is unusual: momentum and cash-generation measures look strong, while balance-sheet quality remains weaker than the sector. Valuation metrics are mixed, with earnings and cash-flow measures looking relatively moderate, but book-value-based valuation appearing richer because the company’s equity base has been pressured by past losses and debt.
The stock chart shows how dramatic the turnaround has been. Shares fell sharply from 2021 into 2023, then rebounded strongly through 2024 and 2026. That kind of recovery usually means the market has shifted from worrying about survival and execution to focusing more on normalization, debt reduction, and steadier profitability.
Growth
Bioventus operates in healthcare niches that still have room for structural growth. Osteoarthritis remains a large and expanding market because populations are aging and staying active longer. Bone healing and wound care also benefit from demographic demand, rising rates of diabetes and mobility-related conditions, and a broader push toward treatments that can improve outcomes while limiting more invasive interventions.
The company’s strategy is sensible if viewed through that lens. It is not trying to compete across all of medical technology. Instead, it is concentrating on a narrower set of musculoskeletal and wound-care categories where physician relationships, reimbursement know-how, and commercial reach matter. That focus can work well for a smaller company, especially if management can keep costs under control and steadily improve cross-selling across the product portfolio.
Growth has not been perfectly smooth. Revenue expansion was strong in 2024, then slowed and briefly dipped in parts of 2025, before returning to modest positive growth in 2026. That recent pattern suggests the company is no longer in a rapid post-restructuring rebound, but it is still showing signs of forward progress. The latest year-over-year pace is below the healthcare sector median, so the market is likely looking for proof that the current product mix can deliver more consistent expansion.
One of the most encouraging developments is cash generation. Free cash flow improved from very low levels to roughly $100 million on a trailing basis by early 2026. For a company of this size, that is meaningful because it can support debt reduction, product investment, and operational flexibility without relying heavily on new financing. Stronger cash conversion is often one of the clearest signs that a turnaround is becoming more durable.
Recent company updates have also pointed to continued emphasis on commercial execution, margin improvement, and balance-sheet repair. For Bioventus, the clearest catalysts are not headline-grabbing breakthroughs but rather steady progress in pain treatments, continued demand in bone stimulation and wound care, and the ability to translate revenue into cash and earnings more efficiently than in the past.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


