Stock Analysis · Compania de Minas Buenaventura SAA (BVN)
Overview
Compania de Minas Buenaventura S.A.A. is one of Peru’s best-known mining groups. The company explores, develops, and operates mines, with a portfolio centered on precious metals such as gold and silver, while also producing base metals including copper, zinc, and lead. In addition to its wholly owned and controlled operations, it also has interests in joint ventures and associated mining assets in Peru. That structure means reported results can be shaped not only by metal prices and mine performance, but also by gains, dividends, and earnings from investments in other mining businesses.
Its revenue mix can move meaningfully from year to year because mining output, realized prices, and by-product credits fluctuate. Based on the company’s recent annual reporting, the main operating revenue sources are roughly organized as follows:
- Gold: approximately 35% to 45% of revenue in recent periods. This includes doré bars and concentrate-related gold content from operations such as Yumpag, Tambomayo, and other producing assets.
- Silver: approximately 20% to 30%. Silver is a core product for Buenaventura and also an important by-product at several mines.
- Copper: approximately 15% to 25%. Copper has become more relevant as the company advances and monetizes assets with stronger exposure to the energy-transition metal complex.
- Zinc: approximately 5% to 10%. Zinc is mainly tied to polymetallic ore bodies.
- Lead: approximately 3% to 8%. Lead is generally produced alongside zinc and silver in polymetallic operations.
- Other mining-related income: a smaller portion tied to treatment terms, by-products, services, and the impact of equity-accounted investments or asset transactions, depending on the year.
What matters for long-term analysis is that Buenaventura is not a single-mine business. It combines producing assets, development projects, and strategic stakes in other operations. That gives it more than one path to create value, but it also makes the business less straightforward than a pure-play miner focused on one metal.
The recent improvement in the company’s operating profile has been notable. Revenue rose sharply in 2024 and 2025, while costs grew more slowly, leading to a much stronger operating result and a clear jump in net income. That suggests the business has moved into a more favorable phase, helped by both execution and commodity prices.
The income flow shows a major change versus the weak 2021–2023 period: sales expanded strongly in 2024 and 2025, gross profit widened much faster than overhead, and earnings turned from uneven to robust. The key takeaway is that recent profitability has not come only from higher sales, but from much better operating leverage.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Other Precious Metals & Mining | |
| Market Cap ⓘ | $8.00B | |
| Beta ⓘ | 0.42 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 7.16 | 16.90 |
| P/B Ratio ⓘ | 1.79 | 1.65 |
| FCF Yield ⓘ | 8.20% | 5.76% |
| Dividend Yield ⓘ | 3.60% | 2.13% |
| EBIT / EV ⓘ | 13.88% | 6.30% |
| PEG ⓘ | 1.11 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 43.20% | 11.10% |
| RPS Growth (5Y CAGR) ⓘ | 17.76% | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | 40.11% | -13.47% |
| BVPS Growth (5Y CAGR) ⓘ | 11.02% | 5.51% |
| Margin Growth (5Y Trend) ⓘ | 42.09% | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 0.37% |
| DPS Growth (5Y CAGR) ⓘ | 56.65% | 6.08% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 9.26% |
| ROA (Latest) ⓘ | 19.29% | 4.91% |
| ROIC (5Y Median) ⓘ | 7.63% | 7.70% |
| ROA (5Y Median) ⓘ | 8.41% | 3.86% |
| Net Debt / EBIT (Latest) ⓘ | -0.06 | 1.40 |
| Net Debt / EBIT (5Y Median) ⓘ | 1.50 | 1.70 |
| Net Debt / EBITDA (Latest) ⓘ | -0.05 | 0.95 |
| Net Debt / Assets ⓘ | -1.07% | 13.69% |
| EBITDA / Interest ⓘ | 18.22 | 12.34 |
| Operating Margin (Latest) ⓘ | 49.50% | 13.20% |
| Operating Margin (5Y Median) ⓘ | 20.43% | 11.80% |
| Debt to Equity (Latest) ⓘ | 16.01% | 40.56% |
| Profit Margin (Latest) ⓘ | 48.22% | 6.43% |
| Free Cash Flow (Latest) ⓘ | $656.22M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +285.99% | +68.89% |
| 12M Return (excl. last month) ⓘ | +71.30% | +30.21% |
| 6M Return ⓘ | -16.29% | -4.16% |
| Price vs. 200-Day MA ⓘ | -9.16% | -1.27% |
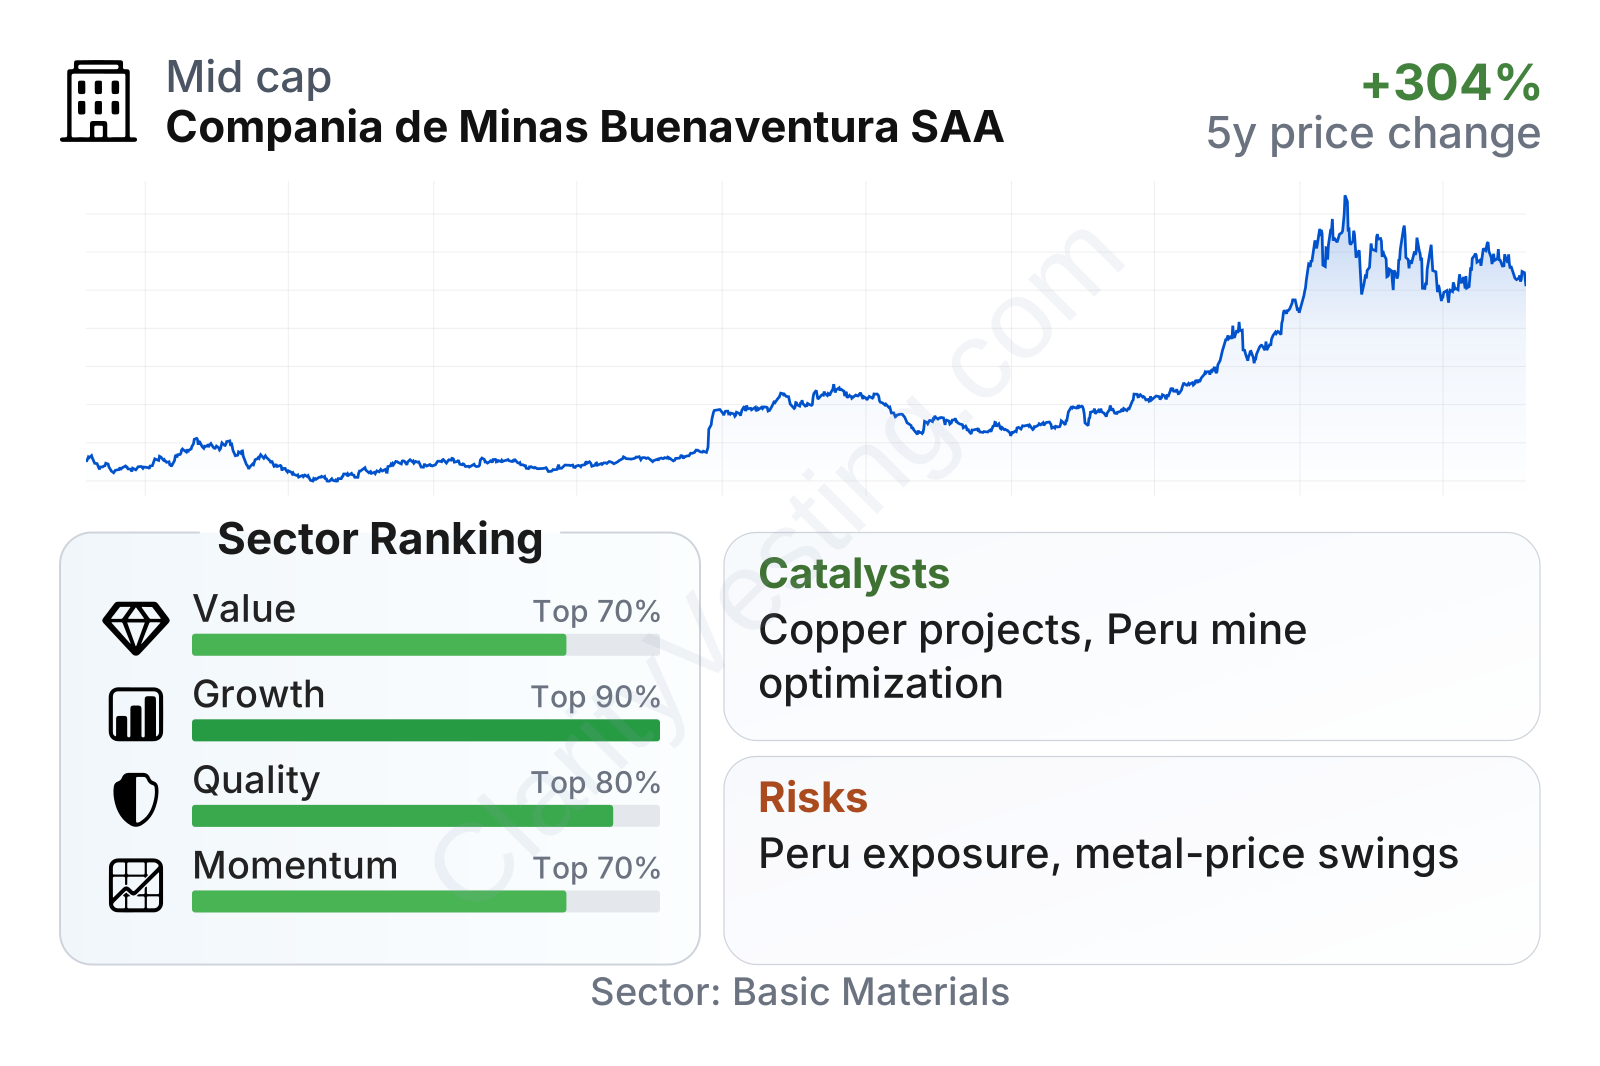
Buenaventura sits in the large-cap range for its niche and its share price has had a strong multi-year re-rating, although with noticeable volatility. The latest factor profile is broadly favorable: growth ranks near the top of the sector, value metrics remain undemanding relative to peers, and balance-sheet quality looks strong. Profitability and cash generation have improved enough that the company now screens better than many mining peers on both earnings power and financial resilience.
Growth
Buenaventura operates in a sector that still has long-term relevance. Gold and silver continue to benefit from central-bank demand, inflation hedging, and geopolitical uncertainty, while copper remains linked to electrification, grid investment, and infrastructure spending. That gives the company exposure to both defensive precious metals and industrial metals with structural demand support.
The company’s strategy also makes sense on paper. It combines cash flow from producing mines with a development pipeline and interests in larger assets that can become more valuable over time. In a mining business, that matters because mature mines eventually decline. A company that regularly replaces reserves, extends mine life, or advances new projects has a better chance of sustaining value across cycles.
Revenue growth has accelerated sharply since 2024 after a choppy earlier period. The recent pace is far above the sector median, which points to more than just stable metal prices. It indicates a mix of stronger production, better price realization, and a more favorable asset contribution profile.
Free cash flow has also turned decisively positive after several periods of negative readings. That shift is important because it shows the recent earnings improvement is being converted into actual cash, not only accounting profit. For a miner, stronger free cash flow can support project spending, dividends, debt reduction, and flexibility during weaker commodity periods.
One of the more visible catalysts is the company’s development portfolio in Peru, especially projects tied to copper and precious metals. Public company updates in 2026 have continued to emphasize progress at key growth assets and optimization at operating mines. If those projects advance on schedule, Buenaventura could become more diversified by metal and less dependent on any single operation.
Another important support factor is Peru itself. The country remains one of the world’s major mining jurisdictions for silver, copper, and gold. Permitting and social issues can be difficult, but the geological endowment is exceptional. For a local operator with long operating experience, that creates a large opportunity set that newer entrants may find harder to access.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


