Stock Analysis · BrightSpring Health Services Inc (BTSG)
Overview
BrightSpring Health Services is a healthcare services company focused on patients who need care outside the traditional hospital setting. Its activities are centered on home and community-based care, pharmacy services, rehabilitation, and support for people with complex or chronic conditions. The company serves a broad mix of patients, including seniors, people with disabilities, and individuals managing behavioral, respiratory, or specialty medication needs.
Its business is organized around two main operating segments, and public filings show that revenue is heavily concentrated in pharmacy and provider services delivered in lower-cost care settings.
- Pharmacy Solutions: approximately 70% to 75% of revenue in recent periods. This includes specialty pharmacy, infusion and other pharmacy-related services, often for patients with complex, recurring treatment needs.
- Provider Services: approximately 25% to 30% of revenue. This segment includes home health, hospice, personal care, rehabilitation, and community living or behavioral support services.
That mix matters because it gives BrightSpring exposure to two durable healthcare themes at once: rising demand for medications tied to complex conditions, and a long-term shift of care away from hospitals and into the home or community. Over the last several years, the company has also expanded revenue meaningfully, with total sales rising from about $6.7 billion in 2021 to about $12.9 billion in 2025. At the same time, interest expense has come down and net income turned positive in 2025, showing that scale is starting to translate into better bottom-line results.
The overall flow of revenue and expenses suggests a business with high volume but relatively thin margins, which is common in healthcare services. The more encouraging trend is that operating income improved in 2025 while interest costs moved lower, helping the company shift from losses in prior years to positive earnings.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Healthcare | |
| Industry | Health Information Services | |
| Market Cap ⓘ | $12.34B | |
| Beta ⓘ | 1.88 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 55.19 | 24.79 |
| P/B Ratio ⓘ | 6.74 | 3.08 |
| FCF Yield ⓘ | 3.26% | 3.15% |
| Dividend Yield ⓘ | N/A | 1.94% |
| EBIT / EV ⓘ | 3.71% | 0.57% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 23.00% | 7.45% |
| RPS Growth (5Y CAGR) ⓘ | 10.69% | 8.61% |
| EPS Growth (5Y CAGR) ⓘ | 91.91% | -17.81% |
| BVPS Growth (5Y CAGR) ⓘ | 17.00% | 3.72% |
| Margin Growth (5Y Trend) ⓘ | -1.21% | -0.62% |
| FCF Growth (5Y CAGR) ⓘ | 16.96% | 1.04% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 6.77% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 9.19% | 3.24% |
| ROA (Latest) ⓘ | 4.89% | 3.01% |
| ROIC (5Y Median) ⓘ | 3.68% | 4.60% |
| ROA (5Y Median) ⓘ | -0.32% | 1.89% |
| Net Debt / EBIT (Latest) ⓘ | 3.84 | 1.34 |
| Net Debt / EBIT (5Y Median) ⓘ | 15.90 | 1.84 |
| Net Debt / EBITDA (Latest) ⓘ | 2.88 | 1.00 |
| Net Debt / Assets ⓘ | 30.69% | 5.45% |
| EBITDA / Interest ⓘ | 4.20 | 9.64 |
| Operating Margin (Latest) ⓘ | 3.33% | 9.27% |
| Operating Margin (5Y Median) ⓘ | 2.29% | 7.38% |
| Debt to Equity (Latest) ⓘ | 116.54% | 28.58% |
| Profit Margin (Latest) ⓘ | 2.55% | 3.59% |
| Free Cash Flow (Latest) ⓘ | $402.35M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | N/A | +42.80% |
| 12M Return (excl. last month) ⓘ | +116.48% | +18.50% |
| 6M Return ⓘ | +35.54% | +7.57% |
| Price vs. 200-Day MA ⓘ | +16.66% | +5.12% |
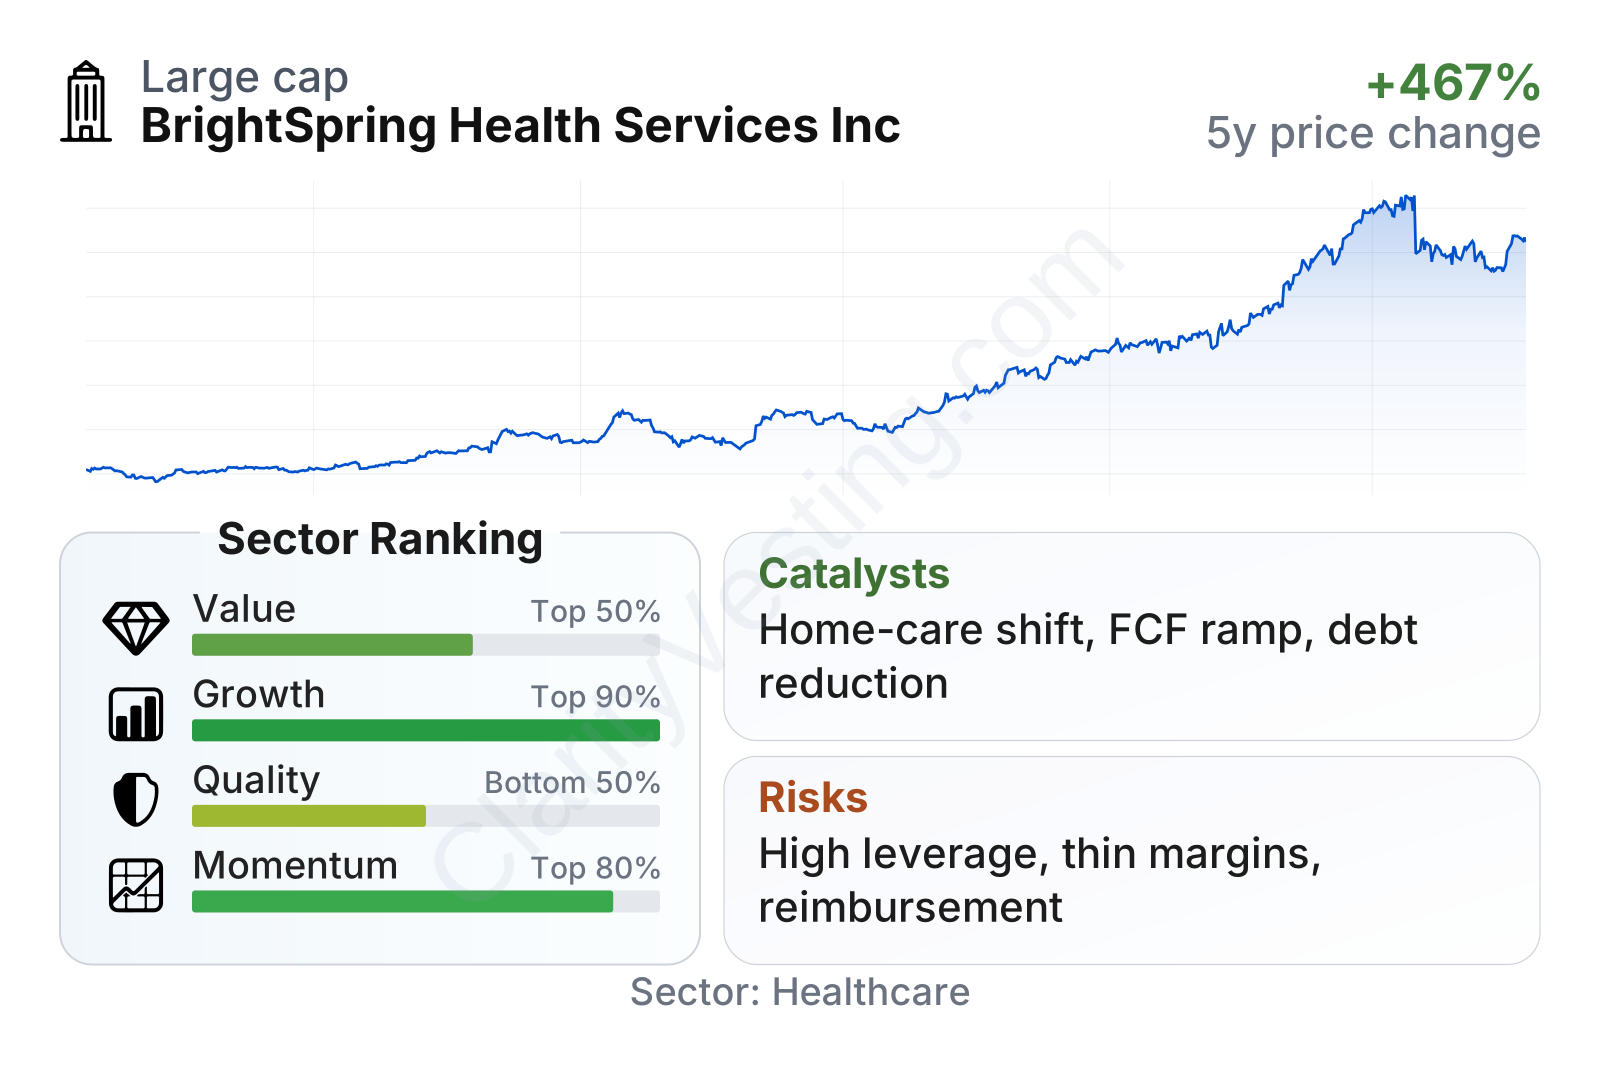
BrightSpring is now a large healthcare services company by market value, and the stock has had very strong momentum over the past year and a half. The metrics table points to a business that ranks well on growth and recent share performance, while quality remains mixed because leverage is still elevated and margins remain below many healthcare peers. On valuation, the picture is also mixed: earnings and book-value multiples are above sector medians, but cash-flow-based measures look more reasonable than the headline P/E ratio alone would suggest.
Growth
BrightSpring operates in areas of healthcare that appear structurally supported for years rather than quarters. An aging population, more patients living with chronic illness, pressure to reduce hospital stays, and payer interest in lower-cost treatment settings all support demand for home-based services, specialty pharmacy, infusion, and rehabilitation. These are not niche trends; they are part of a broader reorganization of how care is delivered in the U.S.
The company’s strategy fits those trends fairly well. It combines recurring pharmacy activity with hands-on provider services, allowing it to participate in both medication management and direct patient care. That can strengthen relationships with referral sources, improve coordination, and create more touchpoints with patients whose needs are ongoing rather than one-time.
Recent growth has been strong. Year-over-year revenue expansion has remained in roughly the mid-teens to high-20% range across the most recent reported quarters, clearly above the sector median. That does not automatically mean growth will stay at that pace, but it does show that BrightSpring has been capturing demand at a meaningful rate.
Cash generation has also improved sharply. Free cash flow moved from a low base to more than $400 million on a trailing basis, which is important because it gives the company more flexibility to reduce debt, invest in operations, and absorb reimbursement pressure. Stronger cash flow is especially relevant for a company that historically carried a meaningful debt load.
A further growth catalyst is execution on margin improvement. BrightSpring has already shown that revenue gains can be paired with better profitability than in earlier years. If management keeps improving operating discipline while maintaining growth in specialty pharmacy and home-based services, the earnings profile could continue to strengthen even if top-line growth moderates from recent highs.
Recent company communications and filings have also highlighted continued expansion in core service lines and ongoing demand for higher-acuity care delivered outside institutions. That backdrop supports the idea that the company is participating in a part of healthcare where volume growth can remain resilient.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


