Stock Analysis · Bellring Brands LLC (BRBR)
Overview
BellRing Brands is a packaged nutrition company focused on convenient, protein-centered foods and drinks. Its business is much narrower than a typical large food manufacturer: rather than selling many categories, it is concentrated in sports nutrition and ready-to-drink protein products. The company’s best-known brand is Premier Protein, and it also owns Dymatize. In simple terms, BellRing sells products aimed at consumers looking for protein for fitness, meal replacement, active lifestyles, and everyday wellness.
Revenue is heavily concentrated in branded nutrition products sold through retail, club, e-commerce, and other distribution channels. Based on company filings, the mix is dominated by Premier Protein, with Dymatize representing a much smaller share.
- Premier Protein: approximately 85% to 90% of net sales. This includes ready-to-drink protein shakes, powders, bars, and related nutritional products. The shake business is the largest piece.
- Dymatize: approximately 10% to 15% of net sales. This brand is more focused on powders and sports nutrition products used by fitness-oriented consumers.
The business model is relatively easy to understand: BellRing invests in brand building, product innovation, and retail distribution, then benefits when more consumers add protein products to their routine. Over the last several years, revenue and gross profit expanded materially, showing that sales growth translated into a larger profit base. At the same time, selling and marketing expenses also increased, which suggests the company is spending to support brand momentum and distribution reach.
The multi-year operating flow shows a strong rise in sales and gross profit from 2022 through 2025. Profitability improved meaningfully during that period, although marketing and administrative costs also climbed, which matters because this is a brand-driven category where shelf space and consumer awareness are critical.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 21, 2026 | |
| Context | ||
| Sector | Consumer Defensive | |
| Industry | Packaged Foods | |
| Market Cap ⓘ | $1.11B | |
| Beta ⓘ | 0.51 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 6.74 | 18.68 |
| P/B Ratio ⓘ | N/A | 1.24 |
| FCF Yield ⓘ | 20.35% | 12.11% |
| Dividend Yield ⓘ | N/A | 2.67% |
| EBIT / EV ⓘ | 15.10% | 6.40% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 4.20% | 4.10% |
| RPS Growth (5Y CAGR) ⓘ | -13.07% | 6.22% |
| EPS Growth (5Y CAGR) ⓘ | -7.37% | -13.59% |
| BVPS Growth (5Y CAGR) ⓘ | -53.80% | 3.27% |
| Margin Growth (5Y Trend) ⓘ | 2.08% | -0.13% |
| FCF Growth (5Y CAGR) ⓘ | 3.33% | 4.10% |
| DPS Growth (5Y CAGR) ⓘ | -50.47% | 6.83% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 34.57% | 12.34% |
| ROA (Latest) ⓘ | 17.20% | 6.30% |
| ROIC (5Y Median) ⓘ | 42.52% | 10.53% |
| ROA (5Y Median) ⓘ | 23.66% | 5.44% |
| Net Debt / EBIT (Latest) ⓘ | 3.48 | 1.98 |
| Net Debt / EBIT (5Y Median) ⓘ | 2.84 | 2.35 |
| Net Debt / EBITDA (Latest) ⓘ | 3.27 | 1.38 |
| Net Debt / Assets ⓘ | 103.12% | 21.70% |
| EBITDA / Interest ⓘ | 4.20 | 9.49 |
| Operating Margin (Latest) ⓘ | 13.25% | 8.88% |
| Operating Margin (5Y Median) ⓘ | 15.43% | 9.57% |
| Debt to Equity (Latest) ⓘ | -243.00% | 72.35% |
| Profit Margin (Latest) ⓘ | 7.28% | 5.40% |
| Free Cash Flow (Latest) ⓘ | $225.00M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | -77.90% | +24.53% |
| 12M Return (excl. last month) ⓘ | -75.06% | +1.93% |
| 6M Return ⓘ | -42.29% | +1.61% |
| Price vs. 200-Day MA ⓘ | -31.60% | +2.99% |
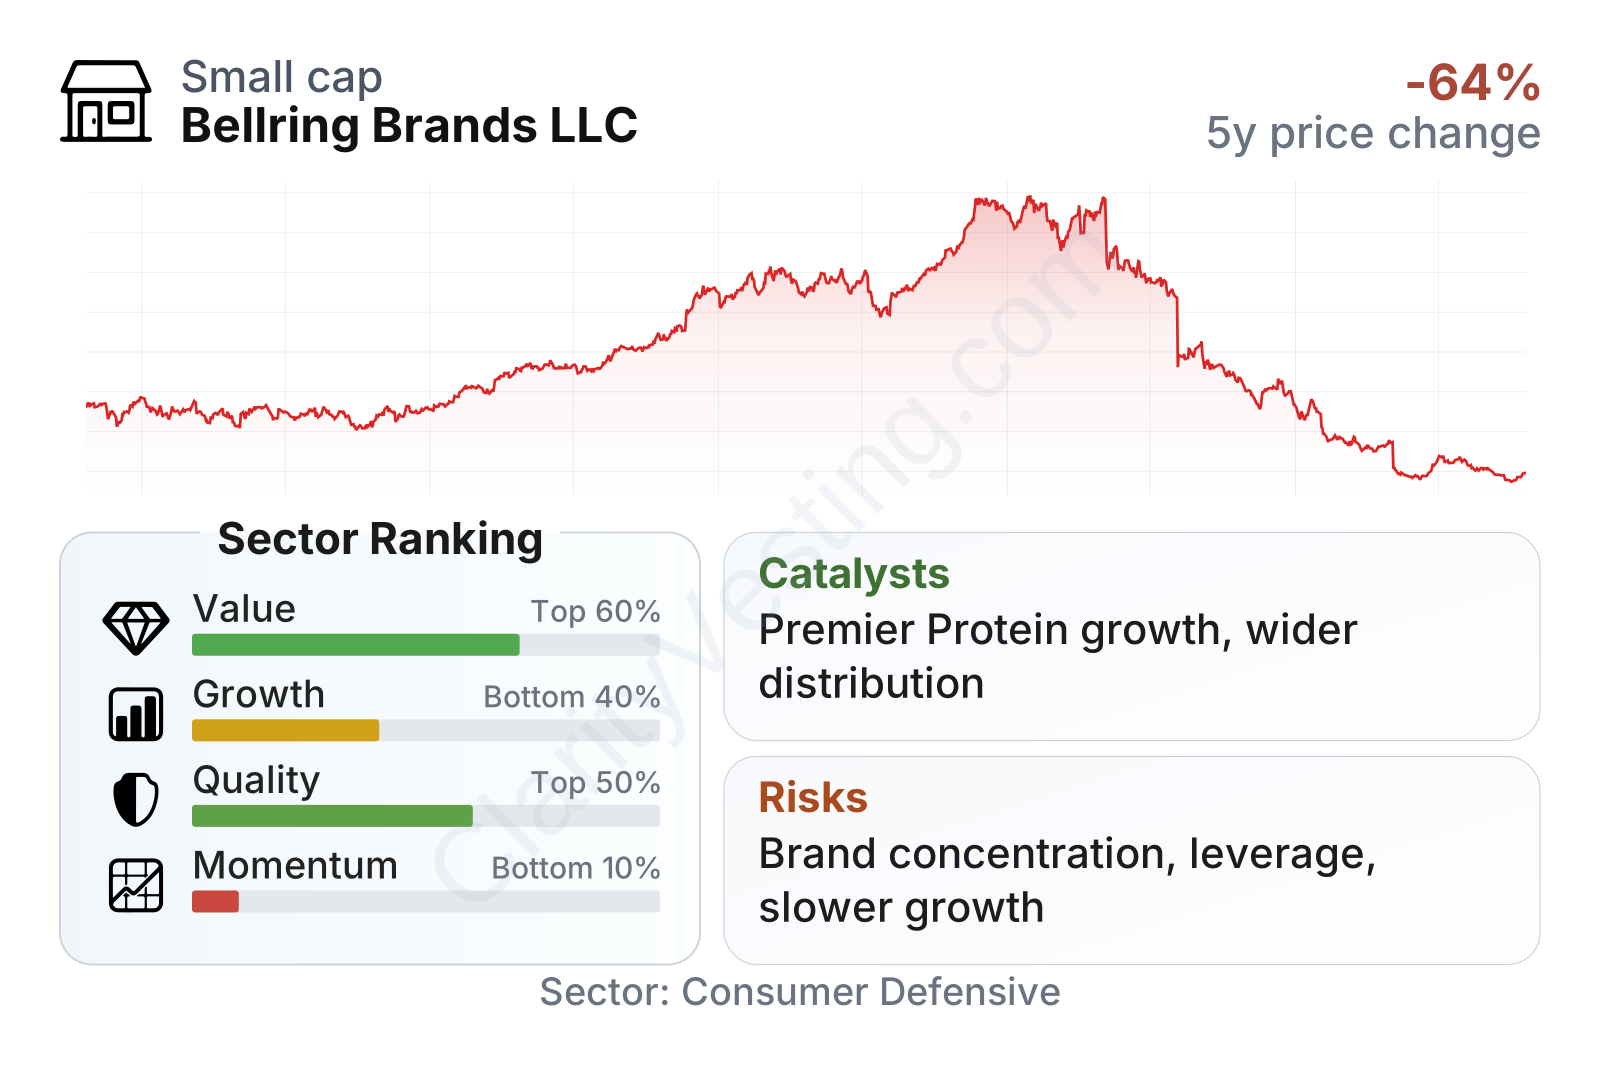
BellRing is a relatively small public company within the consumer staples universe, and its recent profile is unusual. On one hand, profitability and returns on capital are strong compared with much of the sector. On the other, recent market performance has been very weak, and leverage remains an important consideration. The value metrics currently screen favorably versus the sector median, while growth and momentum rank lower. That combination often signals a company the market has become more cautious about, despite still-solid operating economics.
Growth
BellRing operates in a category that still has attractive long-term demand drivers. Protein consumption has broadened well beyond athletes: it now reaches mainstream consumers interested in satiety, convenience, weight management, and healthier snacking. Ready-to-drink shakes are especially well positioned because they fit busy routines and are easier to use than traditional powders. That makes the sector more resilient than narrower sports nutrition niches.
The company’s strategy also makes sense for future growth. BellRing is centered on brands with strong recognition in protein shakes and sports nutrition, and it can expand through more retail distribution, product extensions, flavor innovation, and further household penetration. Because the business is focused rather than diversified, management can direct capital and marketing toward a category where it already has credibility.
Revenue growth was very strong through 2023, remained healthy for much of 2024 and 2025, and then slowed sharply entering 2026. More recently, year-over-year growth appears to have stabilized in the low-single-digit range. That suggests the business is still expanding, but the phase of exceptionally rapid growth has cooled.
Cash generation has been positive but uneven. Free cash flow rebounded strongly after a weak period and remains meaningful for a company of this size, although it has not followed a straight upward line. That matters because cash flow supports debt service, marketing investment, and strategic flexibility.
A notable catalyst is BellRing’s exposure to the ready-to-drink protein shake category, which remains one of the more attractive pockets of packaged nutrition. Another is the company’s ability to keep widening distribution with key retail partners while using brand strength to defend shelf space. If volume growth reaccelerates after the recent slowdown, operating leverage could improve because the business already runs at margins above many packaged food peers.
Recent company communications have also emphasized innovation, expanded distribution, and continued demand for convenient protein formats. For a focused company like BellRing, even moderate category share gains can have an outsized impact on results because nearly all of the business is tied to this one theme.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


