Stock Analysis · Belite Bio Inc (BLTE)
Overview
Belite Bio Inc is a clinical-stage biotechnology company focused on treatments for degenerative eye diseases with high unmet need. Its lead program is tinlarebant, an oral therapy designed to slow the buildup of toxic vitamin A byproducts in the eye. The company is primarily targeting Stargardt disease, a rare inherited retinal disorder that often affects children and young adults, and it is also studying the same drug candidate in geographic atrophy, an advanced form of dry age-related macular degeneration.
This is still a pre-commercial business. Based on its recent SEC filings, Belite Bio has not yet built a recurring product revenue base, so the investment case is centered on clinical progress rather than current sales.
The company’s revenue mix is therefore extremely simple at this stage.
- Product revenue: 0% of total revenue in recent annual reporting periods, because no therapy has been approved for commercial sale.
- Collaboration, licensing, or other operating revenue: effectively 0% in recent annual reporting periods.
- Cash resources from financing and prior capital raises: not revenue, but the main source of funding for operations while trials continue.
Belite Bio’s business model could change sharply if tinlarebant reaches approval. In that case, future revenue would likely be concentrated first in rare-disease ophthalmology, where pricing can be strong and specialist distribution is more focused than in mass-market medicine.
The operating profile remains typical for a development-stage biotech: essentially no revenue, rising research spending, and widening losses as late-stage studies expand. Research and development has been the largest expense line by a wide margin, although administrative costs also climbed materially in the latest period, showing that the organization is scaling ahead of potential commercialization and broader clinical activity.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Healthcare | |
| Industry | Biotechnology | |
| Market Cap ⓘ | $6.21B | |
| Beta ⓘ | -1.23 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | N/A | 24.79 |
| P/B Ratio ⓘ | 7.90 | 3.08 |
| FCF Yield ⓘ | -0.12% | 3.15% |
| Dividend Yield ⓘ | N/A | 1.94% |
| EBIT / EV ⓘ | -1.92% | 0.57% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | N/A | 7.45% |
| RPS Growth (5Y CAGR) ⓘ | N/A | 8.61% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -17.81% |
| BVPS Growth (5Y CAGR) ⓘ | N/A | 3.72% |
| Margin Growth (5Y Trend) ⓘ | N/A | -0.62% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 1.04% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 6.77% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 3.24% |
| ROA (Latest) ⓘ | -19.06% | 3.01% |
| ROIC (5Y Median) ⓘ | -30.61% | 4.60% |
| ROA (5Y Median) ⓘ | -40.40% | 1.89% |
| Net Debt / EBIT (Latest) ⓘ | N/A | 1.34 |
| Net Debt / EBIT (5Y Median) ⓘ | N/A | 1.84 |
| Net Debt / EBITDA (Latest) ⓘ | N/A | 1.00 |
| Net Debt / Assets ⓘ | N/A | 5.45% |
| EBITDA / Interest ⓘ | N/A | 9.64 |
| Operating Margin (Latest) ⓘ | N/A | 9.27% |
| Operating Margin (5Y Median) ⓘ | N/A | 7.38% |
| Debt to Equity (Latest) ⓘ | N/A | 28.58% |
| Profit Margin (Latest) ⓘ | N/A | 3.59% |
| Free Cash Flow (Latest) ⓘ | -$7.62M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +363.54% | +42.80% |
| 12M Return (excl. last month) ⓘ | +153.65% | +18.50% |
| 6M Return ⓘ | -9.56% | +7.57% |
| Price vs. 200-Day MA ⓘ | -5.16% | +5.12% |
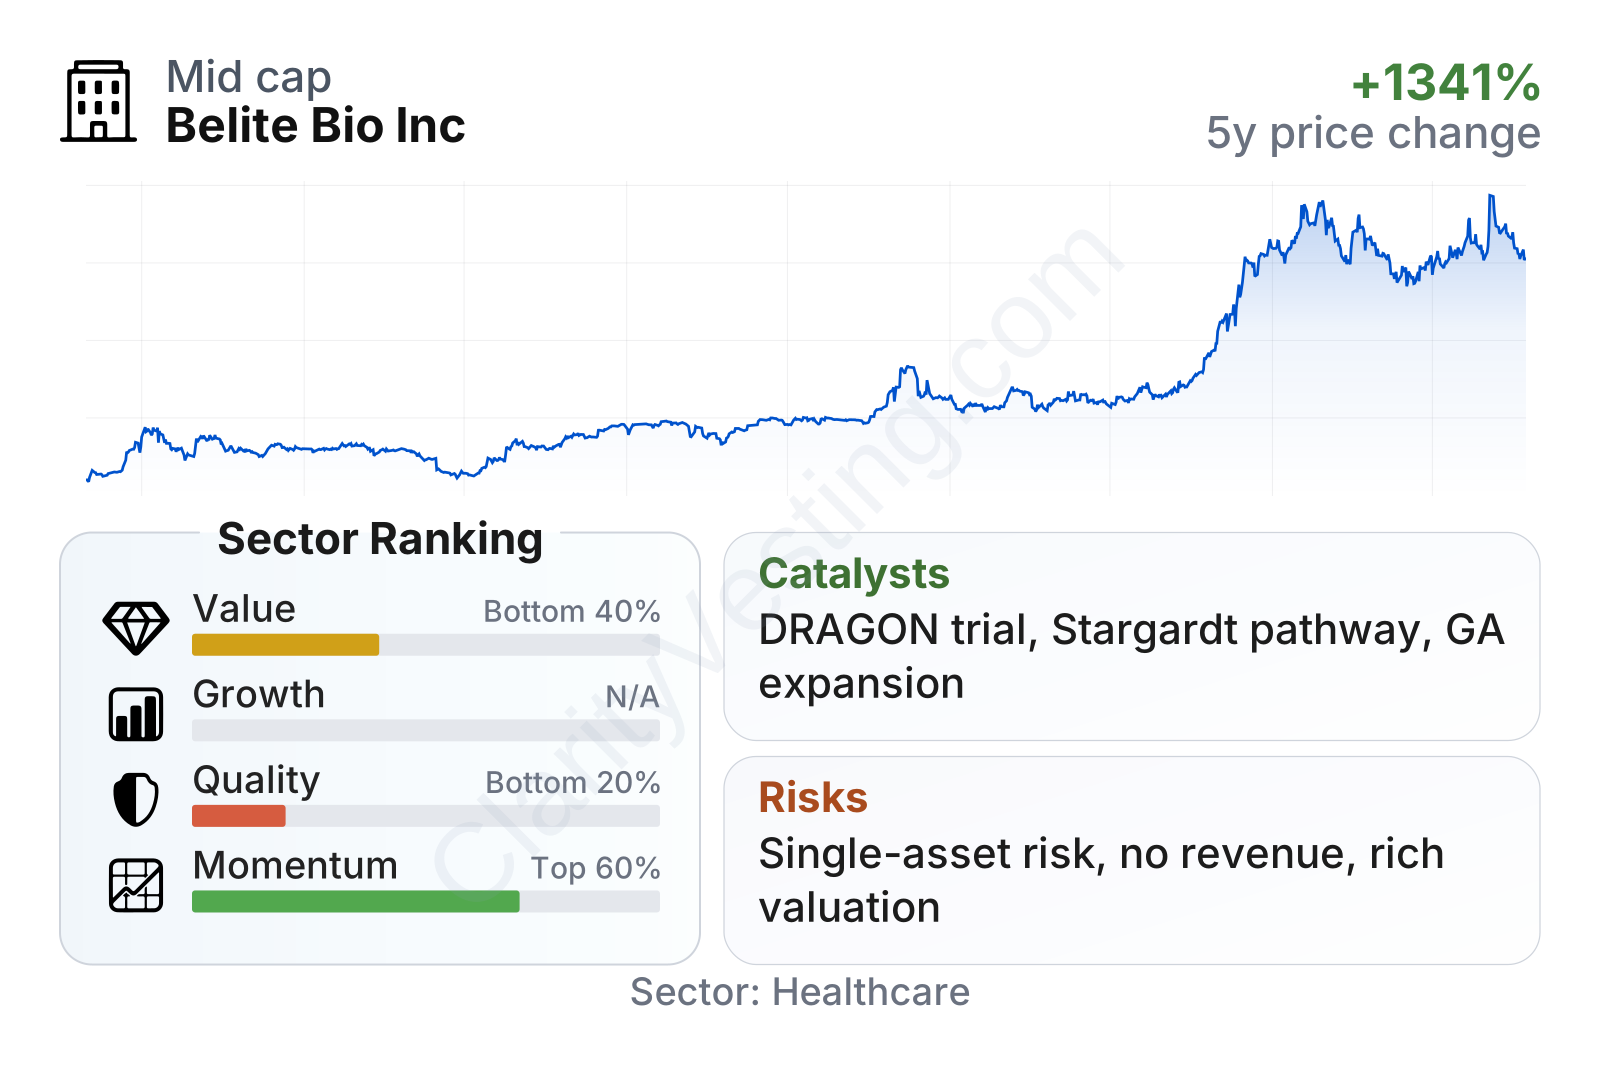
The market is valuing Belite Bio as a sizable biotech despite the absence of current sales, which explains why its value metrics screen as weaker than much of the healthcare sector. Quality measures are also below sector medians because profitability and returns on assets remain negative, a normal pattern for a company still funding trials rather than selling products. The notable outlier is share-price performance: the stock has dramatically outperformed most biotech peers over the last one to three years, signaling that expectations for the pipeline have risen sharply.
Belite Bio is also unusual in that it combines a high valuation with very low financial leverage. That means the balance sheet risk looks far better than the income statement risk. In simple terms, the company is not heavily indebted, but the current market value already reflects meaningful optimism around future clinical and regulatory milestones.
Growth
Belite Bio operates in an attractive part of healthcare. Retinal disease is a growing field because populations are aging, diagnosis is improving, and effective treatments for many forms of vision loss remain limited. Rare inherited eye diseases are especially important commercially because successful therapies can command premium pricing, gain orphan-drug support, and often face less crowded competition than broader primary-care markets.
The company’s strategy is coherent for long-term growth. Rather than running many unrelated projects, Belite Bio is concentrating resources on one mechanism and applying it across more than one retinal condition. That focus can be efficient if the science works: one drug candidate, one biological rationale, and potentially more than one commercial use. For a small biotech, that is usually a more disciplined approach than spreading capital across a large pipeline.
The main catalyst is straightforward: clinical readouts and regulatory progress for tinlarebant. A positive late-stage result in Stargardt disease would be especially important because it could move the company from a research narrative toward a possible commercial pathway. Geographic atrophy is also meaningful because it is a much larger market, even if it is more competitive and likely more challenging commercially.
Recent company communications have continued to emphasize advancement of the DRAGON trial in adolescent Stargardt disease and broader development work around tinlarebant. In a company like Belite Bio, that matters more than short-term accounting trends. The share price’s strong multi-year run suggests the market has been reacting primarily to progress in the clinic and to the perceived scarcity value of a potentially differentiated oral retinal therapy.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


