Stock Analysis · BillionToOne Inc (BLLN)
Overview
BillionToOne is a molecular diagnostics company focused on blood-based tests. In simple terms, it develops lab tests that look at DNA signals in a blood sample to help detect genetic conditions or cancer. The company is best known for prenatal testing, where its products are used during pregnancy, and it is also expanding into oncology, especially blood-based cancer screening and monitoring.
Its business model is mainly test-based revenue. Physicians order the company’s tests, samples are processed in its laboratory network, and revenue is recognized from delivering those diagnostic services. Based on recent company reporting and product focus, the main revenue sources appear to be:
- Prenatal diagnostics: approximately the large majority of current revenue. This includes non-invasive prenatal screening products such as UNITY, which is designed to assess fetal risk from a maternal blood sample and reduce the need for paternal samples in some cases.
- Oncology diagnostics: currently a smaller but growing share of revenue. This includes tests tied to cancer detection and disease monitoring, with the business still in expansion mode compared with the more established prenatal franchise.
- Other and collaboration-related activity: limited contribution where applicable, including smaller ancillary sources linked to testing services or partnerships.
The broad financial direction has improved sharply over the last three years. Revenue rose from roughly $72 million in 2023 to about $153 million in 2024 and then to about $305 million in 2025. Over the same period, gross profit expanded strongly and the company moved from heavy losses to modest profitability in 2025. That matters because it suggests BillionToOne is no longer operating only as an early-stage growth company; it is beginning to show that scale can translate into earnings.
Even so, the company remains concentrated around a narrow set of products in specialized healthcare markets. That gives it focus, but also means future results still depend heavily on continued adoption of a relatively small number of tests.
The income profile shows a meaningful operating shift. Revenue and gross profit have climbed much faster than costs, while research and commercial spending have also increased to support expansion. The key change is that the business crossed from operating losses in 2023 and 2024 to positive operating income in 2025, which is an important sign of improving scale.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 03, 2026 | |
| Context | ||
| Sector | Healthcare | |
| Industry | Diagnostics & Research | |
| Market Cap ⓘ | $5.02B | |
| Beta ⓘ | N/A | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 149.92 | 24.06 |
| P/B Ratio ⓘ | 10.73 | 3.08 |
| FCF Yield ⓘ | 0.66% | 3.07% |
| Dividend Yield ⓘ | N/A | 2.05% |
| EBIT / EV ⓘ | 0.76% | 0.63% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 64.40% | 7.50% |
| RPS Growth (5Y CAGR) ⓘ | 103.69% | 8.70% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -18.20% |
| BVPS Growth (5Y CAGR) ⓘ | 291.83% | 3.95% |
| Margin Growth (5Y Trend) ⓘ | N/A | -0.58% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 0.88% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 6.80% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 9.58% | 3.29% |
| ROA (Latest) ⓘ | 6.34% | 3.02% |
| ROIC (5Y Median) ⓘ | N/A | 4.75% |
| ROA (5Y Median) ⓘ | N/A | 1.93% |
| Net Debt / EBIT (Latest) ⓘ | -10.67 | 1.33 |
| Net Debt / EBIT (5Y Median) ⓘ | N/A | 1.83 |
| Net Debt / EBITDA (Latest) ⓘ | -8.05 | 0.99 |
| Net Debt / Assets ⓘ | -55.46% | 5.33% |
| EBITDA / Interest ⓘ | 1,225.49 | 9.63 |
| Operating Margin (Latest) ⓘ | 9.55% | 9.25% |
| Operating Margin (5Y Median) ⓘ | -25.66% | 7.80% |
| Debt to Equity (Latest) ⓘ | 26.81% | 28.99% |
| Profit Margin (Latest) ⓘ | 8.35% | 3.60% |
| Free Cash Flow (Latest) ⓘ | $33.17M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | N/A | +37.48% |
| 12M Return (excl. last month) ⓘ | N/A | +20.85% |
| 6M Return ⓘ | +27.48% | +9.73% |
| Price vs. 200-Day MA ⓘ | +11.16% | +4.69% |
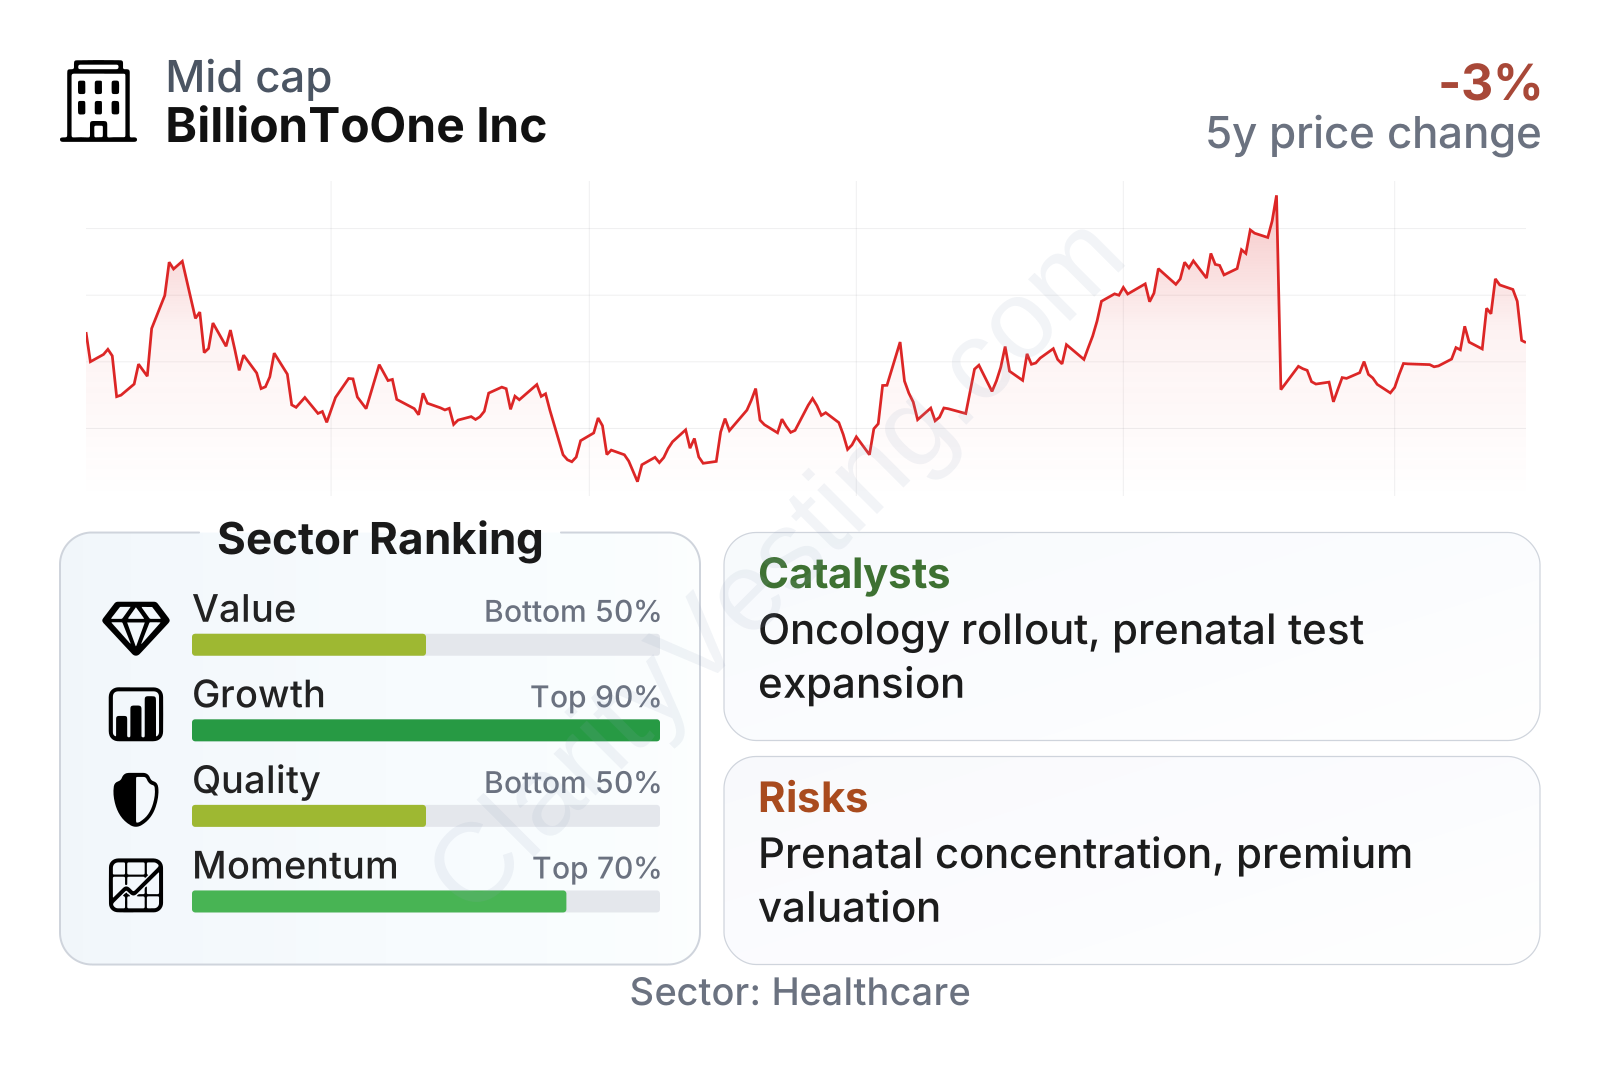
BillionToOne currently stands out much more on growth and market momentum than on traditional valuation measures. Revenue growth is far above the sector median, and the share price trend over the last six months has also been much stronger than most healthcare peers. Profitability metrics are mixed but improving: recent returns on capital and assets are above sector medians, while the broader quality ranking remains closer to the middle because the company is still early in its profit cycle. Valuation is the weak point in the snapshot, with earnings and book value multiples well above sector norms and free cash flow yield below the typical healthcare peer.
The stock path over the last year suggests a volatile but overall resilient market view. The shares have moved up and down in wide ranges rather than following a straight line, which is common for fast-growing diagnostics businesses where expectations can change quickly after new product, reimbursement, or clinical updates.
Growth
BillionToOne operates in a part of healthcare with durable long-term demand drivers. Prenatal genetic screening benefits from continued use of non-invasive testing in obstetrics, while oncology diagnostics is supported by the broader shift toward earlier detection, personalized treatment decisions, and blood-based monitoring. These are attractive segments because they combine medical need, recurring test volume, and room for innovation.
The company’s strategy is coherent. In prenatal testing, it has tried to differentiate its platform by addressing limitations of older screening approaches and by making testing easier to use in clinical practice. In oncology, the opportunity is larger but more competitive, and management appears to be using the prenatal business as the financial base to fund expansion into cancer testing. That kind of sequencing can make sense because it reduces dependence on external financing if the core franchise remains strong.
Recent financial progress supports the growth case. Revenue growth of about 64% year over year is far above the sector median, and the company has already shown that rapid expansion is not purely theoretical. The move to positive net income in 2025 is especially important because it suggests operating leverage is beginning to emerge rather than growth being purchased entirely through rising expenses.
A major catalyst is the possibility that oncology becomes a much more material contributor over time. If BillionToOne can turn its cancer programs into meaningful commercial adoption, the revenue mix could become broader and the company’s addressable market could expand substantially beyond prenatal testing. Additional coverage decisions, physician adoption, and clinical validation updates could all strengthen that path.
Another favorable point is balance-sheet flexibility. The company’s net debt measures are negative, which indicates cash exceeds debt on those metrics. For a diagnostics company still scaling, that is useful because it gives management more room to invest in sales, research, and laboratory capacity without immediate pressure from leverage.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


