Stock Analysis · BELIMO Holding AG (BLHWF)
Overview
BELIMO Holding AG is a Swiss industrial company focused on devices that help control heating, ventilation, and air conditioning systems inside buildings. Its products are used to regulate air and water flows, improve energy efficiency, and support indoor air quality. In simple terms, BELIMO makes the components that allow commercial buildings, public facilities, and other non-residential properties to run their climate systems more precisely and with less wasted energy.
The business is centered on a narrow but important niche within building technology. That focus matters because building owners increasingly want lower energy consumption, better occupant comfort, and smarter control systems. BELIMO’s products are typically embedded in HVAC infrastructure, which can make the company relevant both in new construction and in retrofit projects where older systems are upgraded.
Based on the company’s recent annual reporting, BELIMO’s revenue mix is led by product categories rather than broad service lines.
- Control Valves: approximately 44% of revenue. These products regulate the flow of water in heating and cooling systems.
- Damper Actuators: approximately 35% of revenue. These actuators control air dampers in ventilation and air distribution systems.
- Sensors and Meters: approximately 21% of revenue. This segment includes devices that measure temperature, pressure, flow, and other variables used in building automation and energy management.
Geographically, BELIMO is diversified across major construction and retrofit markets, with the Americas representing the largest share, followed by EMEA, then Asia Pacific. That regional spread helps reduce dependence on a single country, although commercial building activity remains the main common driver across all markets.
The business model also stands out for its combination of specialized manufacturing, direct customer relationships, and a strong installed base in mission-critical building systems. Revenue has expanded steadily over the last several years, while profitability has remained strong, suggesting that BELIMO has been able to grow without giving up pricing discipline.
The long-term pattern points to rising revenue and improving operating income, with profits growing faster than sales in recent years. That usually signals a favorable mix of pricing, scale, and cost control, although yearly expense classifications can create some noise in the visual breakdown.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 22, 2026 | |
| Context | ||
| Sector | Industrials | |
| Industry | Building Products & Equipment | |
| Market Cap ⓘ | $11.35B | |
| Beta ⓘ | 1.14 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 43.90 | 22.29 |
| P/B Ratio ⓘ | 18.19 | 1.98 |
| FCF Yield ⓘ | 1.83% | 6.26% |
| Dividend Yield ⓘ | 1.08% | 1.92% |
| EBIT / EV ⓘ | N/A | 4.83% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 20.50% | 9.30% |
| RPS Growth (5Y CAGR) ⓘ | 10.02% | 7.76% |
| EPS Growth (5Y CAGR) ⓘ | -24.37% | -13.17% |
| BVPS Growth (5Y CAGR) ⓘ | 5.03% | 6.13% |
| Margin Growth (5Y Trend) ⓘ | 1.67% | 0.74% |
| FCF Growth (5Y CAGR) ⓘ | -0.35% | 10.79% |
| DPS Growth (5Y CAGR) ⓘ | 6.11% | 9.41% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 64.45% | 10.75% |
| ROA (Latest) ⓘ | 42.11% | 5.41% |
| ROIC (5Y Median) ⓘ | 26.56% | 9.37% |
| ROA (5Y Median) ⓘ | 20.53% | 4.95% |
| Net Debt / EBIT (Latest) ⓘ | 0.06 | 2.04 |
| Net Debt / EBIT (5Y Median) ⓘ | -0.55 | 2.27 |
| Net Debt / EBITDA (Latest) ⓘ | 0.05 | 1.39 |
| Net Debt / Assets ⓘ | 2.69% | 19.27% |
| EBITDA / Interest ⓘ | 47.93 | 9.58 |
| Operating Margin (Latest) ⓘ | 20.58% | 10.49% |
| Operating Margin (5Y Median) ⓘ | 18.77% | 10.30% |
| Debt to Equity (Latest) ⓘ | 20.92% | 64.82% |
| Profit Margin (Latest) ⓘ | 16.61% | 6.67% |
| Free Cash Flow (Latest) ⓘ | $207.42M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +128.46% | +67.77% |
| 12M Return (excl. last month) ⓘ | -18.99% | +12.05% |
| 6M Return ⓘ | +18.58% | 0.00% |
| Price vs. 200-Day MA ⓘ | N/A | +0.67% |
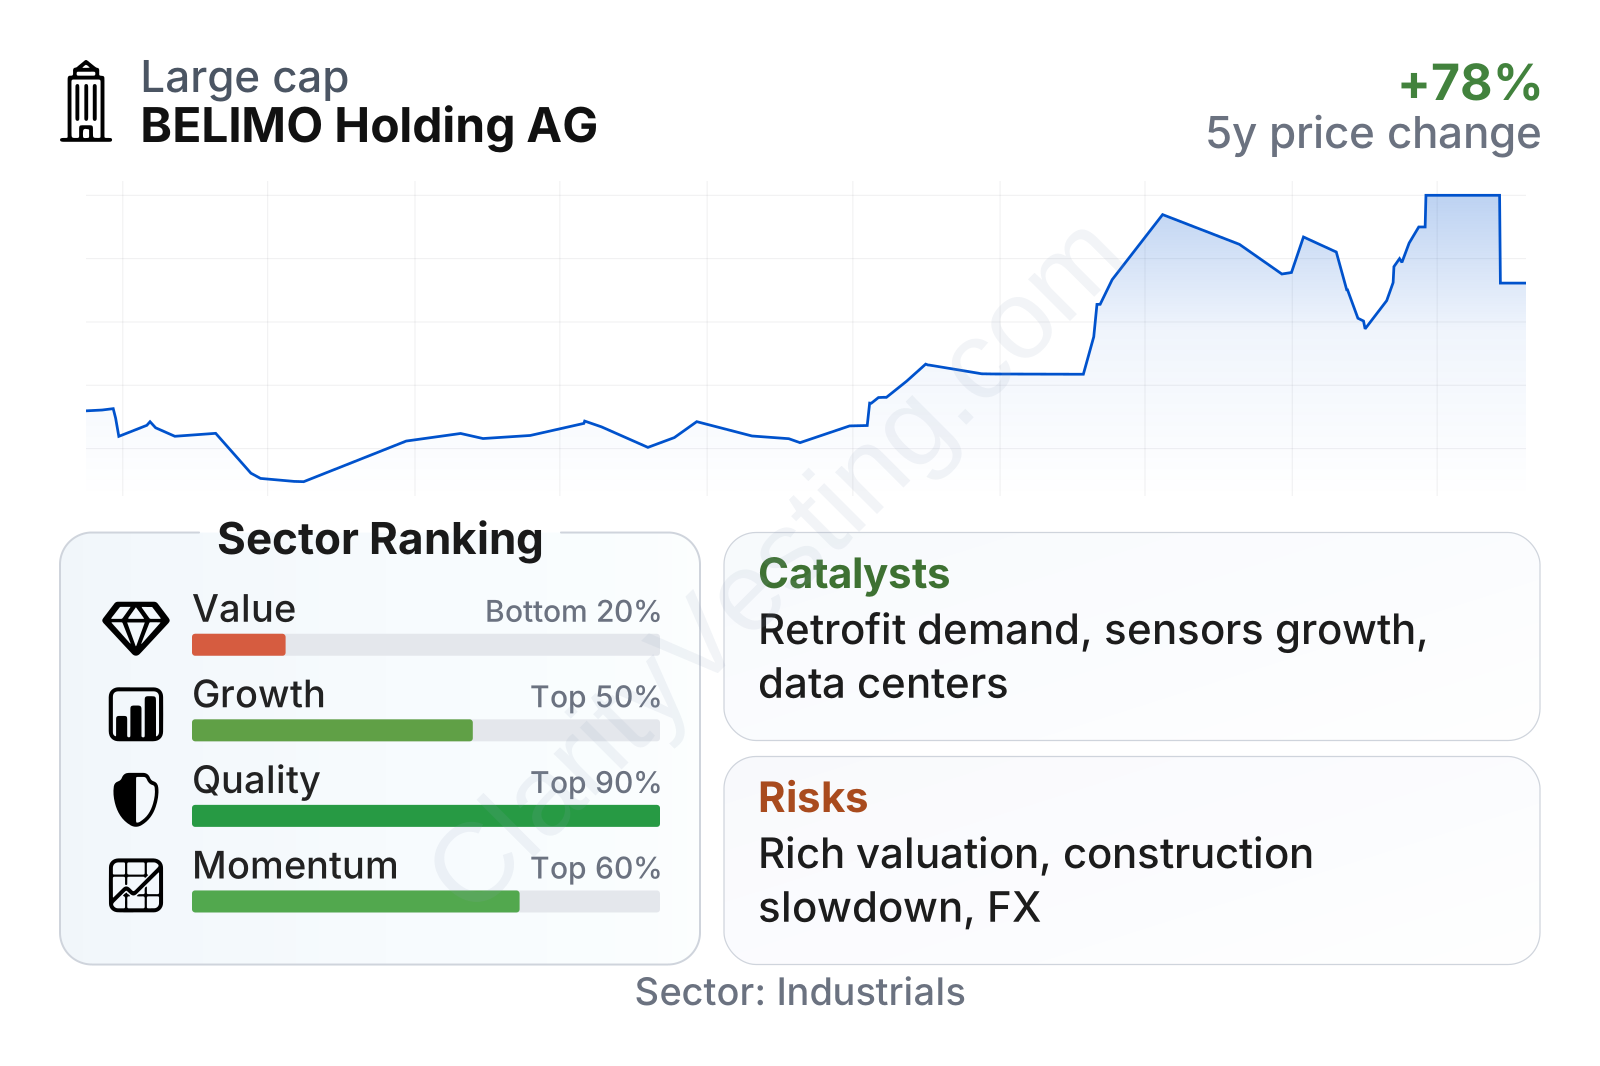
BELIMO’s overall profile is unusual in a good way on operating quality and balance sheet strength, but much less favorable on valuation. Profitability is far above the sector median, with operating margin around 21% and net margin around 17%, both well ahead of typical industrial peers. Returns on capital and assets are exceptionally high, and leverage is very low, with debt-to-equity near 21% and net debt close to negligible relative to earnings.
Growth is solid rather than explosive. Recent revenue growth has been above the sector median, and the five-year trend in revenue per share is also ahead of peers. Margin progression has improved over time as well. The weaker points are cash flow growth over the last five years and earnings-per-share trend in the supplied comparison set, which suggests that not every growth measure has moved smoothly.
Market behavior has been mixed. The stock has performed strongly over three years, but the shorter-term path has been more uneven. That combination often appears when a high-quality company goes through periods of valuation compression even while the underlying business remains healthy.
Growth
BELIMO operates in a part of the market that benefits from several durable trends. Buildings account for a large share of energy use, and tighter efficiency standards are pushing owners toward better control systems. At the same time, demand for healthier indoor environments has increased attention on ventilation performance, airflow control, and monitoring. These trends support the need for actuators, valves, sensors, and meters—the exact areas where BELIMO is concentrated.
The company’s strategy appears coherent for that environment. It is not trying to be everything in industrial automation; instead, it stays focused on HVAC field devices and related controls, where technical reliability, energy savings, and specification-driven sales can create sticky customer relationships. This kind of positioning can be attractive over the long run because building components often need to meet strict standards, and replacement decisions can favor proven suppliers.
One important catalyst is the retrofit cycle. Many existing commercial buildings need upgrades to reduce energy consumption or comply with modern efficiency rules. BELIMO does not rely only on new construction; modernization of installed systems can create recurring demand. Another catalyst is the rising content of sensors and monitoring hardware inside HVAC systems, which may gradually lift the value of each installation.
Recent company reporting also points to continued expansion in sensors and meters, a category tied more directly to smart-building and efficiency needs. If that mix keeps increasing, BELIMO could benefit from a business line that is strategically close to building automation trends and potentially supportive for margins.
A further opportunity comes from data center construction and other specialized buildings where climate control is critical. These projects require reliable airflow and thermal management, and BELIMO’s product portfolio is relevant to that demand. This does not make the company a pure data center play, but it adds another source of structural support beyond ordinary office or retail construction.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


