Stock Analysis · BioLife Solutions Inc (BLFS)
Overview
BioLife Solutions Inc. is a healthcare tools company focused on products and services that support the development, storage, transport, and manufacturing of advanced therapies. In simple terms, it helps cell and gene therapy companies keep sensitive biological materials viable from lab research through commercial production. Its offering spans biopreservation media, automated thawing and freezing equipment, cold-chain shipping solutions, and contract services tied to biologic material handling.
The business model is built around selling specialized consumables, equipment, and related services to biotechnology and biopharmaceutical customers. That creates exposure to a growing niche of medicine, but also ties results to customer funding cycles and therapy development timelines.
Based on recent annual reporting, revenue is mainly generated from the following sources:
- Cell Processing tools and consumables: approximately 45% to 55% of revenue. This includes biopreservation media and related products used to protect cells during freezing, storage, and handling.
- Cold-chain and storage services: approximately 25% to 35% of revenue. This includes evo shipping containers, cryogenic logistics support, and temperature-controlled transport solutions for biologic materials.
- Thawing, freezing, and automated handling equipment: approximately 15% to 25% of revenue. These products are used to prepare and process cell therapy materials with more consistency and lower contamination risk.
- Other service and product revenue: a small remaining portion, including support activities and adjacent processing solutions.
Over the last several years, the company has also been reshaping the mix of its portfolio, moving away from lower-quality or noncore revenue and placing more emphasis on therapy-enabling tools with recurring or repeat-use potential. That matters because consumables and embedded workflow products often produce steadier economics than one-time equipment sales.
The long-term operating picture shows a business that went through a difficult reset after a revenue peak in 2021, but has since rebuilt sales while improving gross profit. Operating losses narrowed materially from 2022 through 2025, suggesting cost controls and a cleaner revenue mix have helped, even if full operating profitability has not yet become consistent.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Healthcare | |
| Industry | Medical Instruments & Supplies | |
| Market Cap ⓘ | $1.89B | |
| Beta ⓘ | 1.82 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 39.00 | 24.79 |
| P/B Ratio ⓘ | 4.53 | 3.08 |
| FCF Yield ⓘ | -0.05% | 3.15% |
| Dividend Yield ⓘ | N/A | 1.94% |
| EBIT / EV ⓘ | 0.35% | 0.57% |
| PEG ⓘ | 65.38 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 21.50% | 7.45% |
| RPS Growth (5Y CAGR) ⓘ | -10.59% | 8.61% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -17.81% |
| BVPS Growth (5Y CAGR) ⓘ | -11.42% | 3.72% |
| Margin Growth (5Y Trend) ⓘ | N/A | -0.62% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 1.04% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 6.77% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 12.72% | 3.24% |
| ROA (Latest) ⓘ | 12.02% | 3.01% |
| ROIC (5Y Median) ⓘ | -1.90% | 4.60% |
| ROA (5Y Median) ⓘ | -4.97% | 1.89% |
| Net Debt / EBIT (Latest) ⓘ | -1.33 | 1.34 |
| Net Debt / EBIT (5Y Median) ⓘ | N/A | 1.84 |
| Net Debt / EBITDA (Latest) ⓘ | -0.86 | 1.00 |
| Net Debt / Assets ⓘ | -1.85% | 5.45% |
| EBITDA / Interest ⓘ | N/A | 9.64 |
| Operating Margin (Latest) ⓘ | 6.03% | 9.27% |
| Operating Margin (5Y Median) ⓘ | -14.00% | 7.38% |
| Debt to Equity (Latest) ⓘ | 3.75% | 28.58% |
| Profit Margin (Latest) ⓘ | 54.35% | 3.59% |
| Free Cash Flow (Latest) ⓘ | -$904.00K | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +185.16% | +42.80% |
| 12M Return (excl. last month) ⓘ | +33.22% | +18.50% |
| 6M Return ⓘ | +101.83% | +7.57% |
| Price vs. 200-Day MA ⓘ | +44.31% | +5.12% |
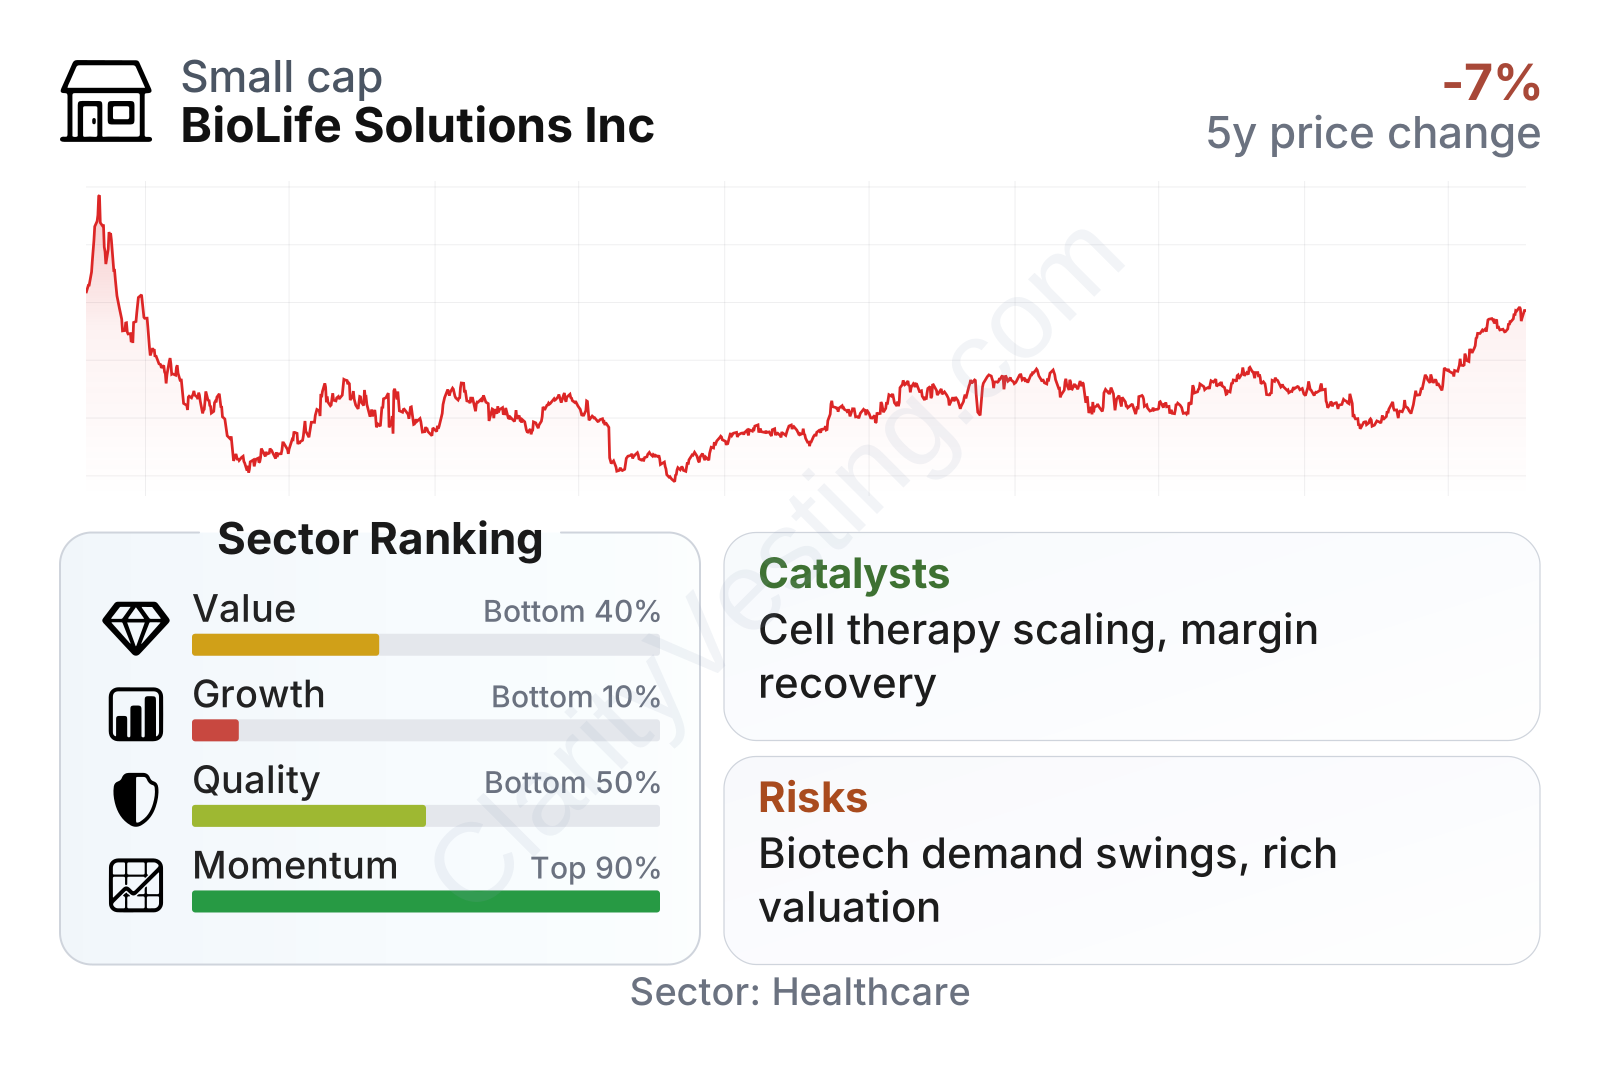
BioLife Solutions is a mid-cap healthcare tools company with a stock that has been much more volatile than the broader market, as shown by its high beta. The factor profile is mixed. Momentum is very strong, reflecting a sharp recovery in share performance over the last year and especially over the last six months. Quality is uneven: current returns on capital and assets are solid, and leverage is low, but longer-term profitability history remains weak. Growth looks weak on a five-year view because earlier declines still weigh on the record, even though recent year-over-year revenue growth has reaccelerated. Value metrics appear demanding relative to the sector, with a higher earnings multiple and price-to-book ratio, while free cash flow remains near break-even rather than comfortably positive.
Growth
BioLife Solutions operates in a part of healthcare that still has favorable structural drivers. Cell and gene therapy development, biologics manufacturing, and advanced cold-chain requirements all point to rising demand for specialized storage, processing, and transport solutions. These are not broad commodity markets: biological materials are fragile, process-sensitive, and expensive, so customers often prefer validated tools that fit regulatory and manufacturing workflows.
The company’s strategy broadly makes sense for that setting. It is trying to become a picks-and-shovels supplier to therapy developers rather than a drug developer itself. That approach can be attractive because success does not depend on a single therapy winning approval. Instead, the opportunity comes from serving many clinical programs and, ideally, staying embedded as those programs scale commercially.
Recent top-line trends are more encouraging than the longer-term averages suggest. Revenue growth has been volatile, including a deep contraction period, but the latest readings show a return to positive year-over-year expansion in the low-teens to low-twenties percentage range. That is clearly ahead of the sector median and supports the view that the business is in a recovery and rebuilding phase rather than a mature, low-growth phase.
Cash generation tells a more cautious version of the same story. Free cash flow improved dramatically from deeply negative levels and briefly turned positive, but the latest trailing figure slipped slightly below zero again. That does not invalidate the recovery, but it does show that growth has not yet translated into stable cash conversion. For a company serving fast-growing therapy markets, durable free cash flow is still an important milestone to watch.
A meaningful catalyst is the continued expansion of commercial manufacturing in cell and gene therapy. As programs move from research into later-stage trials and launch preparation, demand can increase not just for one product, but across preservation media, controlled-rate freezing, thawing, and shipping solutions. BioLife’s installed base and workflow position could allow one customer relationship to widen over time.
Another potential catalyst is portfolio simplification. In recent periods, management has emphasized sharper focus on core bioproduction tools and a more disciplined operating structure. If that leads to steadier margins and better cash flow, the market may continue to view the company less as a turnaround case and more as a specialized life-science tools platform.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


