Stock Analysis · Biohaven Ltd (BHVN)
Overview
Biohaven Ltd is a biotechnology company focused on developing medicines for neurological, neuropsychiatric, and rare disease conditions. Its research pipeline spans areas such as migraine, mood disorders, epilepsy-related conditions, and certain immunology and oncology targets, but the core investment question is still very simple: this is a company built around drug development rather than a mature, diversified pharmaceutical revenue base.
At this stage, Biohaven’s business model is driven much more by its drug pipeline, partnerships, and capital resources than by recurring product sales. That makes it different from large pharmaceutical companies that already generate broad commercial revenue. Biohaven’s long-term value depends on whether its clinical programs can advance successfully and eventually turn into approved products or licensing income.
Based on recent public filings, Biohaven currently has little to no recurring operating revenue. In practical terms, its revenue mix is heavily tilted away from commercial sales and toward nonrecurring or limited sources when available.
- Product revenue: approximately 0% recently. Biohaven is not currently operating as a scaled commercial drug seller.
- Collaboration, licensing, and other revenue: the company may record these items depending on partnership activity or accounting milestones, but recent annual revenue has been minimal to nonexistent.
- Financing-related resources: not revenue in an accounting sense, but still essential to the company’s operating model because research spending remains the main cash use.
The clearest operating pattern is that spending is concentrated in research and development. Over the last several years, R&D has represented the vast majority of operating expenses, which is typical for a clinical-stage biotech but also means Biohaven’s near-term economics are shaped by trial progress rather than sales execution.
The business picture is straightforward: little current revenue, heavy scientific investment, and a future that depends on pipeline conversion into approved medicines or commercially meaningful partnerships.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 03, 2026 | |
| Context | ||
| Sector | Healthcare | |
| Industry | Biotechnology | |
| Market Cap ⓘ | $1.98B | |
| Beta ⓘ | 3.17 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | N/A | 24.06 |
| P/B Ratio ⓘ | 161.95 | 3.08 |
| FCF Yield ⓘ | -25.79% | 3.07% |
| Dividend Yield ⓘ | N/A | 2.05% |
| EBIT / EV ⓘ | -27.97% | 0.63% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | N/A | 7.50% |
| RPS Growth (5Y CAGR) ⓘ | N/A | 8.70% |
| EPS Growth (5Y CAGR) ⓘ | -44.20% | -18.20% |
| BVPS Growth (5Y CAGR) ⓘ | -33.65% | 3.95% |
| Margin Growth (5Y Trend) ⓘ | N/A | -0.58% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 0.88% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 6.80% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | -154.16% | 3.29% |
| ROA (Latest) ⓘ | -150.50% | 3.02% |
| ROIC (5Y Median) ⓘ | -154.98% | 4.75% |
| ROA (5Y Median) ⓘ | -141.89% | 1.93% |
| Net Debt / EBIT (Latest) ⓘ | N/A | 1.33 |
| Net Debt / EBIT (5Y Median) ⓘ | N/A | 1.83 |
| Net Debt / EBITDA (Latest) ⓘ | N/A | 0.99 |
| Net Debt / Assets ⓘ | 15.91% | 5.33% |
| EBITDA / Interest ⓘ | N/A | 9.63 |
| Operating Margin (Latest) ⓘ | N/A | 9.25% |
| Operating Margin (5Y Median) ⓘ | N/A | 7.80% |
| Debt to Equity (Latest) ⓘ | 2430.33% | 28.99% |
| Profit Margin (Latest) ⓘ | N/A | 3.60% |
| Free Cash Flow (Latest) ⓘ | -$511.87M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | -45.41% | +37.48% |
| 12M Return (excl. last month) ⓘ | +2.27% | +20.85% |
| 6M Return ⓘ | +36.59% | +9.73% |
| Price vs. 200-Day MA ⓘ | +9.20% | +4.69% |
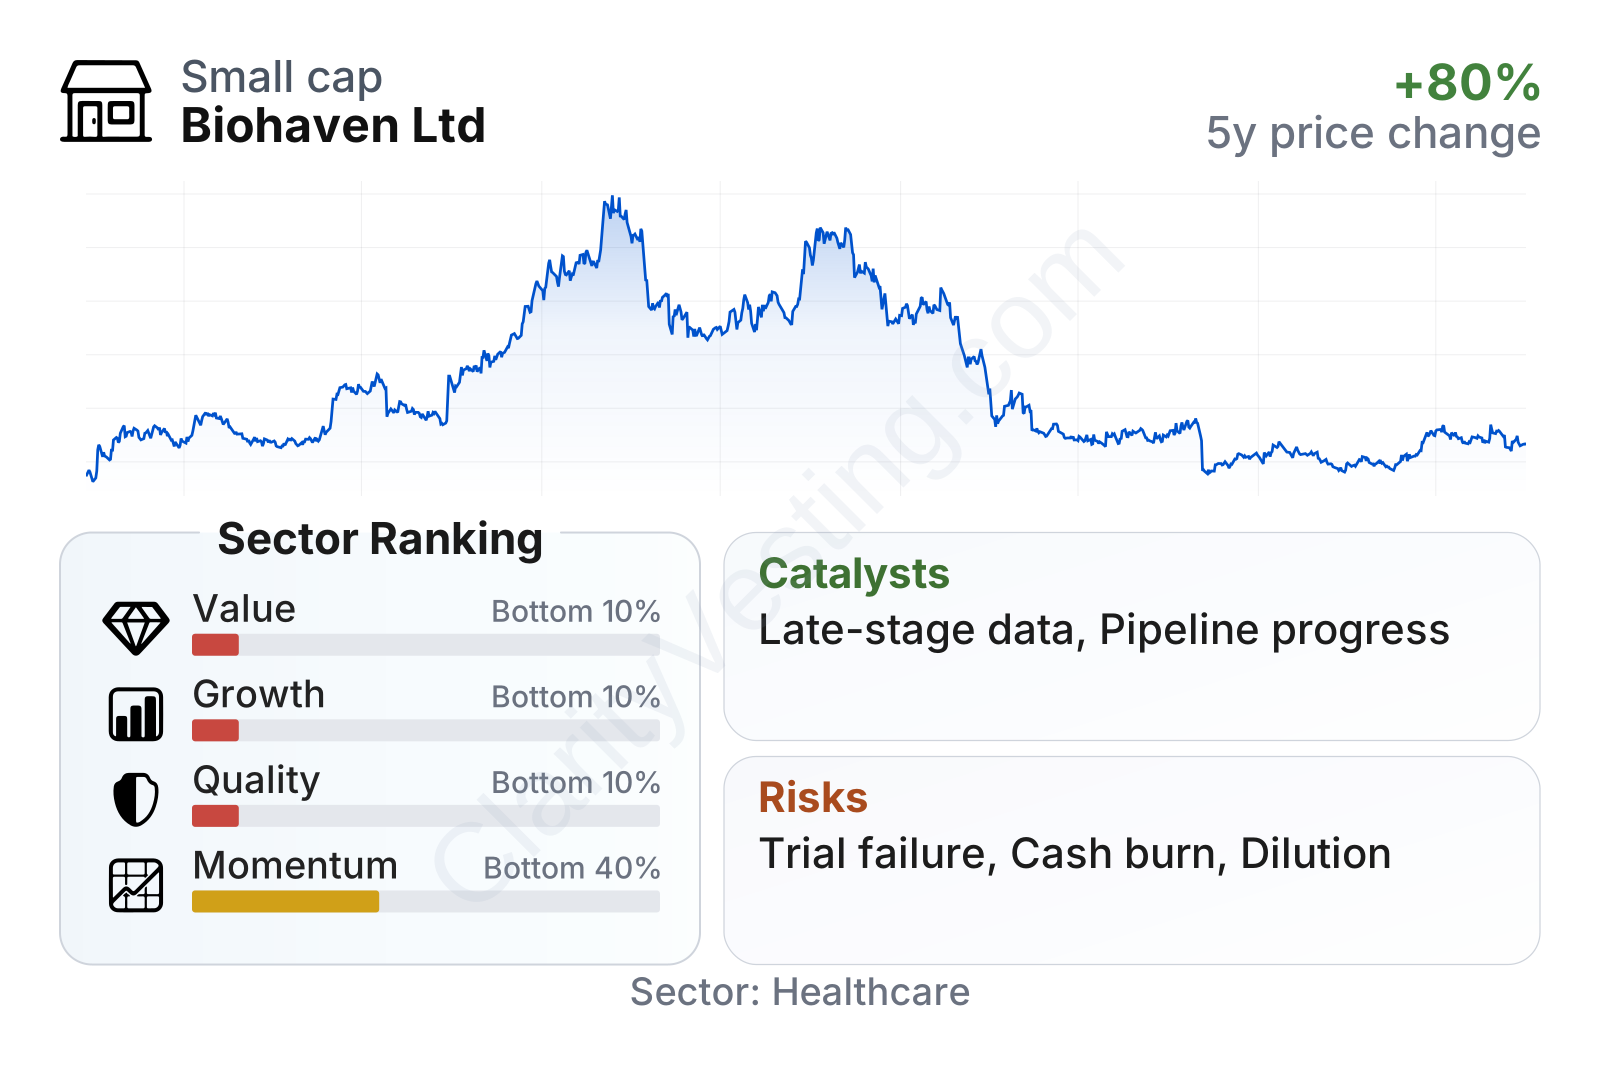
Biohaven is a small-cap biotechnology company with unusually high share-price volatility, reflected in a beta above 3. The stock has also been highly event-driven: it fell sharply over the longer three-year period, but the more recent six-month rebound shows how quickly sentiment can shift when investors focus on clinical milestones.
The metrics table points to a company that currently ranks poorly on value, quality, and growth versus much of the healthcare sector. That is not surprising for a development-stage biotech with limited revenue, negative free cash flow, and large ongoing losses. The most important takeaway is that conventional valuation tools such as earnings multiples are not very informative here; the market is mostly pricing Biohaven on future pipeline potential rather than current profitability.
Growth
Biohaven operates in one of the healthcare market’s most active long-term areas: innovative drug development for neurological and rare diseases. These are attractive markets because medical need is still substantial, successful drugs can command strong pricing, and breakthrough therapies can create meaningful commercial opportunities. In that sense, the sector backdrop is supportive for growth, even though it comes with high scientific risk.
Biohaven’s strategy also has a clear logic. Instead of relying on a single program, the company has assembled a broader pipeline across several therapeutic categories. For a long-term view, that matters because it reduces dependence on one binary outcome. At the same time, not all programs carry the same importance. The company’s future is still likely to be driven by a handful of lead assets, especially in neurology and related disorders, where proof of efficacy could materially change both partnership options and market expectations.
A key catalyst is clinical progress. For a company like Biohaven, positive trial readouts, regulatory updates, or partnership agreements can matter more than quarterly revenue. Any program that moves from mid-stage to late-stage development, or from late-stage data into a filing path, can significantly improve the company’s commercial outlook. Public company updates in 2026 have continued to emphasize pipeline advancement and portfolio prioritization, which keeps the focus on milestone-driven value creation rather than near-term sales.
Another reason Biohaven remains closely watched is the company’s history of creating value around neurology assets. That does not remove execution risk, but it does show management has experience developing programs in areas that larger drugmakers consider strategically important. If one or more lead candidates produce convincing results, Biohaven could benefit from the industry’s continuing appetite for external innovation.
The main financial constraint on growth is cash burn. Free cash flow remains deeply negative, although the recent trend appears somewhat less severe than the peak outflow seen previously. That suggests spending pressure is still high but no longer accelerating at the same pace. For a development-stage biotech, this means growth potential exists, but it must be balanced against how long the balance sheet can support multiple expensive clinical programs.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


