Stock Analysis · Brown-Forman Corporation (BF-A)
Overview
Brown-Forman is a global spirits company best known for Jack Daniel’s. It produces, markets, and sells premium alcoholic beverages, with a portfolio centered on American whiskey, tequila, ready-to-drink cocktails, and other premium spirits. The group operates in more than 170 countries through a mix of owned distribution, third-party distributors, and retail relationships. Its business model is relatively simple to understand: build brands with pricing power, support them with marketing and distribution, and convert a meaningful share of sales into cash.
The company’s revenue is concentrated in a handful of large brands and categories. Based on recent company disclosures, the main sources of revenue are approximately:
- Whiskey: about 70% to 75% of net sales. This is dominated by the Jack Daniel’s family of brands, which includes Tennessee Whiskey, Tennessee Honey, Tennessee Fire, Gentleman Jack, Single Barrel, and ready-to-drink extensions. It also includes Woodford Reserve, Old Forester, and other whiskey labels.
- Tequila: about 10% to 15% of net sales. This mainly comes from Herradura, el Jimador, and related agave-based spirits.
- Ready-to-drink cocktails and canned beverages: about 5% to 10%. This includes Jack Daniel’s & Coca-Cola RTD and other convenient premixed offerings.
- Vodka, gin, liqueurs, wine, and other products: about 5% to 10%. This includes brands such as Finlandia in periods before its divestiture impact fully cycles through comparisons, Gin Mare where relevant to partnerships/distribution, and smaller portfolio brands.
- Geographically, the United States remains the largest market, typically representing around 45% to 50% of sales, with the balance coming from developed international markets and emerging markets.
What stands out is not broad diversification across many equal-sized brands, but a strong concentration in premium spirits led by Jack Daniel’s. That concentration creates dependence on one franchise, but it also gives Brown-Forman one of the most recognizable names in global distilled spirits.
The economics remain attractive even after a softer period. Annual revenue has moved around the $3.9 billion to $4.2 billion range in recent years, and gross profit has stayed comfortably above $2.3 billion. However, the most recent year shows pressure: revenue edged lower and operating income fell more noticeably, partly because selling and administrative spending rose sharply while net income declined from prior peaks.
The business still converts a large share of sales into gross profit, which is typical of premium branded spirits. The recent weak point is further down the income statement: operating profit and net income have come off earlier highs, showing that brand strength has not fully offset slower demand and higher cost pressure.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Consumer Defensive | |
| Industry | Beverages - Wineries & Distilleries | |
| Market Cap ⓘ | $12.52B | |
| Beta ⓘ | 0.32 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 17.60 | 17.88 |
| P/B Ratio ⓘ | 3.22 | 1.29 |
| FCF Yield ⓘ | 7.39% | 12.39% |
| Dividend Yield ⓘ | 3.42% | 2.85% |
| EBIT / EV ⓘ | 6.97% | 6.43% |
| PEG ⓘ | 2.05 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | -1.40% | 4.10% |
| RPS Growth (5Y CAGR) ⓘ | 0.70% | 6.18% |
| EPS Growth (5Y CAGR) ⓘ | -35.94% | -13.59% |
| BVPS Growth (5Y CAGR) ⓘ | 10.89% | 3.20% |
| Margin Growth (5Y Trend) ⓘ | -2.18% | -0.15% |
| FCF Growth (5Y CAGR) ⓘ | 2.85% | 4.10% |
| DPS Growth (5Y CAGR) ⓘ | -14.71% | 6.79% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 12.07% | 12.34% |
| ROA (Latest) ⓘ | 8.99% | 6.30% |
| ROIC (5Y Median) ⓘ | 23.59% | 10.49% |
| ROA (5Y Median) ⓘ | 11.07% | 5.44% |
| Net Debt / EBIT (Latest) ⓘ | 2.15 | 1.96 |
| Net Debt / EBIT (5Y Median) ⓘ | 1.86 | 2.35 |
| Net Debt / EBITDA (Latest) ⓘ | 1.97 | 1.38 |
| Net Debt / Assets ⓘ | 27.35% | 21.51% |
| EBITDA / Interest ⓘ | 10.87 | 9.46 |
| Operating Margin (Latest) ⓘ | 25.39% | 8.87% |
| Operating Margin (5Y Median) ⓘ | 30.26% | 9.53% |
| Debt to Equity (Latest) ⓘ | 61.50% | 72.35% |
| Profit Margin (Latest) ⓘ | 18.42% | 5.40% |
| Free Cash Flow (Latest) ⓘ | $925.00M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | -44.81% | +20.92% |
| 12M Return (excl. last month) ⓘ | -1.45% | +2.13% |
| 6M Return ⓘ | -4.49% | +1.26% |
| Price vs. 200-Day MA ⓘ | +3.09% | +1.39% |
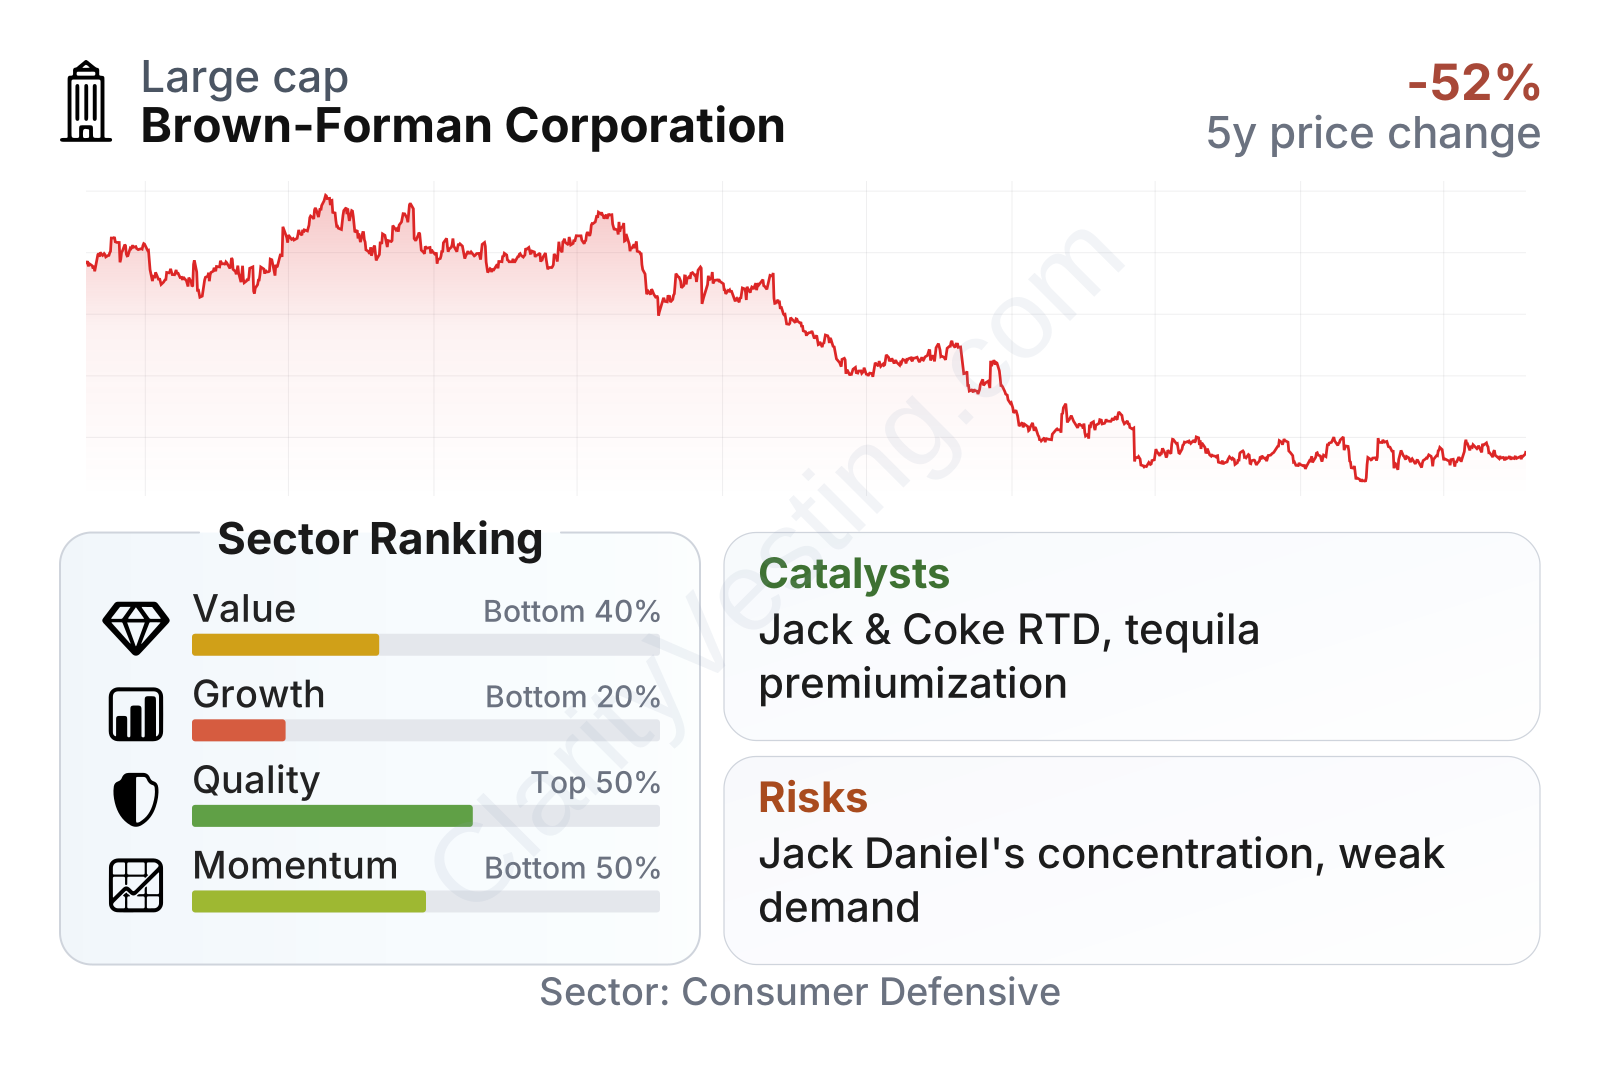
Brown-Forman is a large established consumer company with unusually low share-price volatility for a stock, reflected in a beta near 0.33. On quality, it still ranks relatively well: returns on assets and invested capital remain above many sector peers, and profit margins are much stronger than the industry median. The weak area is growth. Revenue growth has recently been slightly negative, five-year sales growth per share has been modest, and earnings growth over that span has been poor. Valuation looks more mixed than expensive at first glance: the earnings multiple is around the sector median, but the price-to-book ratio remains clearly richer than peers, suggesting the market still assigns value to the brand portfolio and consistency.
Growth
Brown-Forman operates in a sector that has favorable long-term characteristics, but not a straight-line growth profile. Global spirits benefit from premiumization, international expansion, and brand loyalty. Consumers often trade up within spirits over time, and well-known labels can retain pricing power for many years. That said, the industry is currently moving through a slower phase, with some markets showing weaker demand, distributor inventory adjustments, and more cautious consumer spending.
The company’s strategy remains logical for long-term expansion. Management continues to emphasize premium and super-premium products, international distribution, innovation in flavor extensions and ready-to-drink formats, and selective brand building rather than large-scale acquisitions. That approach fits Brown-Forman’s strengths. Jack Daniel’s still has room to expand internationally, tequila remains an attractive category, and ready-to-drink products give the company access to a faster-moving segment that can bring in younger and convenience-oriented consumers.
Recent growth has been inconsistent. After a strong post-pandemic rebound, year-over-year revenue growth turned negative through much of 2024 and 2025, then briefly improved before slipping slightly negative again. This pattern suggests the company is not in structural decline, but it is clearly in a slower operating period than the market had once expected.
Cash generation has improved from the lows seen after 2022. Free cash flow recovered from under $400 million at its weakest point to roughly $700 million to $900 million more recently. That matters because spirits companies need ongoing brand investment, barrel aging inventory, and distribution support, yet Brown-Forman still produces substantial cash even during a weaker sales environment.
A meaningful recent catalyst is the continued development of the Jack Daniel’s and Coca-Cola ready-to-drink partnership, which gives the company access to a globally recognized combination in a category that is growing faster than traditional spirits in many markets. Another catalyst is the ongoing premiumization of American whiskey and tequila internationally. Brown-Forman has also continued adjusting its portfolio and distribution setup in ways meant to sharpen execution rather than simply chase volume.
There is opportunity if volumes stabilize and premium brands regain momentum, because the company already has the distribution footprint and brand recognition to translate even moderate demand improvement into better profit performance. The issue is not whether Brown-Forman has expansion avenues; it is whether those avenues can outweigh near-term softness quickly enough to restore stronger earnings growth.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


