Stock Analysis · Beta Technologies Inc (BETA)
Overview
Beta Technologies Inc is an aerospace company focused on electric aviation. Its main products and services center on electric aircraft, charging infrastructure, and related technology designed to support lower-emission flight operations. The company is part of the broader aerospace and defense industry, but its positioning is closer to the emerging market for electric and advanced air mobility than to traditional aircraft manufacturing.
At this stage, Beta Technologies appears to be in a commercialization phase rather than a mature operating phase. Revenue is still relatively small compared with its cost base, which is common for an aircraft developer building products, certification capabilities, manufacturing capacity, and infrastructure at the same time.
The company’s revenue mix is not disclosed in enough detail to build a precise percentage split from public filings alone. Based on company disclosures, revenue is mainly tied to early aircraft- and aviation-related commercial activities, with additional contributions from technology and infrastructure work connected to its electric aviation platform.
- Aircraft and aviation platform activities: likely the largest source, including early deliveries, customer programs, and work tied to electric aircraft deployment.
- Charging and infrastructure-related activities: equipment, network deployment, and supporting services for electric aviation operations.
- Other development and partnership revenue: work associated with testing, support, and strategic programs, where recognized under accounting rules.
What stands out most is not the current revenue size, but the business model the company is trying to establish: a combined aircraft-and-infrastructure ecosystem. If that model gains traction, Beta would not depend only on aircraft sales, which are often cyclical and lumpy, but could also benefit from recurring activity around charging, support, and network usage.
Financially, the path is still very early. Revenue improved meaningfully in 2025, while research and development spending and total operating expenses remained far above sales. That indicates the company is still investing heavily ahead of broader market adoption.
The financial flow highlights a familiar profile for an early-stage aerospace company: modest revenue, very large research and development spending, and heavy operating losses. One encouraging sign is that gross profit turned positive in 2025 after being negative in 2024, suggesting the commercial base is beginning to improve even though the scale remains far too small to absorb fixed costs.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Industrials | |
| Industry | Aerospace & Defense | |
| Market Cap ⓘ | $4.25B | |
| Beta ⓘ | N/A | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | N/A | 22.29 |
| P/B Ratio ⓘ | 2.69 | 1.98 |
| FCF Yield ⓘ | -9.93% | 6.26% |
| Dividend Yield ⓘ | N/A | 1.92% |
| EBIT / EV ⓘ | -19.36% | 4.83% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 145.70% | 9.30% |
| RPS Growth (5Y CAGR) ⓘ | 50.44% | 7.76% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -13.17% |
| BVPS Growth (5Y CAGR) ⓘ | 114.48% | 6.13% |
| Margin Growth (5Y Trend) ⓘ | N/A | 0.74% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 10.79% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 9.41% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | -62.03% | 10.75% |
| ROA (Latest) ⓘ | -57.16% | 5.41% |
| ROIC (5Y Median) ⓘ | N/A | 9.37% |
| ROA (5Y Median) ⓘ | N/A | 4.95% |
| Net Debt / EBIT (Latest) ⓘ | N/A | 2.04 |
| Net Debt / EBIT (5Y Median) ⓘ | N/A | 2.27 |
| Net Debt / EBITDA (Latest) ⓘ | N/A | 1.39 |
| Net Debt / Assets ⓘ | -65.83% | 19.27% |
| EBITDA / Interest ⓘ | N/A | 9.58 |
| Operating Margin (Latest) ⓘ | -1909.18% | 10.49% |
| Operating Margin (5Y Median) ⓘ | -1747.31% | 10.30% |
| Debt to Equity (Latest) ⓘ | 12.80% | 64.82% |
| Profit Margin (Latest) ⓘ | N/A | 6.67% |
| Free Cash Flow (Latest) ⓘ | -$421.53M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | N/A | +67.77% |
| 12M Return (excl. last month) ⓘ | N/A | +12.05% |
| 6M Return ⓘ | +12.83% | 0.00% |
| Price vs. 200-Day MA ⓘ | -3.05% | +0.67% |
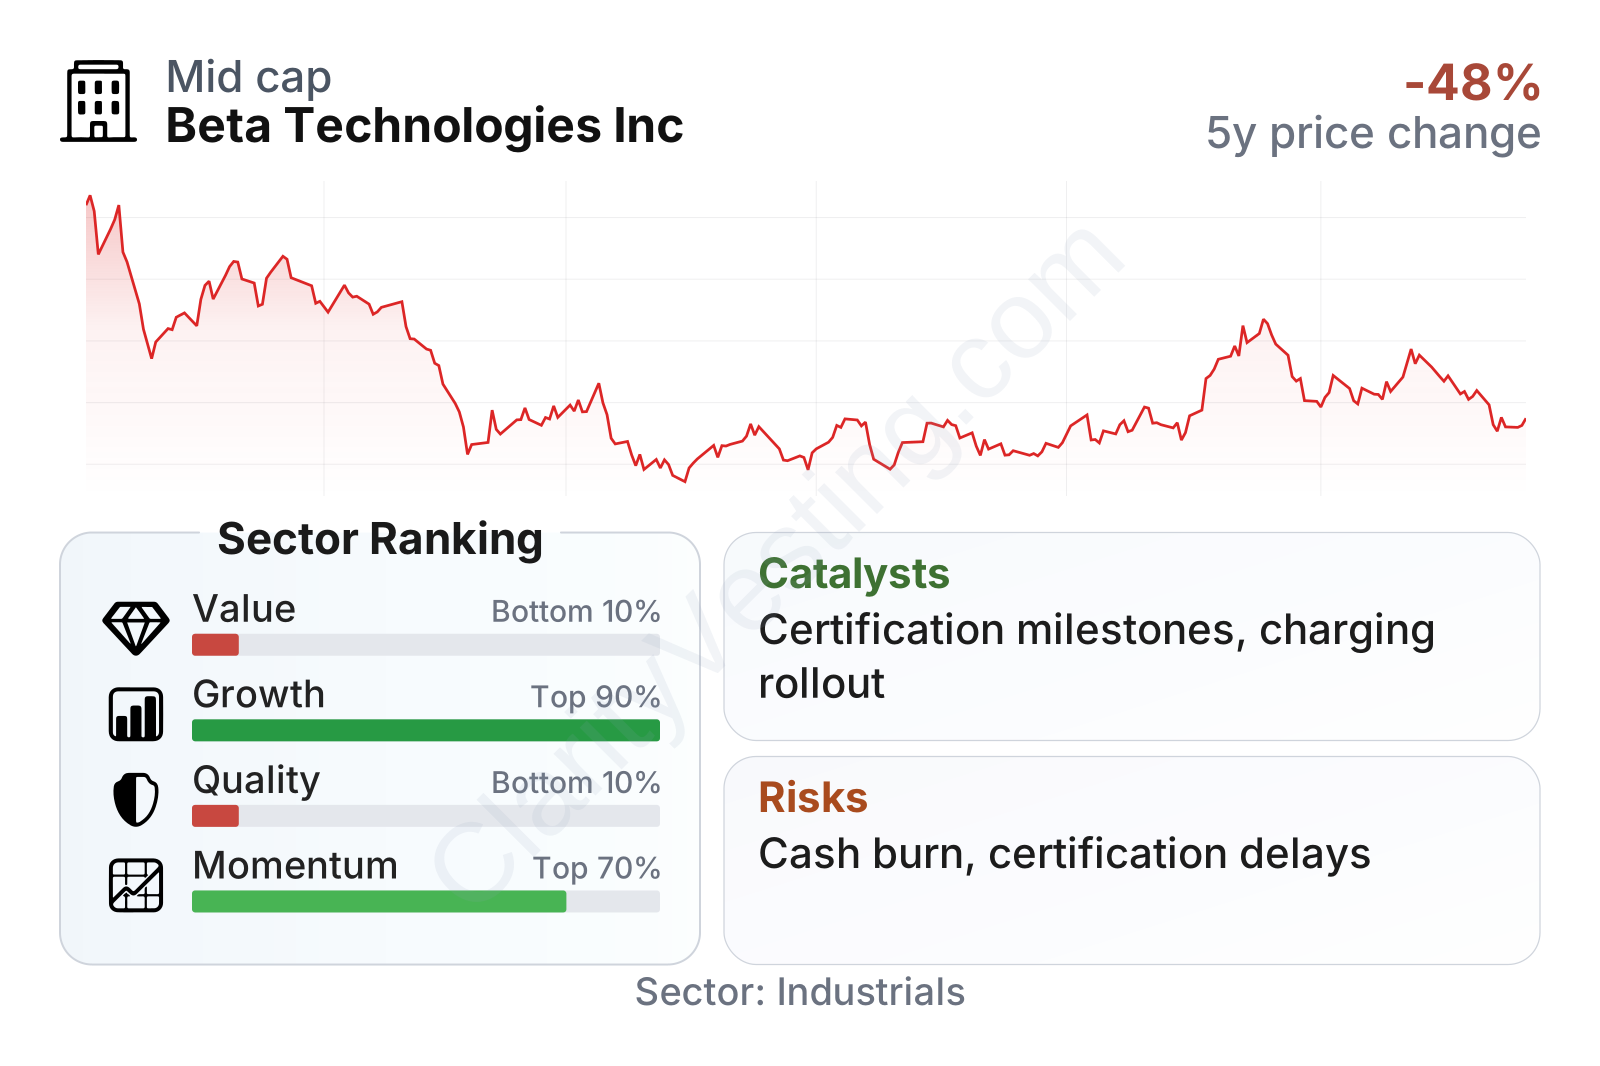
Beta Technologies combines very strong growth signals with very weak current profitability. Relative to the broader aerospace and defense group, the company ranks near the top on growth and share-price momentum, but near the bottom on value and quality metrics. That is consistent with a business that is scaling quickly from a low base while still generating large losses and negative free cash flow.
The company is mid-sized by market value, but its operating profile still looks venture-like. Revenue growth is far above the sector median, and book value growth has also been unusually strong, showing how quickly the balance sheet and operating footprint have expanded. At the same time, returns on capital and assets are deeply negative, and cash consumption remains heavy. The stock’s trading pattern also shows elevated volatility, with a sharp drop followed by a strong recovery over recent months.
Growth
Beta Technologies operates in a sector with credible long-term growth potential. Electric aviation remains early, but interest has been rising around lower-emission aircraft, regional logistics, military and government applications, and airport electrification. If battery performance, certification progress, and infrastructure rollout continue to improve, the addressable market could expand well beyond niche pilot programs.
The company’s strategy is logical for that environment. Rather than building only an aircraft, Beta is developing a broader operating system around electric flight. That matters because adoption in aviation depends on more than the vehicle itself. Customers also need charging access, operational support, maintenance readiness, and regulatory confidence. By building both aircraft and charging solutions, Beta is trying to reduce one of the biggest barriers to market adoption.
Another positive point is the speed of top-line expansion. Revenue growth well above 100% year over year suggests commercial activity is moving forward, even if from a very small base. Over a multi-year period, revenue per share growth has also been far stronger than the sector median. These are important early signals that the company is not purely in a research phase anymore.
A major catalyst is certification and deployment. In electric aviation, technical progress matters, but regulatory approval matters even more. Any milestone involving aircraft certification, customer deliveries, expanded defense or logistics use cases, or new charging network partnerships could materially improve the company’s commercial position. For Beta, proof that operators can use its aircraft and infrastructure together in real-world settings would likely be more important than short-term accounting profit.
Recent company communications have also emphasized continued platform development, operational testing, and the buildout of supporting infrastructure. Those steps do not eliminate execution risk, but they do suggest management is pursuing a practical route to adoption rather than relying on a single product launch.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


