Stock Analysis · AZZ Incorporated (AZZ)
Overview
AZZ Incorporated is an industrial company focused on two main activities: coating metal products to protect them from corrosion, and manufacturing metal coil coatings used on building products and other industrial applications. In simple terms, the company helps steel and other metals last longer, look better, and perform reliably in demanding environments.
Its business is organized into two segments, with revenue now heavily weighted toward coatings. Based on the latest annual results for the fiscal year ended February 28, 2026, the mix is approximately:
- Metal Coatings: about 63% of revenue. This includes hot-dip galvanizing, spin casting, powder coating, anodizing, plating, and other metal finishing services used in construction, utilities, transportation, and general industrial markets.
- Precoat Metals: about 37% of revenue. This segment applies protective and decorative coatings to steel and aluminum coils that are later used in products such as building panels, ducts, garage doors, appliances, and other fabricated metal goods.
Over the last several years, AZZ has become a more focused coatings company after reshaping its portfolio. That matters because coatings tends to be a steadier, more specialized activity than many capital goods businesses. The profit flow also improved meaningfully in the latest fiscal year, with stronger operating income, lower interest expense, and a much higher bottom line than in prior years. Selling and administrative costs have stayed relatively controlled as revenue expanded, which suggests operating leverage is improving.
The revenue and profit profile shows a business that has scaled up significantly since 2022 while becoming more efficient. One notable improvement is the drop in interest expense from earlier post-acquisition levels, which has helped more of the operating profit reach net income.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 19, 2026 | |
| Context | ||
| Sector | Industrials | |
| Industry | Specialty Business Services | |
| Market Cap ⓘ | $3.89B | |
| Beta ⓘ | 1.13 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 23.34 | 22.10 |
| P/B Ratio ⓘ | 2.75 | 1.97 |
| FCF Yield ⓘ | 5.51% | 6.42% |
| Dividend Yield ⓘ | 0.64% | 1.94% |
| EBIT / EV ⓘ | 5.80% | 4.79% |
| PEG ⓘ | 1.24 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 16.70% | 9.30% |
| RPS Growth (5Y CAGR) ⓘ | 27.05% | 7.81% |
| EPS Growth (5Y CAGR) ⓘ | 3.79% | -13.06% |
| BVPS Growth (5Y CAGR) ⓘ | 13.56% | 6.14% |
| Margin Growth (5Y Trend) ⓘ | 13.74% | 0.88% |
| FCF Growth (5Y CAGR) ⓘ | 66.68% | 11.01% |
| DPS Growth (5Y CAGR) ⓘ | 3.22% | 9.41% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 12.67% | 10.84% |
| ROA (Latest) ⓘ | 7.33% | 5.41% |
| ROIC (5Y Median) ⓘ | 13.66% | 9.38% |
| ROA (5Y Median) ⓘ | 5.83% | 4.95% |
| Net Debt / EBIT (Latest) ⓘ | 2.06 | 2.08 |
| Net Debt / EBIT (5Y Median) ⓘ | 3.48 | 2.27 |
| Net Debt / EBITDA (Latest) ⓘ | 1.53 | 1.40 |
| Net Debt / Assets ⓘ | 23.89% | 19.29% |
| EBITDA / Interest ⓘ | 8.02 | 9.56 |
| Operating Margin (Latest) ⓘ | 15.55% | 10.50% |
| Operating Margin (5Y Median) ⓘ | 15.42% | 10.29% |
| Debt to Equity (Latest) ⓘ | 39.60% | 65.48% |
| Profit Margin (Latest) ⓘ | 9.59% | 6.67% |
| Free Cash Flow (Latest) ⓘ | $214.45M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +180.34% | +61.68% |
| 12M Return (excl. last month) ⓘ | +16.70% | +12.58% |
| 6M Return ⓘ | -2.83% | 0.00% |
| Price vs. 200-Day MA ⓘ | -5.40% | 0.00% |
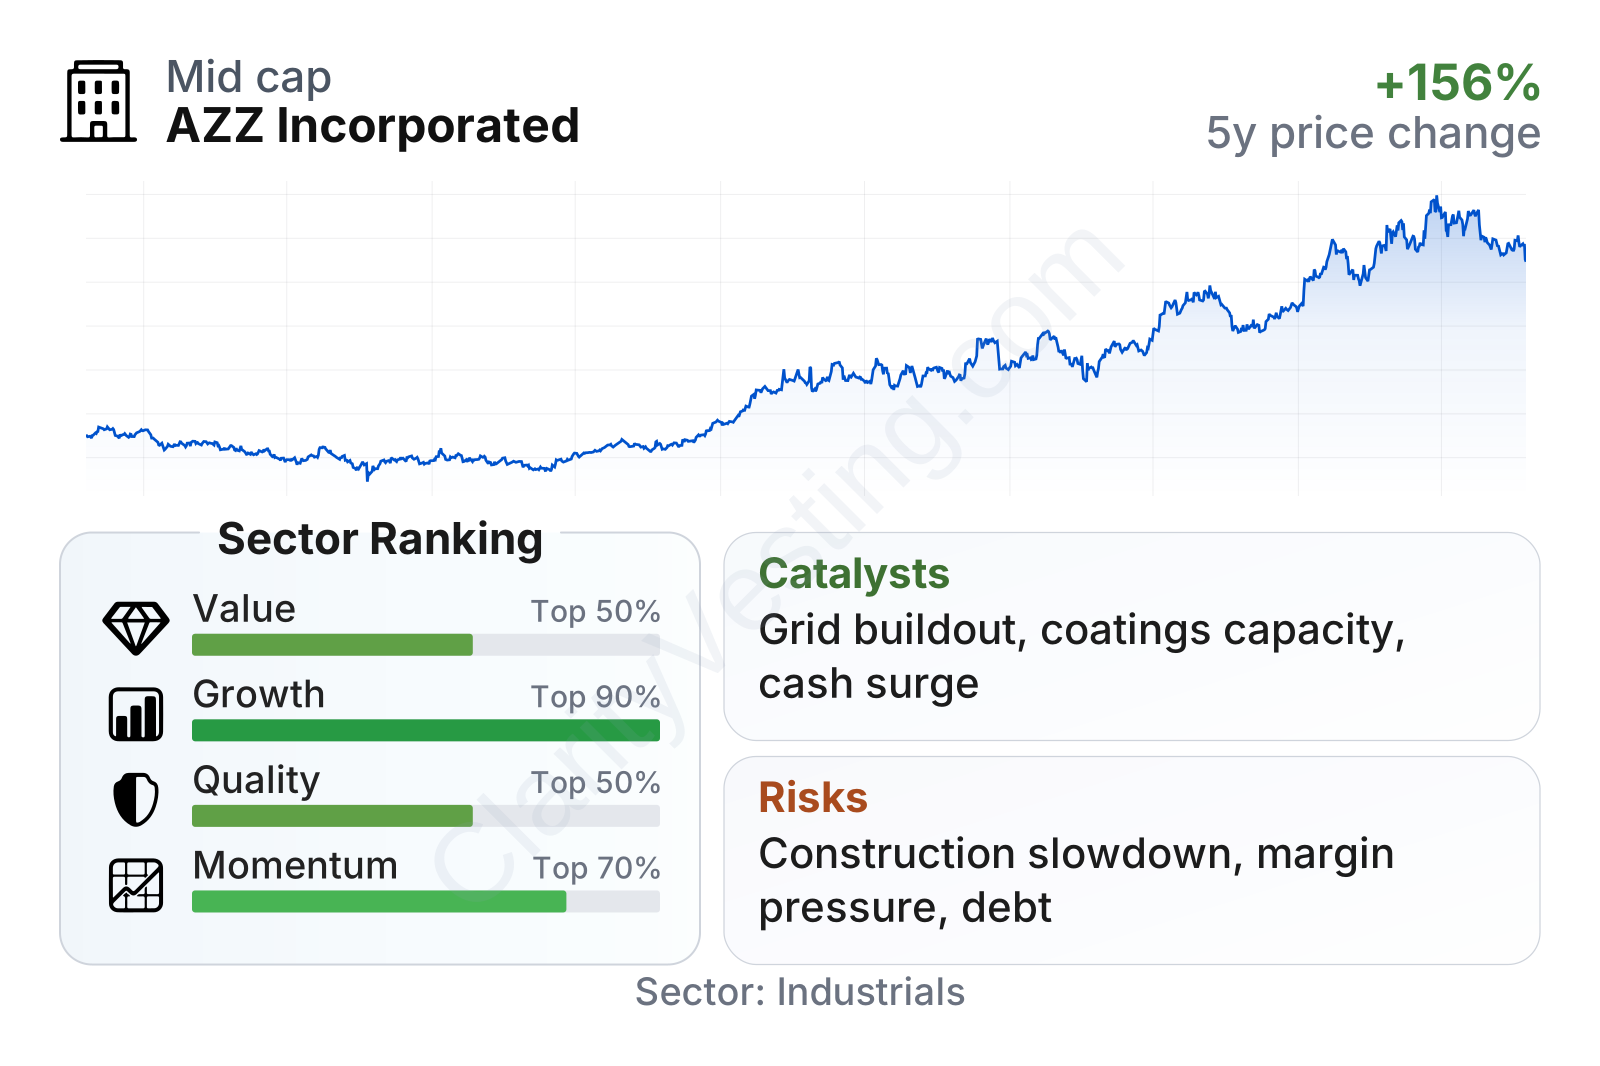
AZZ screens as a mid-sized industrial company with balanced overall fundamentals. Growth stands out the most, ranking near the top of its sector, while profitability and returns on capital are also above typical sector levels. Value metrics look close to the sector average on earnings, but not notably cheap on book value or cash flow yield. Momentum remains positive over longer periods, even though the shares have cooled somewhat in the most recent months after a strong multi-year rise.
Growth
AZZ operates in parts of the industrial economy that benefit from long-duration demand rather than short-lived trends. Corrosion protection and coated metal products are tied to infrastructure, electric utility networks, non-residential construction, manufacturing, and maintenance spending. These are not flashy markets, but they are important and recurring because metal assets need protection throughout their useful lives.
The company’s strategy appears coherent for long-term expansion. Metal Coatings is service-based, local, and hard to replace once customers are integrated into regional networks. Precoat Metals adds another way to serve construction and industrial customers with specialized coated products. This combination gives AZZ exposure to both service revenue and manufactured product revenue, while keeping a clear focus on coatings-related activities.
Recent growth has been solid rather than purely acquisition-driven. After unusually volatile comparisons in earlier periods, revenue growth settled into a more normal positive range and accelerated again in the latest readings, with year-over-year growth around the mid-to-high single digits and then rising into the mid-teens. That compares favorably with the broader sector and supports the view that demand has remained healthy.
Cash generation is another encouraging point. Free cash flow was modest after the company’s large portfolio changes, but it recovered strongly and recently moved to a much higher level. A step-up of that size can support debt reduction, plant upgrades, selective acquisitions, and shareholder returns without requiring the company to stretch its balance sheet.
A visible catalyst is the continued buildout and maintenance of electrical transmission, renewable-related infrastructure, and U.S. industrial facilities. Galvanizing and metal protection are essential in those applications because replacing corroded structures is costly. Another positive factor is AZZ’s network footprint in North America, which can make it easier to capture work close to customer sites and benefit from local scale.
Recent company updates also point to ongoing investments in capacity and operational efficiency. For a coatings business, incremental capacity in the right geography can matter because transportation costs and turnaround time are important for customers. If end-market demand remains stable, those investments can support both revenue growth and margins.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


