Stock Analysis · Acuity Brands Inc (AYI)
Overview
Acuity Brands is a U.S.-based industrial technology company best known for lighting products used in commercial, institutional, industrial, and infrastructure settings. Over time, it has expanded from traditional lighting fixtures into LED systems, lighting controls, building management software, and other technology-enabled products designed to improve energy efficiency, automation, and building performance.
The company reports its business in two main segments. The larger operation is focused on lighting and lighting controls sold under a portfolio of established brands. The smaller segment is centered on intelligent building technologies, including products and software used for building management, audio-visual control, and related automation applications.
Based on recent company reporting, revenue is mainly split as follows:
- Acuity Brands Lighting and Lighting Controls (ABL): approximately 89% to 91% of revenue. This includes indoor and outdoor luminaires, LED fixtures, retrofit solutions, emergency lighting, controls, and components used across offices, schools, warehouses, retail sites, roads, and other facilities.
- Intelligent Spaces Group (ISG): approximately 9% to 11% of revenue. This includes building management platforms, software, audio-visual and control technologies, and sensors that help customers operate buildings more efficiently.
The business mix also shows why Acuity Brands is often viewed as more than a pure lighting manufacturer. The lighting operation still drives most sales, but the company is gradually adding more software, controls, and electronics content, which can support better margins and make the offering harder to commoditize.
Over the last several years, the income profile has improved meaningfully. Revenue has risen, but the more notable trend is that gross profit has expanded faster than cost of revenue, suggesting a richer product mix and better pricing discipline. Net income has also moved up strongly by the latest period, even as operating expenses increased with investment in technology and commercial capabilities.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Industrials | |
| Industry | Electrical Equipment & Parts | |
| Market Cap ⓘ | $9.01B | |
| Beta ⓘ | 1.30 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 17.66 | 22.10 |
| P/B Ratio ⓘ | 3.07 | 1.97 |
| FCF Yield ⓘ | 8.30% | 6.38% |
| Dividend Yield ⓘ | 0.26% | 1.94% |
| EBIT / EV ⓘ | 7.72% | 4.79% |
| PEG ⓘ | 1.21 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 2.90% | 9.30% |
| RPS Growth (5Y CAGR) ⓘ | 6.55% | 7.81% |
| EPS Growth (5Y CAGR) ⓘ | 10.63% | -13.06% |
| BVPS Growth (5Y CAGR) ⓘ | 14.69% | 6.14% |
| Margin Growth (5Y Trend) ⓘ | 3.20% | 0.88% |
| FCF Growth (5Y CAGR) ⓘ | 30.26% | 11.01% |
| DPS Growth (5Y CAGR) ⓘ | 9.97% | 9.48% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 13.93% | 10.84% |
| ROA (Latest) ⓘ | 11.16% | 5.41% |
| ROIC (5Y Median) ⓘ | 26.23% | 9.38% |
| ROA (5Y Median) ⓘ | 10.89% | 4.95% |
| Net Debt / EBIT (Latest) ⓘ | 0.08 | 2.08 |
| Net Debt / EBIT (5Y Median) ⓘ | 0.20 | 2.27 |
| Net Debt / EBITDA (Latest) ⓘ | 0.07 | 1.39 |
| Net Debt / Assets ⓘ | 1.25% | 19.28% |
| EBITDA / Interest ⓘ | 30.40 | 9.58 |
| Operating Margin (Latest) ⓘ | 15.89% | 10.50% |
| Operating Margin (5Y Median) ⓘ | 12.69% | 10.29% |
| Debt to Equity (Latest) ⓘ | 23.45% | 65.48% |
| Profit Margin (Latest) ⓘ | 11.45% | 6.67% |
| Free Cash Flow (Latest) ⓘ | $747.90M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +67.45% | +61.68% |
| 12M Return (excl. last month) ⓘ | -7.82% | +12.58% |
| 6M Return ⓘ | +4.35% | 0.00% |
| Price vs. 200-Day MA ⓘ | -4.65% | +0.02% |
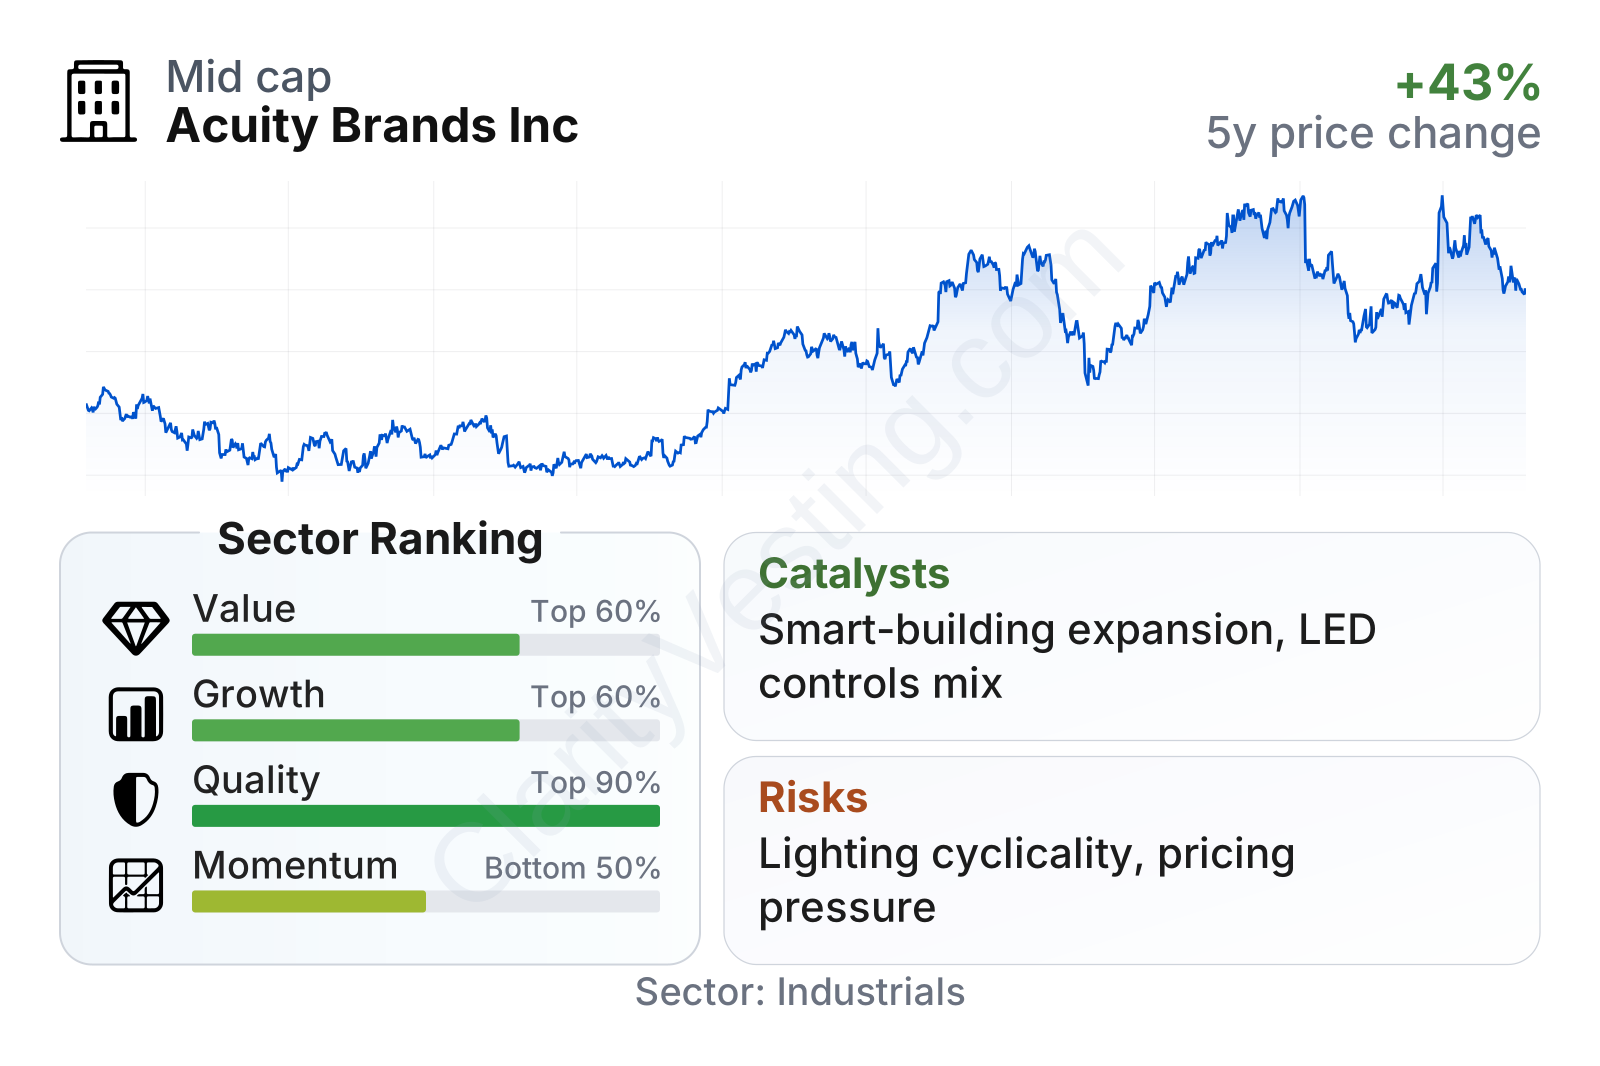
Acuity Brands is a large industrial company, but not a mega-cap name, which can make its share price somewhat more sensitive to swings in business sentiment. The stock has been volatile over the last few years, yet the longer-term trend remains clearly positive. In the latest factor snapshot, valuation looks broadly moderate versus the sector, growth is decent rather than exceptional, quality stands out strongly, and momentum has been mixed in the shorter term after a strong multi-year run.
Growth
Acuity Brands operates in parts of the market that benefit from durable structural demand. Buildings continue shifting toward LED upgrades, connected controls, and smarter energy management. Those themes are supported by energy savings requirements, sustainability targets, and the need to modernize aging commercial and institutional buildings. This is not a hyper-growth industry, but it is one with recurring retrofit opportunities and a gradual move toward higher-value systems.
The company’s strategy appears coherent for this environment. In lighting, it continues to push value-added products rather than compete only on basic fixtures. In intelligent spaces, it is trying to build a larger presence in software and automation, where customer relationships can become deeper and pricing can be more resilient. That matters because standard lighting hardware can face heavier price pressure, while controls and building intelligence can create more differentiation.
Revenue growth has not been smooth. The company moved from strong post-pandemic expansion to a softer period with some year-over-year declines, then returned to growth. Most recently, the pace has been positive but modest, around the low-single-digit range, which is below the sector median. That suggests Acuity Brands is not currently in a rapid expansion phase, but it has shown an ability to recover and grow again after cyclical slowdowns.
Cash generation is one of the more encouraging parts of the picture. Free cash flow has trended higher over the last several years, despite some interim fluctuations, and the latest trailing figure is substantial for the company’s size. Over five years, free cash flow growth has been far stronger than the sector median. This gives management flexibility for acquisitions, product investment, debt reduction, and shareholder returns without stretching the balance sheet.
A notable catalyst for future growth is the continued shift toward intelligent building solutions. Acuity Brands has used acquisitions to strengthen this area, and if software, controls, and automation continue gaining share within the mix, the company could improve both revenue quality and profitability. Another potential tailwind is non-residential construction and renovation activity, especially in segments where energy efficiency upgrades remain a priority.
Recent company updates have also pointed to ongoing product innovation and efforts to expand the addressable market beyond core lighting. That is important because the strongest long-term opportunity likely comes less from simply selling more fixtures and more from embedding the company’s technology deeper into how buildings are managed and operated.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


