Stock Analysis · Axalta Coating Systems Ltd (AXTA)
Overview
Axalta Coating Systems Ltd is a global coatings company that makes products used to protect and improve the appearance of surfaces. In simple terms, it sells paints and coatings for vehicles, industrial equipment, buildings, and other manufactured products. Its business is less about consumer wall paint and more about specialized coatings that need to meet performance standards such as durability, corrosion resistance, color matching, and productivity in manufacturing or repair shops.
The company operates through two main segments: Performance Coatings and Mobility Coatings. Based on recent annual reporting, revenue is weighted slightly toward Performance Coatings, with Mobility Coatings also representing a very large share of the business.
- Performance Coatings: about 55% of revenue — This segment includes refinish coatings used in vehicle repair shops after collisions or wear, as well as industrial coatings used on construction equipment, architectural components, and other manufactured goods. Refinish is particularly important because demand is tied more to the installed base of cars on the road than to new vehicle production.
- Mobility Coatings: about 45% of revenue — This segment mainly serves light vehicle and commercial vehicle manufacturers. It includes coatings applied during original vehicle production and products designed to meet color, appearance, and performance requirements for automakers and transport equipment makers.
Geographically, Axalta is broadly diversified across North America, Europe, and faster-growing international markets, which helps reduce dependence on any single country or customer group. The business model is also supported by a mix of recurring demand from vehicle repair and more cyclical demand from industrial production and auto manufacturing.
Over the last several years, the company’s revenue has been fairly stable to modestly rising, while operating income has improved more noticeably. That suggests management has been getting better pricing, product mix, or cost control even when sales growth has not been especially strong.
The business has recently shown a healthier earnings flow than it did a few years ago: sales have stayed around the same general level, but operating profit and net income have improved from earlier troughs. Interest expense remains meaningful, however, which shows that debt still matters to the investment case.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Specialty Chemicals | |
| Market Cap ⓘ | $7.22B | |
| Beta ⓘ | 1.26 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 20.71 | 16.92 |
| P/B Ratio ⓘ | 3.03 | 1.66 |
| FCF Yield ⓘ | 6.85% | 5.83% |
| Dividend Yield ⓘ | N/A | 2.07% |
| EBIT / EV ⓘ | 7.28% | 6.38% |
| PEG ⓘ | 2.04 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 3.10% | 11.25% |
| RPS Growth (5Y CAGR) ⓘ | 5.49% | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | -3.97% | -15.24% |
| BVPS Growth (5Y CAGR) ⓘ | 14.15% | 5.49% |
| Margin Growth (5Y Trend) ⓘ | 3.69% | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | 0.90% | 0.37% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 5.91% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 8.32% | 9.59% |
| ROA (Latest) ⓘ | 4.52% | 4.92% |
| ROIC (5Y Median) ⓘ | 8.56% | 7.91% |
| ROA (5Y Median) ⓘ | 3.73% | 3.92% |
| Net Debt / EBIT (Latest) ⓘ | 3.57 | 1.36 |
| Net Debt / EBIT (5Y Median) ⓘ | 4.95 | 1.69 |
| Net Debt / EBITDA (Latest) ⓘ | 2.47 | 0.93 |
| Net Debt / Assets ⓘ | 31.63% | 13.69% |
| EBITDA / Interest ⓘ | 5.80 | 12.38 |
| Operating Margin (Latest) ⓘ | 13.26% | 13.24% |
| Operating Margin (5Y Median) ⓘ | 11.33% | 11.82% |
| Debt to Equity (Latest) ⓘ | 121.65% | 40.30% |
| Profit Margin (Latest) ⓘ | 6.78% | 6.38% |
| Free Cash Flow (Latest) ⓘ | $495.00M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +35.53% | +73.47% |
| 12M Return (excl. last month) ⓘ | +5.25% | +27.59% |
| 6M Return ⓘ | +20.25% | -4.02% |
| Price vs. 200-Day MA ⓘ | +8.54% | -0.65% |
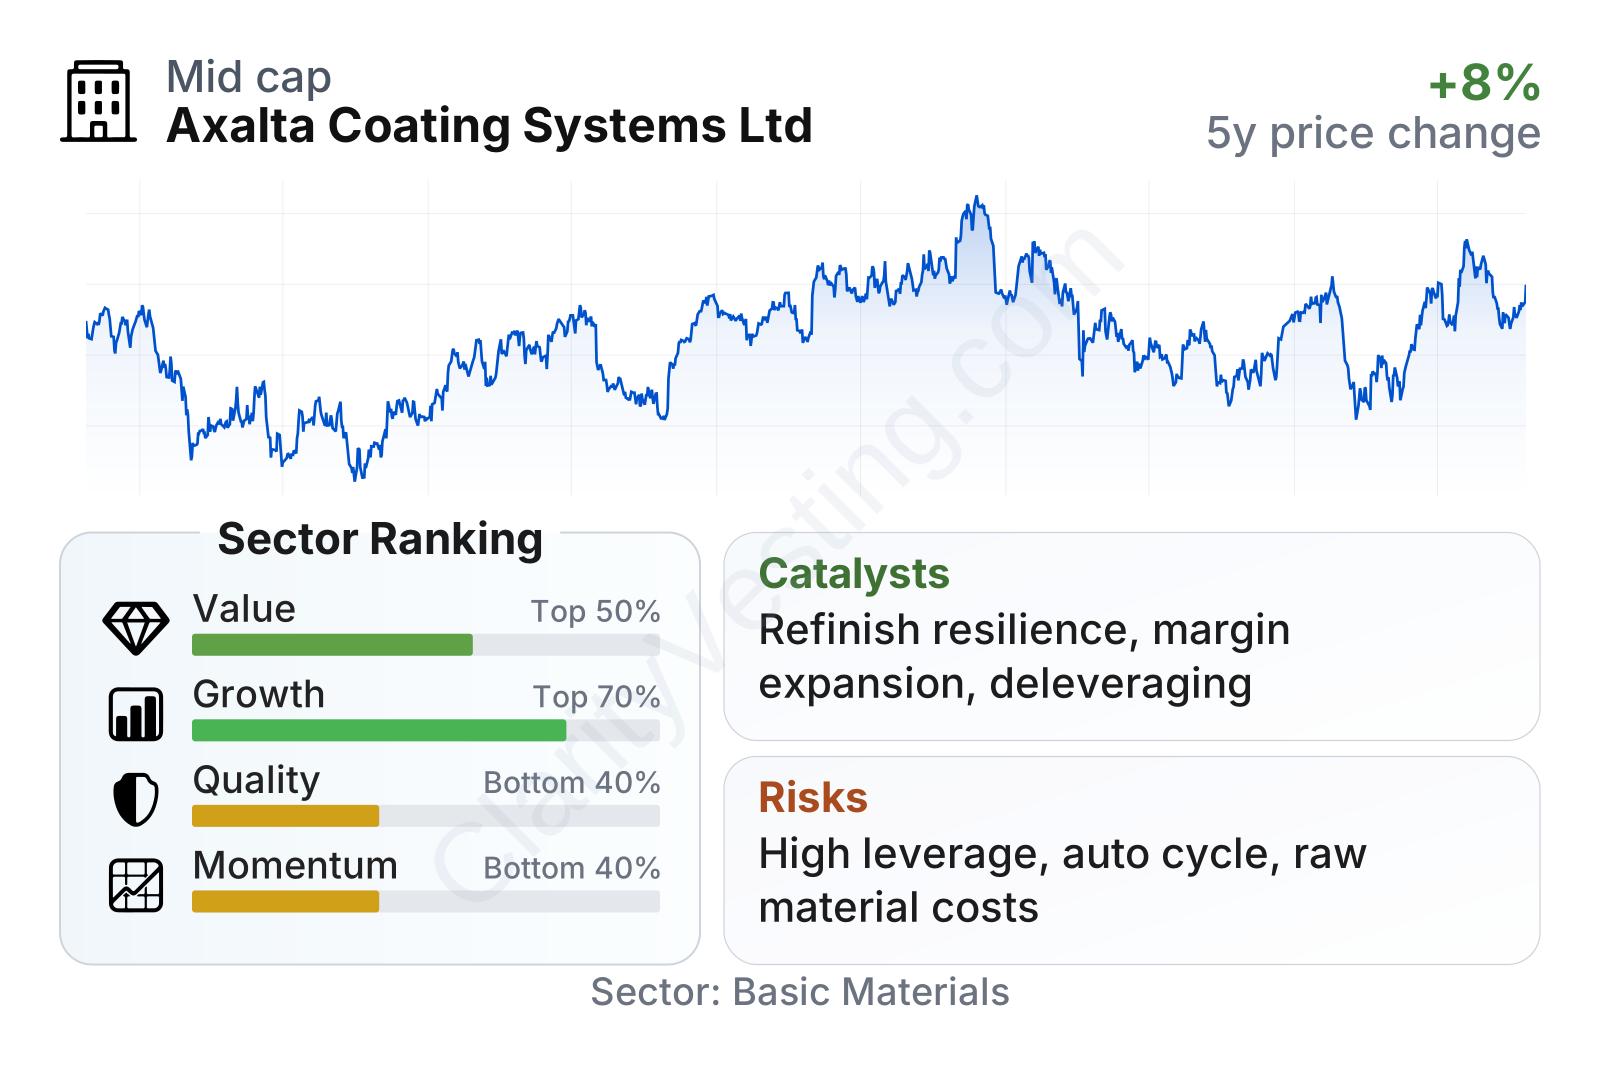
Axalta sits in the mid-to-upper range of its sector on valuation and growth measures, but less favorably on balance-sheet strength and stock-price momentum. Profitability at the operating level is respectable, and free cash flow generation is solid for a company of its size. The weaker point is leverage: debt-related ratios remain clearly above sector norms, which limits flexibility even though they have been improving.
The stock’s recent path has been volatile rather than steadily compounding. After major swings since 2021, the shares have recovered from weaker periods but have not matched the stronger long-term performance seen in parts of the broader materials sector.
Growth
Axalta operates in a sector with steady long-term demand rather than explosive expansion. Coatings benefit from structural needs that do not disappear easily: vehicles need repair, manufacturers need protective finishes, and industrial customers need products that improve durability and appearance. This makes the sector attractive for consistency, even if it usually does not deliver the fastest top-line growth in the market.
A key advantage in Axalta’s growth profile is the mix between refinish and original equipment exposure. Refinish demand is typically more resilient because it depends on accidents, aging vehicles, and repair activity, while coatings for new vehicle production are more cyclical but can benefit from higher content, new models, and technology shifts in transportation. The combination gives Axalta both stability and some upside to manufacturing recoveries.
Recent revenue growth has been uneven. After a stronger stretch in 2022 and 2023, growth slowed sharply, turned negative through much of 2025, and then moved back into positive territory in mid-2026. That pattern points to a company navigating softer end markets rather than one losing relevance outright. The return to positive growth matters because it suggests recent pressure may have been cyclical, not purely structural.
Management’s strategy has centered on productivity, margin improvement, portfolio management, and higher-value products rather than simply chasing volume. For a coatings company, that approach makes sense. Customers often care about application efficiency, color accuracy, durability, and total system cost, which can support pricing power when the products are embedded in customer workflows.
Cash generation is an encouraging part of the picture. Free cash flow has recovered strongly from earlier weakness and has stayed at a meaningful level more recently, close to the half-billion-dollar range on a trailing basis. That gives the company resources for debt reduction, acquisitions, and share repurchases, even in periods when revenue growth is not particularly strong.
One notable catalyst is the company’s continuing push into technology-rich coatings and customer productivity tools, especially in refinish and premium vehicle applications. Another is any rebound in global auto production or industrial demand, since Axalta is well positioned to benefit when customer factories run harder. The company has also emphasized margin expansion and disciplined capital allocation, which can create earnings growth even without rapid sales expansion.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


